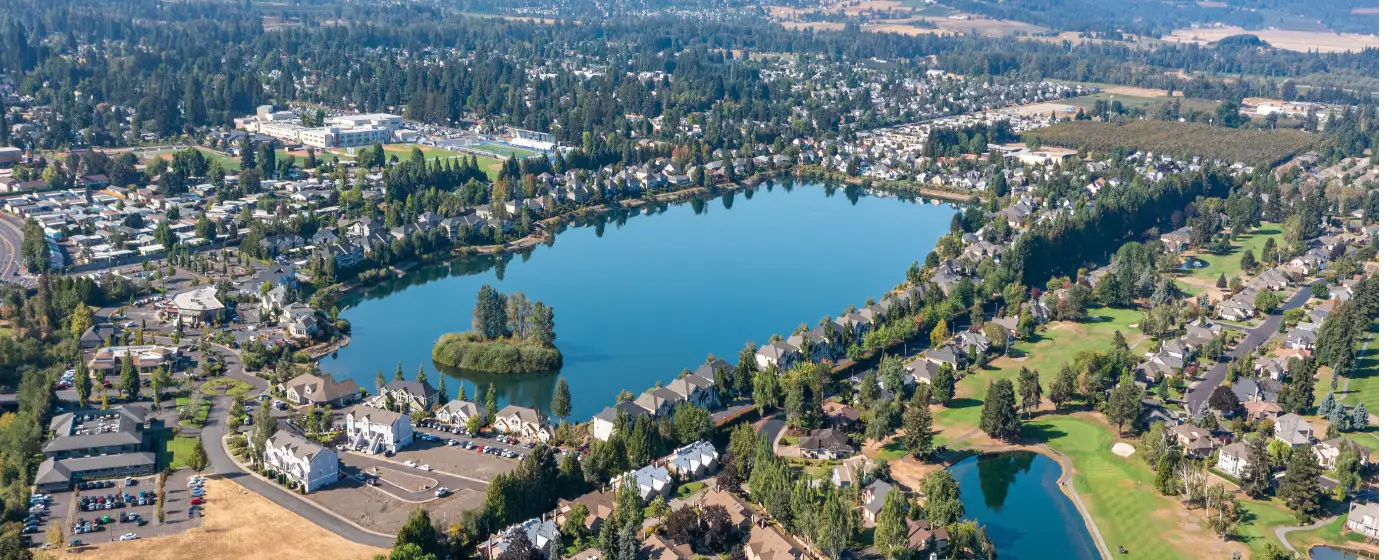
Keizer sits just north of Salem in the Willamette Valley, separated from its larger neighbor by little more than a city limit sign on OR-99E — but with a housing market that first-time buyers are increasingly watching closely. The typical home here is priced at $453,552 (Zillow Home Value Index, July 2026), which puts it within reach of moderate incomes on paper. The honest caveat: the median household income of $84,813 falls about $33,000 short of what most lenders want to see to carry that price comfortably. That gap is the central math problem every first-time buyer in Keizer needs to solve before signing anything.
The city of 39,082 people is compact and largely residential, anchored by the Salem-Keizer Public Schools district and the adjacent government and public-sector employment base that fills the Marion County corridor. Most residents commute about 12 minutes to Salem for work, shopping, or services, which makes Keizer feel like a bedroom community in the best sense — quieter streets, established neighborhoods, and a pace that suits families with school-age children and public-sector workers putting down roots. The Salem-Keizer School District 24J serves the area, rated B- by Niche.com (McNary High School grade) and GreatSchools district overview, with 36,837 students enrolled in 2025-26.
Compared with Portland-area suburbs, Keizer's prices are noticeably lower — and compared with Salem itself, prices are roughly the same, making this less a flight-to-affordability play and more a lifestyle and neighborhood choice. Oregon's cost of living runs modestly above the national average, but Keizer tracks closer to the national average than most of the state. The bigger cash hurdle for buyers here is the combination of down payment and closing costs, which Oregon buyers as a whole have found more demanding than the national average.
Whether you have never owned a home or simply haven't owned a principal residence in the last three years — Oregon's definition of a first-time buyer — this guide breaks down what the Keizer market looks like right now, how the buying process works here step by step, what your cash needs actually are at different price points, and the specific mistakes that catch first-timers off guard in this market.
The Keizer First-Time Buyer Reality
The typical home in Keizer is priced at $453,552 (Zillow Home Value Index, July 2026). That figure buys you a solid, established single-family home — think three bedrooms, a two-car garage, and a yard in a neighborhood like Greater Gubser or West Keizer — but it does not buy you a house that needs no work. Entry-level inventory in the low-to-mid $300,000s does exist, but it moves, and it typically comes with trade-offs in size, condition, or location relative to the better school attendance zones.
The income gap is real. The median household income of $84,813 falls short of what most lenders calculate as the income needed to carry the typical home here — by roughly $33,000. That means many first-time buyers in Keizer are either bringing a meaningful down payment to reduce the monthly load, buying below the median, or co-purchasing with a partner whose income closes the gap. None of those paths are unusual, but all of them require knowing the math before you fall in love with a listing.
Keizer's housing stock is largely established rather than newly built. You are more likely to find 1980s and 1990s ranch-style homes and split-levels than the new construction subdivisions common in faster-growing suburbs. That history means homes can carry deferred maintenance, older roofs, or systems nearing end-of-life — all things an inspection will catch, but only if you do not waive it. For more on how neighborhoods within Keizer compare, see the best neighborhoods guide.
The Homebuying Process in Keizer, Step by Step
Step 1: Get Pre-Approved — Before You Tour Anything
Pre-approval is not a formality in this market. A lender verifies your income, assets, and credit score, then issues a letter stating the maximum loan amount they will offer. Sellers in Keizer expect to see one with any offer. Showing up to a weekend open house without one is fine for browsing; writing an offer without one is not.
For conventional loans, most Oregon lenders want a minimum 620 credit score. FHA loans — which require only 3.5% down — are available to borrowers with FICO scores of 580 or higher, and buyers with scores as low as 500 may still qualify with a 10% down payment. Know your number before you start. A single hard credit pull for a mortgage application does not hurt your score the way multiple pulls over months do.
Step 2: Define Your Search
Commute matters here more than buyers from larger metros expect. Keizer is about 12 minutes to Salem, but if your job is further — in the mid-valley or toward Portland — factor that into which neighborhoods you consider. School attendance boundaries also shift block by block within the Salem-Keizer district; confirm the zone for any specific address before you make it a must-have.
Step 3: Make an Offer
Work with an agent who knows Keizer's established neighborhoods. Your offer will include a purchase price, earnest money (typically 1%–2% of the purchase price), a financing contingency, and an inspection contingency. Do not skip either contingency on a resale home, regardless of competitive pressure. Earnest money goes into escrow and applies toward your closing costs or down payment at the end.
Step 4: Inspection and Appraisal
This is where first-timers most often get surprised. A general home inspection is not optional on a 30-year-old home — and many Keizer homes are exactly that age. Budget for the cost; do not let a tight timeline or a competitive offer pressure you into waiving it. Separately, your lender will order an appraisal to confirm the home's value supports the loan amount. If the appraisal comes in below the purchase price, you will need to negotiate, make up the difference in cash, or walk away.
Step 5: Closing
Oregon closings typically happen through a title or escrow company. You will sign a significant stack of documents and wire your down payment and closing costs. Plan for the full closing cost range — 2% to 5% of the purchase price — and have those funds in a verifiable account well before closing day. The interactive calculator below this section can help you model the monthly payment side; the table in the next section handles the cash-to-close picture.
How Much Home Can You Afford in Keizer
The table below shows estimated cash requirements at several realistic Keizer price points. Closing costs are estimated at 2%–5% of the purchase price, covering lender fees, escrow, title, appraisal, recording fees, and prepaid costs. These are estimates — your actual figures depend on lender, loan type, credit profile, and negotiated seller concessions. The mortgage calculator below the table models the monthly payment side at current rates.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5% down) — entry | $325,000 | ~$11,375 (3.5%) | ~$6,500–$16,250 (2%–5%) | ~$17,875–$27,625 |
| FHA (3.5% down) — city median | $453,552 | ~$15,874 (3.5%) | ~$9,071–$22,678 (2%–5%) | ~$24,945–$38,552 |
| Conventional (3% down) — entry | $325,000 | ~$9,750 (3%) | ~$6,500–$16,250 (2%–5%) | ~$16,250–$26,000 |
| Conventional (3% down) — city median | $453,552 | ~$13,607 (3%) | ~$9,071–$22,678 (2%–5%) | ~$22,678–$36,285 |
| Conventional (5% down) — city median | $453,552 | ~$22,678 (5%) | ~$9,071–$22,678 (2%–5%) | ~$31,749–$45,356 |
| Conventional (10% down) — city median | $453,552 | ~$45,355 (10%) | ~$9,071–$22,678 (2%–5%) | ~$54,426–$68,033 |
One state-level tool worth knowing: Oregon's First-Time Home Buyer Savings Account lets eligible buyers deduct up to $6,285 per individual (or $12,570 for joint filers) annually in contributions and earnings from Oregon taxable income. Accounts must be opened by December 31, 2026, and funds must be used within ten years toward a single-family home purchase — covering down payment, closing costs, appraisal, and loan origination fees. It is a savings vehicle, not a grant, but the tax deduction makes it a meaningful accelerator for buyers building their down payment over one to three years.
Looking to buy in Keizer? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Keizer quote.
Common First-Time Buyer Mistakes in Keizer
Touring Without Pre-Approval
It happens constantly. A buyer spends three weekends walking through homes in McNary Estates and Northeast Keizer, settles on a target, and then discovers mid-process that their debt-to-income ratio or credit score disqualifies them for the price point they've been shopping. Pre-approval takes a few days and costs nothing. Do it before the first showing, not after the emotional attachment is already set.
Underbudgeting the Cash-to-Close
The down payment gets all the attention, but closing costs — running 2% to 5% in Oregon — can match or exceed it at lower price points. A buyer putting 3% down on a $325,000 home needs roughly $9,750 for the down payment and up to $16,250 more for closing costs. Arriving at the table $10,000 short because you only saved for the down payment is one of the most common and most avoidable surprises in this process.
Waiving the Inspection on an Established Home
Keizer's housing stock is largely from the 1970s through the 1990s. Roofs, HVAC systems, and electrical panels on homes that age have finite remaining life. In a competitive offer situation, waiving an inspection contingency to look stronger feels tempting — but on a 40-year-old house, it is a genuine financial risk. A better path: shorten the inspection window rather than eliminate it. Most sellers accept a 5-to-7-day inspection period.
Ignoring School Boundary and Commute Details
Two homes on the same street in Keizer can fall into different school attendance zones within the Salem-Keizer district. If a specific school matters to your family, confirm the attendance boundary for the exact address — not the neighborhood name — before making an offer. Similarly, buyers who move here picturing a 12-minute commute to Salem and then land a job in Woodburn or toward Portland should map the actual daily drive before choosing a neighborhood. The commute from the northern reaches of Keizer runs longer than the southern end, and that difference compounds daily. See the living in Keizer guide for a fuller commute picture.
Local Expert Takeaway: Keizer is a genuine entry point into Willamette Valley homeownership — not because prices are low, but because they are lower than Portland's orbit and backed by stable public-sector employment and a real community infrastructure. The honest challenge is the cash gap: between down payment and closing costs, a buyer at the city median needs $25,000 to $40,000 liquid before they close, and the median household income falls short of carrying that price without meaningful savings or a second income. Buyers who come in pre-approved, with their closing cost cash verified and their inspection contingency intact, are the ones who close here without drama.
Quick Takeaways & FAQs
✅ Keizer's typical home price of $453,552 (July 2026) is noticeably below Portland-area suburbs, giving first-time buyers a more realistic entry point into Oregon homeownership.
⚠️ The median household income in Keizer falls about $33,000 short of the income most lenders want to carry the typical home here — cash savings and a realistic budget are not optional.
📍 Oregon defines a first-time homebuyer as anyone who has not owned a principal residence in the last three years, so buyers who previously owned but sold may still qualify for first-time buyer loan programs.
What credit score do I need to buy a home in Keizer, Oregon?
How much do I need saved to buy a home in Keizer?
Is it better to use an FHA or conventional loan in Keizer?
Do I qualify as a first-time homebuyer in Oregon if I owned a home before?
How long does it take to buy a home in Keizer from offer to closing?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
