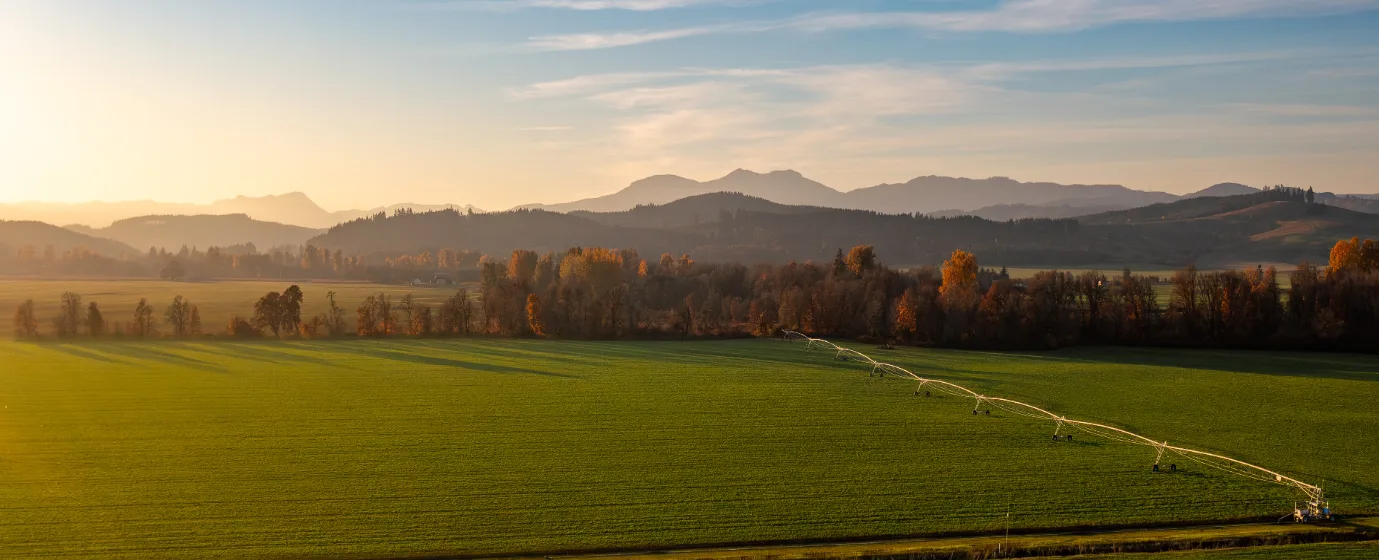
Maybe you've been renting in Salem and someone told you to look west. Maybe you've done the math and realized that $481,280 — the typical home price in Dallas as of July 2026 — buys a real single-family house in a quiet Willamette Valley town rather than a condo on the edge of a metro. That math is real, and it's the main reason first-time buyers are showing up in Dallas at all. What's less obvious from a spreadsheet: the median household income here sits well below what's needed to carry that typical price comfortably, which means your financing strategy matters more than it might somewhere with a thicker job base. Dallas is not an easy market to crack on a starter budget, but it is a possible one — if you go in prepared.
Dallas is a city of 17,531 in Polk County, about 20 minutes to Salem via OR-223 (Kings Valley Highway). The major employers anchor around the public sector — the Dallas School District, Polk County, and City of Dallas government — with a regional health system rounding out the healthcare side. That employment picture is modest, and a lot of residents commute to Salem for work. For buyers who qualify, Dallas (zip code 97338) appears on USDA Rural Development eligible-area lists, which means a no-down-payment path is worth asking a lender about before you rule it out. Property-level eligibility has to be confirmed parcel by parcel, so treat that as a conversation starter, not a guarantee.
On the cost side, Dallas sits noticeably below Salem prices, and even farther below what you'd pay in the Portland metro — a meaningful difference on a first-time budget. Buyer closing costs in Oregon typically run 2% to 5% of the purchase price, covering origination fees, appraisal, escrow setup, and recording — and knowing that range before you make an offer is what separates buyers who close from buyers who get surprised at the table. The cost of living page covers the full tax and expense picture for the area.
Whether you're a true first-timer or someone who hasn't owned a principal residence in the past three years — Oregon uses HUD's definition, so more people qualify than you'd think — the sections below walk through what your budget actually buys in Dallas, the step-by-step buying process, a set of realistic budget scenarios, and the mistakes local buyers most often make on the way to closing.
The Dallas First-Time Buyer Reality
The typical home in Dallas sold for $481,280 as of July 2026 (Zillow Home Value Index). That number is real, and it puts the entry point for homeownership here above what the median household income in Dallas can comfortably carry. That gap doesn't mean buying is impossible, but it does mean most first-timers are either stretching, bringing a strong co-borrower, or targeting something below that figure.
The practical entry point in Dallas for a first-time buyer is somewhere in the low-to-mid $400,000s, where older ranch-style homes and some newer construction start to appear. Properties in that range tend to move, so the window between finding a home and losing it to another offer is short. Coming in without a pre-approval letter is not a strategy; it's a way to watch the home go to the next buyer.
Dallas also sits in a part of Polk County where some properties fall within USDA Rural Development eligible boundaries — a detail worth flagging for buyers whose income falls within program limits and who want to minimize cash at closing. Separately, homes near Rickreall Creek in the northern part of the city may fall within a Special Flood Hazard Area; if your loan is FHA, USDA, or VA, flood insurance would be required on those properties. Ask your lender to check FEMA flood maps for any specific address before you get attached to it. These are the kinds of local details that don't show up in a Zillow search but shape what a purchase actually costs.
The Homebuying Process in Dallas, Step by Step
Step 1: Get Pre-Approved — Not Just Pre-Qualified
In Oregon, sellers routinely decline to consider offers that don't include a pre-approval letter. Pre-qualification, which is a rough estimate based on self-reported numbers, does not meet that bar. Pre-approval requires the lender to verify your income, assets, and debts — resulting in a letter that names the approved loan amount and is typically valid for 30 to 90 days.
The strongest version is a fully underwritten pre-approval, where the lender has reviewed and verified all your documents before you start shopping. In a market like Dallas, where well-priced homes attract attention quickly, that extra step can be the difference between a competitive offer and an also-ran. Gather your two most recent pay stubs, W-2s, two years of tax returns, bank and asset statements, and a government-issued ID before you sit down with a lender.
Step 2: Shop With Purpose
Once pre-approved, work with an agent who knows Polk County specifically — the school district boundaries, the flood zone pockets near Rickreall Creek, and which neighborhoods in Dallas are genuinely walkable versus car-dependent. Salem agents sometimes take Dallas listings but don't always know the street-level reality here. The best neighborhoods in Dallas page covers the character of each area if you're still orienting.
Step 3: Make an Offer
Your offer should include your pre-approval letter and a proposed earnest money deposit — typically 1% to 2% of the purchase price in this market. Oregon is an escrow state, so a neutral title or escrow company will manage the funds and paperwork from accepted offer through closing. Include an inspection contingency; in a first-time purchase, waiving it to compete is almost always the wrong call.
Step 4: Inspection, Appraisal, and Loan Finalization
Oregon practice runs deeper than a standard general inspection. Budget for radon testing and a sewer-line evaluation in addition to the general structural and roof inspection — older homes in Dallas sometimes carry deferred maintenance that a scope reveals before it becomes your problem. The appraisal happens in parallel, ordered by your lender, and must come in at or above purchase price for the loan to proceed as written.
This is also when your lender finalizes the loan file. Any new debt — a car loan, a credit card opened during escrow — can change your debt-to-income ratio and derail an approval that was otherwise solid. Don't open new credit lines between pre-approval and closing.
Step 5: Closing
You'll receive a Closing Disclosure at least three business days before the scheduled closing date, listing the final actual costs. Review it line by line against the Loan Estimate you received earlier. The full timeline from pre-approval to closing in Oregon typically runs 30 to 60 days, though FHA and USDA loans sometimes take longer to process than conventional ones. Show up to the closing table with verified funds — wire or cashier's check — and a valid ID.
How Much Home Can You Afford in Dallas
Closing costs in Oregon run 2% to 5% of the purchase price. The table below uses a midpoint of 3% as the estimate — your actual figure will depend on the lender, the loan type, and how the seller negotiates. The cash-needed column combines down payment and estimated closing costs; it does not include reserves, moving costs, or any post-close repairs. Use the mortgage calculator below the table for a payment estimate at current rates.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (3%) | Cash Needed at Table |
|---|---|---|---|---|
| USDA (0% down, if eligible) | $380,000 | $0 | ~$11,400 | ~$11,400 |
| USDA (0% down, if eligible) | $481,280 | $0 | ~$14,440 | ~$14,440 |
| FHA (3.5% down) | $380,000 | ~$13,300 | ~$11,400 | ~$24,700 |
| FHA (3.5% down) | $481,280 | ~$16,845 | ~$14,440 | ~$31,285 |
| Conventional (3% down) | $420,000 | ~$12,600 | ~$12,600 | ~$25,200 |
| Conventional (5% down) | $481,280 | ~$24,065 | ~$14,440 | ~$38,505 |
All figures are estimates for illustration. USDA eligibility requires income to fall within program limits and the specific property to be within an eligible boundary — verify parcel-level eligibility with a USDA-approved lender before planning around it. FHA loans require mortgage insurance premiums that affect your monthly payment; the calculator below accounts for those inputs. Conventional loans with less than 20% down carry private mortgage insurance, which also affects the payment estimate.
Oregon's effective property tax rate is approximately 0.82% — the cost of living page has the full tax picture alongside utility and grocery benchmarks for the area.
Looking to buy in Dallas? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Dallas quote.
Common First-Time Buyer Mistakes in Dallas
Shopping Before Getting Pre-Approved
This one is especially painful in a smaller market like Dallas, where the inventory of homes under $450,000 is limited. A first-timer who falls in love with a home before their lender has seen a single document is setting up for a hard lesson. Sellers here expect a pre-approval letter in hand — not a promise that one is coming.
Waiving the Inspection Contingency to Compete
In a bidding situation, newer buyers sometimes waive inspections to look more attractive. In Dallas, where a share of the housing stock includes older construction from the 1960s through the 1990s, that's a significant gamble. A sewer-scope on a 1970s ranch near downtown Dallas has caught problems that would have cost far more than the inspection itself. Keep the contingency; price it into your offer strategy instead.
Ignoring the Flood Zone Question Near Rickreall Creek
Properties in the northern part of the city that sit within a Special Flood Hazard Area along Rickreall Creek come with a mandatory flood insurance requirement for FHA, USDA, and VA buyers. That insurance cost doesn't appear in the listing price, and buyers who discover it after an accepted offer sometimes find their monthly budget no longer works the way they planned. Check the FEMA flood map for any address before you schedule a showing.
Underbudgeting Cash at Closing
First-time buyers consistently underestimate how much cash the closing table actually requires. A $481,280 purchase with an FHA loan means roughly $31,000 in down payment and closing costs alone — before inspection fees or moving expenses. Those who plan for the down payment but not the closing costs find themselves scrambling in the final week. Build the full cash-needed figure into your savings target from day one, and use the budget table above as your floor, not your ceiling.
Overlooking the Salem Commute Reality
Dallas is about 20 minutes to Salem on a clear day. That's manageable, and a lot of residents make that drive every day for work. What first-timers don't always account for is that commute multiplied five days a week over the life of a mortgage — and that OR-223 is a two-lane state highway that has no good alternative when there's an accident or a slow farm vehicle. If your job is in Salem, factor the commute honestly into whether Dallas works for your daily life, not just your budget. The living in Dallas page covers commute and employer context in full.
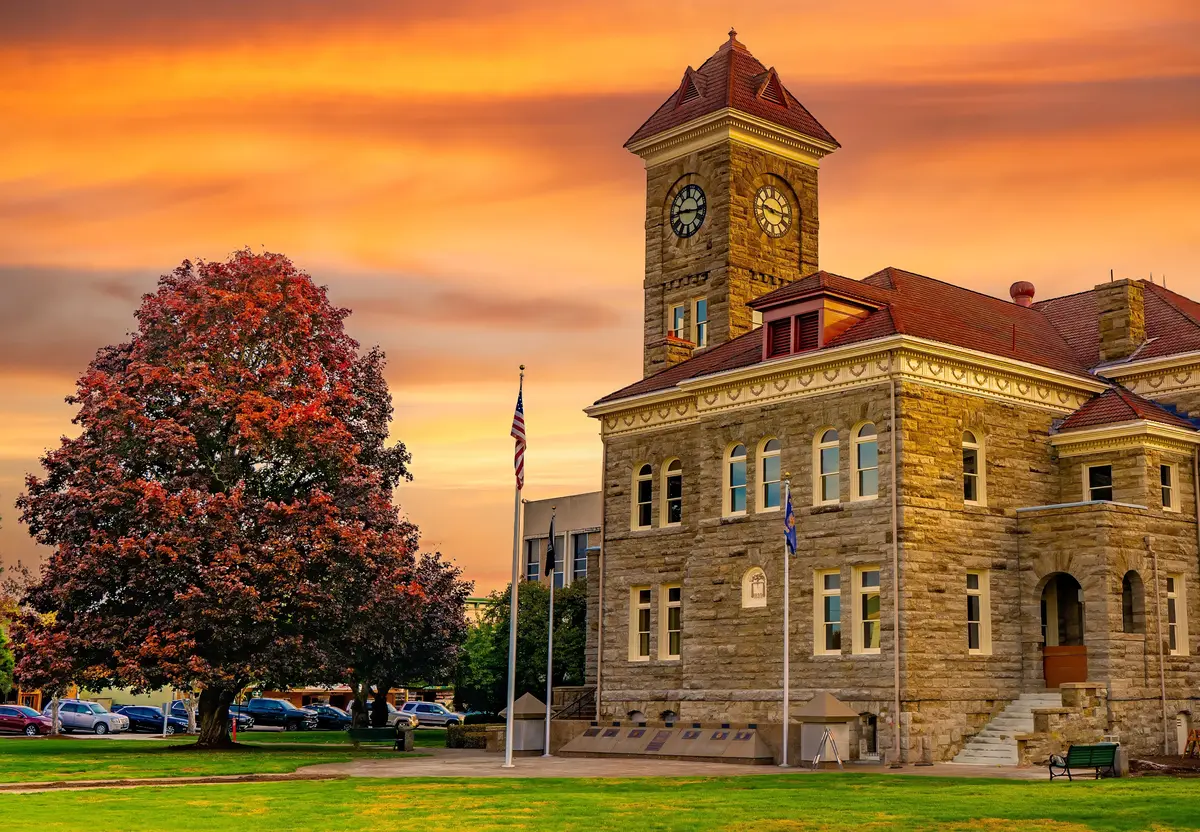
Local Expert Takeaway: Dallas is genuinely one of the more affordable entry points into Willamette Valley homeownership, but 'affordable' is relative — the typical home price sits above what the median household income here can comfortably carry, and the cash needed at closing surprises more first-time buyers than any other part of the process. The buyers who close successfully in Dallas are the ones who get fully underwritten pre-approvals before they tour a single home, ask a USDA-approved lender about parcel eligibility in zip code 97338 before assuming they need a down payment, and check the FEMA flood map on any address near Rickreall Creek before they get attached to it. Go in with your documents ready, your contingencies intact, and a realistic picture of closing cash — and this market is workable.
Quick Takeaways & FAQs
✅ Dallas home prices sit noticeably below Salem and well below the Portland metro, making it one of the more accessible entry points into Willamette Valley ownership for buyers who qualify.
⚠️ The median household income in Dallas falls short of what's needed to comfortably carry the typical home price — financing strategy and loan type matter more here than in higher-income markets.
📍 Some properties in Dallas (zip code 97338) fall within USDA Rural Development eligible boundaries, meaning a zero-down-payment path may be available — but parcel-level eligibility must be confirmed with a USDA-approved lender before counting on it.
What is the typical home price in Dallas, Oregon right now?
Can I use a USDA loan to buy a home in Dallas, Oregon?
How much cash do I actually need to buy a home in Dallas, Oregon?
Do I need a pre-approval letter before I can make an offer in Dallas?
Are there flood zones I should know about when buying in Dallas?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
