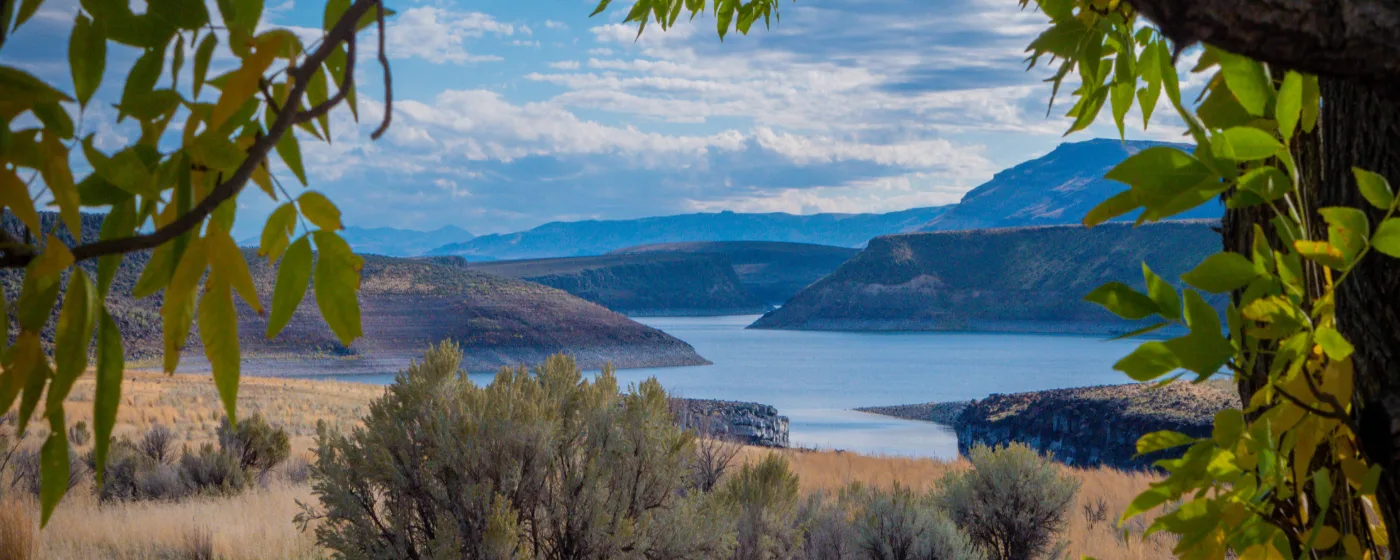
Maybe you've been priced out of Boise or Twin Falls and someone mentioned Rupert. Maybe you're already working at Idahoan Foods or Brewster Cheese and paying rent while wondering if a mortgage might actually be cheaper. The surprise most first-timers get when they pull up listings here is that the numbers actually work — the median sold price in Rupert sat at $266,500 as of January 2026, a figure that makes lenders in Twin Falls do a double-take. Rupert sits at the intersection of Highway 24 and Business I-84 in Minidoka County, roughly 25 minutes east of Twin Falls, with the Snake River just to the north and the agricultural economy that built Magic Valley still running at full speed.
The employment base here is unusually concentrated for a city of about 6,300 people. Idahoan Foods, Brewster Cheese, Snake River Sugar Company, Gossner Foods, and Gem State Processing collectively employ a significant share of the local workforce, and lenders take note — stable, long-tenured employment in the same industry cluster is exactly the income picture underwriters prefer. That stability has attracted a buyer profile that is younger and more working-class than the resort-driven markets two hours north; most people moving here are doing so because the math finally pencils out, not because they fell in love with a lifestyle brand.
Cost of living is the headline, and it delivers. Rupert's prices sit well below Idaho's statewide median, and the effective property tax rate of approximately 0.48% is among the lowest in the region — see the full breakdown on the cost of living page. Day-to-day life revolves around Rupert Square, the walkable civic center anchored by the Historic Wilson Theatre and the DeMary Memorial Library, with Lake Walcott State Park providing outdoor breathing room a short drive north. The compromise is real: limited retail, a modest dining scene, and a commute to Twin Falls for anything more specialized.
Whether you're touring your first open house or still deciding whether Rupert is the right fit, the sections below cover what your budget actually buys here, how the buying process works step by step, an honest affordability snapshot, and the specific mistakes that trip up first-timers in this market.
The Rupert First-Time Buyer Reality
The median sold price in Rupert was $266,500 as of January 2026 — and that figure is not a typo. In a state where prices have climbed sharply over the past four years, Rupert remains one of the few Idaho markets where a household earning close to the local median income can plausibly qualify for a home without an extraordinary down payment. That is the core appeal, and it is genuine.
What that number actually buys is typically a 3-bedroom, 1–2 bath ranch-style home on a standard city lot, often with a detached garage and a yard. Homes below $220,000 still exist but trend toward older construction from the 1950s–1970s, sometimes with deferred maintenance. The Downtown Historic District rewards buyers who want character and walkability to Rupert Square, but homes there may carry historic overlay considerations that affect what you can renovate and how.
The market has softened meaningfully from the frenzy of 2021–2022. As of June 2026, homes were sitting a median of 58 days before going under contract — squarely in balanced territory. Active inventory has grown, with roughly 89 to 106 homes listed depending on the platform. That gives first-timers more room to think than they would have had three years ago. Idaho home prices are still forecast to inch upward 2–4% through the rest of 2026, so waiting for a meaningful price drop is not a strategy most buyers here can afford to count on.
The Homebuying Process in Rupert, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
This is the step most first-timers skip, and it is the one that costs them the most. Pre-approval is not the same as pre-qualification — a pre-qual is a quick estimate based on what you tell the lender; a pre-approval means a lender has pulled your credit, verified your income and assets, and issued a conditional commitment. In Rupert's current market, a seller will often not even respond to an offer without one attached.
Idaho saw a 7.8% year-over-year increase in new mortgage loans through mid-2025, and even smaller Magic Valley markets like Rupert have absorbed that activity. Lenders in the region — including community banks and credit unions in Burley and Twin Falls — are familiar with the local employment base. If you work for one of Rupert's major food processors, bring two years of W-2s and your most recent pay stubs; lenders in rural markets sometimes scrutinize income documentation more carefully when the employer isn't a nationally recognizable name.
Step 2: Shop Within Your Pre-Approved Range — Not Above It
Once you have a pre-approval letter, work with a buyer's agent who covers Minidoka County specifically. Agents based primarily in Burley or Twin Falls may be less familiar with the nuances of Rupert's neighborhoods, including which blocks in the Downtown Historic District carry character overlay restrictions that could affect renovation permits.
Step 3: Make a Competitive Offer — But Don't Waive the Wrong Contingency
With 58 days median time on market, you are unlikely to face a same-day bidding war in Rupert the way buyers did in 2021. That said, well-priced, move-in-ready homes under $250,000 can still attract multiple offers quickly. The inspection contingency is the one first-timers most commonly waive under pressure — and in a market where a significant share of inventory is older ranch-style construction, that is a mistake. Deferred maintenance on roofs, HVAC systems, and older plumbing is common enough here that skipping an inspection to look more competitive is rarely the right trade.
Step 4: Inspection, Appraisal, and the Closing Timeline
After an accepted offer, expect a 30–45 day closing window for financed purchases. Schedule your inspection within the first 10 days — inspectors serving Rupert often also cover Heyburn, Paul, and Burley, so availability can be limited. The appraisal follows and is ordered by your lender; in a market where list prices are sometimes above the sub-$266,500 median sold price, there is a real possibility of an appraisal coming in below purchase price. Negotiate an appraisal contingency, not just an inspection contingency, so you have options if that happens.
Step 5: Closing
Closings in Rupert typically happen at a title company in Burley or Twin Falls. Budget 2–3 business days to receive and review your closing disclosure before the scheduled closing date — federal rules require lenders to deliver it at least three business days in advance. Read it line by line and compare it to your loan estimate; surprises at the closing table in a small market are usually about prepaid items and escrow setup, not lender malfeasance, but you want to catch them before you are sitting across the table.
How Much Home Can You Afford in Rupert
The table below shows estimated cash-to-close requirements at several realistic price points for Rupert first-time buyers. Closing costs are estimated at 2–3% of purchase price, which covers lender fees, title, escrow, and prepaids; your actual figure will vary by lender and loan type. Down payment percentages shown are the program minimums — putting more down lowers your monthly payment and may eliminate private mortgage insurance requirements.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–3%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA minimum (3.5%) | $200,000 | $7,000 (3.5%) | $4,000–$6,000 | ~$11,000–$13,000 |
| Conventional minimum (3%) | $200,000 | $6,000 (3%) | $4,000–$6,000 | ~$10,000–$12,000 |
| FHA minimum (3.5%) — median price | $266,500 | $9,328 (3.5%) | $5,330–$7,995 | ~$14,658–$17,323 |
| Conventional (5%) — median price | $266,500 | $13,325 (5%) | $5,330–$7,995 | ~$18,655–$21,320 |
| Conventional (10%) — updated home | $300,000 | $30,000 (10%) | $6,000–$9,000 | ~$36,000–$39,000 |
| Conventional (20%) — no PMI | $300,000 | $60,000 (20%) | $6,000–$9,000 | ~$66,000–$69,000 |
All figures are estimates for planning purposes only; your lender will provide exact figures in a loan estimate after you apply. The interactive mortgage calculator below lets you adjust price, down payment, and rate to model your specific scenario.
One figure worth anchoring to: Rupert's effective property tax rate is approximately 0.48%, which is low by Idaho standards and meaningfully lower than rates in Twin Falls County. That keeps the tax portion of your monthly housing payment modest relative to what buyers pay in nearby markets.
FHA loans are popular with first-timers here because the 3.5% minimum down payment requires less upfront cash — but they carry an upfront mortgage insurance premium (typically 1.75% of the loan amount, often rolled into the loan) and an annual insurance premium for the life of the loan if you put less than 10% down. Conventional loans at 3–5% down carry private mortgage insurance until you reach 20% equity, but that insurance can be removed without refinancing once you hit that threshold. Talk through both structures with your lender before deciding.
Looking to buy in Rupert? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Rupert quote.
Common First-Time Buyer Mistakes in Rupert
Shopping Before You Have a Pre-Approval Letter
Touring homes in Rupert without a pre-approval in hand is not just premature — it actively works against you. When a well-priced home hits the market under $250,000, it can draw offers within a week. Without a pre-approval letter, your offer is not a real offer. Get the letter first, then start browsing listings.
Underestimating How Much Cash You Need at Closing
First-timers consistently focus on the down payment and undercount everything else. In Rupert, closing costs of 2–3% of purchase price add $5,300 to $8,000 on a median-priced home, on top of your down payment. Then there are prepaid items: homeowners insurance (paid in advance for the first year), property tax escrow setup, and prepaid mortgage interest from closing date to first payment. The total cash-to-close figure is almost always higher than buyers expect — plan for 5–6% of purchase price as a conservative cushion.
Waiving the Inspection Contingency to Look More Competitive
Rupert's housing stock skews older. Many homes in the Downtown Historic District, East Rupert, and the South Side date from the mid-20th century, and deferred maintenance — aging rooflines, galvanized plumbing, older electrical panels — is common. Waiving the inspection contingency on a 1960s ranch to compete with another offer is a gamble that experienced local buyers rarely take. Keep the inspection contingency. Negotiate on price or timeline instead.
Ignoring the Downtown Historic District's Overlay Restrictions
Buyers drawn to the character of homes near Rupert Square and the Historic Wilson Theatre sometimes don't realize that properties within the historic overlay may face restrictions on exterior alterations, material choices, and additions. If you're planning to add a bedroom, replace windows with modern double-pane units, or put up a new fence, confirm with Minidoka County Planning what the overlay permits before you make an offer — not after you close. The DeMary Memorial Library is a good starting point for local permit history if a home has had recent work done.
Local Expert Takeaway: Rupert is one of the few remaining Idaho markets where first-time buyers can realistically close on a home without six figures saved — but 'affordable' does not mean 'easy.' The buyers who succeed here get pre-approved at a local credit union or community lender in Burley before they tour a single property, keep their inspection contingency intact on every offer regardless of competition, and budget for the full cash-to-close figure rather than just the down payment. The market is balanced enough in mid-2026 to give you time to do this right. Use that window.
Quick Takeaways & FAQs
✅ Rupert's $266,500 median sold price (January 2026) is well below the Idaho statewide median, making it one of the most accessible entry points for first-time buyers in Magic Valley.
⚠️ At the median household income of $54,741, total housing costs on a median-priced home can stretch to 37–39% of gross monthly income — pre-approval math matters here before you fall in love with a listing.
📍 Homes near Rupert Square in the Downtown Historic District may carry character overlay restrictions that limit exterior renovations — always confirm permit scope with Minidoka County before making an offer on older downtown properties.
What credit score do I need to buy a home in Rupert, Idaho?
How long does it take to close on a home in Rupert?
Is Rupert a buyer's market or a seller's market right now?
What are typical closing costs when buying a home in Rupert?
Should I use an FHA or conventional loan to buy my first home in Rupert?
Moving to Idaho?
Tell us what you need help with and we'll connect you with local resources.
