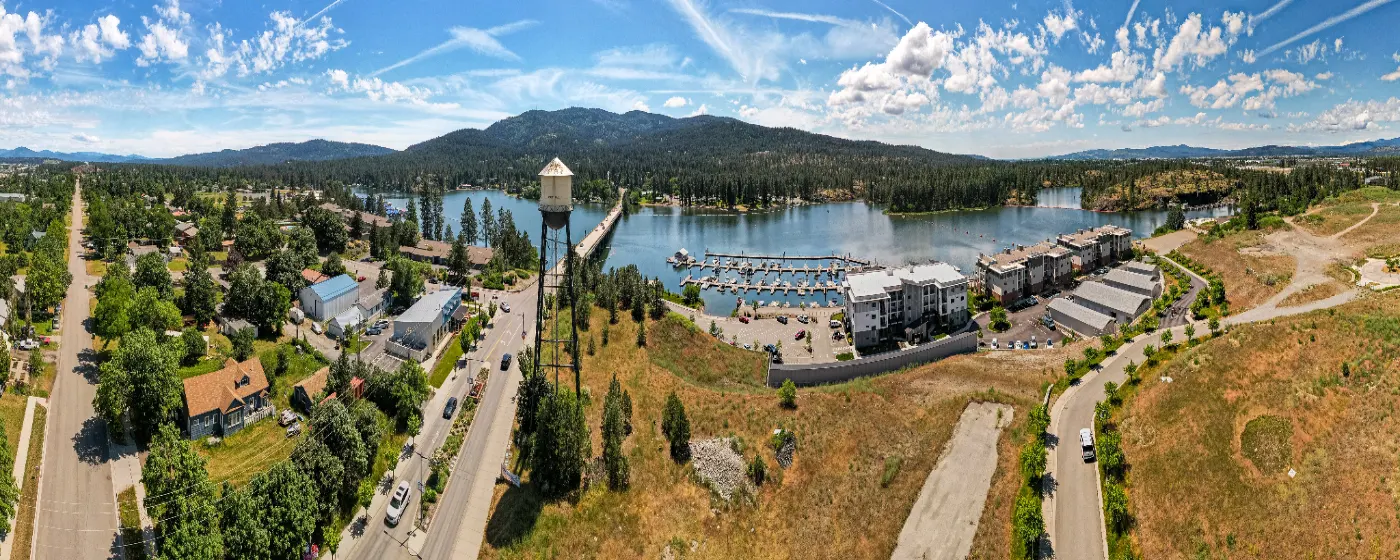
Maybe someone told you Post Falls was the affordable alternative to Coeur d'Alene. Maybe your employer in Spokane is relocating you east and you're realizing Idaho's side of the state line stretches your budget further. Either way, the picture you arrive with rarely survives first contact with the local market. Post Falls scored 82 out of 100 on Redfin's competitiveness scale as of mid-2026 — that's "very competitive" in a city that grew 21% in five years and is projected to nearly double in population by 2045. The Spokane River corridor, the I-90 access, and the relative affordability compared to the Pacific Northwest metros that feed it keep demand consistently above what resale inventory can absorb.
The city's economy is grounded in manufacturing, distribution, and services — Buck Knives, Ground Force Manufacturing, and Sysco Systems anchor local employment — but a large share of the Post Falls workforce commutes outside the city limits, mostly west toward Spokane or east into Coeur d'Alene. That commuter reality matters enormously when you're choosing a neighborhood, because which side of town you land on can shape your daily routine in ways the listing photos never show. First-time buyers who focus only on price and ignore the drive often regret it by month four.
On cost of living, Post Falls sits noticeably below Coeur d'Alene and dramatically below the Seattle and Portland markets that send it the most in-migration traffic. The full cost-of-living breakdown covers this in depth, but the headline is that entry-level single-family homes exist here, which is more than most Pacific Northwest first-timers can say about their home markets. Kootenai County added housing units at the highest annual percentage rate of any Idaho county tracked between 2024 and 2025, meaning new construction is genuinely part of the inventory — something worth understanding before you assume resale is your only path.
Whether you're just starting to research or already watching listings, the sections below walk through what your budget actually buys here, the buying process step by step, a concrete affordability snapshot, and the specific mistakes that cost first-timers money and time in this particular market.
The Post Falls First-Time Buyer Reality
The Zillow Home Value Index for Post Falls stood at $518,467 as of February 2026 — a figure that puts first-time buyers squarely in the territory where a 3% or 3.5% down payment still requires meaningful cash at the table, and where competing against buyers relocating from higher-cost West Coast markets is a genuine daily reality. Seattle, Los Angeles, and Portland collectively drove the most Post Falls search traffic of any metro areas in Q1 2026. Those buyers often arrive with equity from a prior sale. First-timers without that equity need a sharper strategy.
What does that price point actually buy? Detached single-family homes make up 69.4% of Post Falls housing stock — the dominant type, and the category where first-timers have the most options. Entry-level in this market typically means older construction, smaller square footage, or a location farther from the Spokane River corridor. Newer construction in areas like Prairie Falls or Foxtail trends above the city median. If your budget is firmly below $450,000, expect to compete hard for what's available or look seriously at attached housing and townhomes.
Inventory pressure compounds the challenge. Idaho statewide saw total homes for sale decline year-over-year in early 2025 even as new listings rose — a sign that owners locked into low prior-rate mortgages are staying put. Post Falls is specifically identified among Idaho cities with "exceptionally" intense competition. That's not a reason to wait; prices have trended upward and the growth projections for Kootenai County suggest demand isn't softening. It is a reason to enter the process more prepared than you think you need to be.
The Homebuying Process in Post Falls, Step by Step
Step 1: Get Pre-Approved Before You Do Anything Else
In a market scoring 82 out of 100 on competitiveness, touring homes without a pre-approval letter is not just inefficient — it's a disqualifier. Sellers in Post Falls routinely receive multiple offers within days of listing, and listing agents will tell their clients to deprioritize buyers who haven't documented their financing. Get the letter first. Then start the Zillow browsing.
Pre-approval means submitting actual documentation — W-2s, pay stubs, tax returns, bank statements — to a lender who runs your credit and issues a conditional commitment. A pre-qualification (the quick online form) is not the same thing and will not carry weight in a competitive offer situation. Work with a lender familiar with Idaho transactions; closing timelines and title customs here differ from California or Washington practice.
Step 2: Define Your Search Parameters Honestly
Post Falls spans enough geography that neighborhood location materially affects your daily routine. If you're driving to Spokane regularly, where you land in the city shapes your mornings differently than it would for someone working locally. Map your employer's address before you fall in love with a listing.
School boundary lines also shift as the city grows — and they don't always follow the neighborhood names you see in listings. Confirm the actual assigned school for any property you're seriously considering rather than assuming by zip code or subdivision name.
Step 3: Make a Competitive Offer
In a hot listing situation, the two steps first-timers most often get wrong are: offering below asking price on a well-priced home, and writing an offer without an escalation clause when competing against multiple buyers. A local agent who tracks days-on-market by neighborhood is worth more than any national estimate of what a home "should" cost. Homes in Post Falls have been selling at or above asking price in competitive situations — walking in with a lowball offer on a fresh listing signals to a seller that you don't understand the market.
The inspection contingency is your most important protection. Keep it. Waiving inspection entirely to win a bidding war is a risk that first-timers — without equity cushion from a prior home — can rarely afford to absorb if a problem surfaces post-closing.
Step 4: Inspection, Appraisal, and the Final Stretch
Idaho uses attorney-free closings — a title company handles the transaction. Once you're under contract, expect roughly 30–45 days to closing depending on your loan type. FHA loans can take longer than conventional, partly due to property condition requirements. If you're buying a home built before 1978 or with visible deferred maintenance, ask your lender upfront whether the property is likely to pass FHA appraisal standards — finding out at the appraisal stage is a costly delay.
Closing costs in Idaho typically run 2%–3% of the purchase price on top of your down payment. Budget for them separately; they are not optional and they are not small. The interactive calculator below this section can help you model the full cash picture for your specific price point.
How Much Home Can You Afford in Post Falls
The table below models what different purchase prices and loan types require as cash at closing. Down payment percentages are minimums for each loan type; closing costs are estimated at 2.5% of the purchase price as a planning baseline. Idaho's effective property tax rate is approximately 0.60% — among the lower rates in the region — but the interactive calculator below this section will let you model your specific monthly total once you enter your price, rate, and down payment.
Idaho's 30-year fixed mortgage rate was running at 6.75% as of early August 2026 (per Zillow Home Loans), which is the rate environment shaping affordability for buyers entering the market now. These scenarios use round figures for planning purposes; your actual costs will vary by lender, loan type, and negotiated seller credits.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2.5%) | Cash Needed at Table |
|---|---|---|---|---|
| FHA minimum (3.5%) | $400,000 | $14,000 (3.5%) | ~$10,000 | ~$24,000 |
| Conventional minimum (3%) | $400,000 | $12,000 (3%) | ~$10,000 | ~$22,000 |
| FHA — at city median | $518,000 | $18,130 (3.5%) | ~$12,950 | ~$31,080 |
| Conventional — at city median | $518,000 | $15,540 (3%) | ~$12,950 | ~$28,490 |
| Entry-level new construction | $550,000 | $19,250 (3.5%) | ~$13,750 | ~$33,000 |
| Conventional with 10% down | $518,000 | $51,800 (10%) | ~$12,950 | ~$64,750 |
A 10% down payment on a median-priced home eliminates private mortgage insurance thresholds common on lower-down conventional loans and meaningfully reduces your monthly obligation — worth modeling if you have the savings. VA and USDA loans offer 0% down for qualifying buyers; your lender can confirm eligibility based on service record and property location respectively.
Looking to buy in Post Falls? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Post Falls quote.
Common First-Time Buyer Mistakes in Post Falls
Waiving the Inspection to Win
In multiple-offer situations, some buyers waive the inspection contingency entirely to make their offer more attractive. In Post Falls — where a significant share of the resale inventory is older construction and winters are hard on roofing, foundations, and HVAC systems — this is one of the higher-risk moves a first-timer can make. Consider an inspection contingency with a shortened timeline (5–7 days instead of 10) rather than eliminating it. That compromise keeps you protected without putting your offer at a structural disadvantage.
Shopping Before Pre-Approval
Post Falls listings in desirable price ranges routinely go under contract within days. Buyers who find a home they love and then start the pre-approval process — even if it only takes 48 hours — will lose to buyers who walked in ready. Beyond the competitive issue, shopping without pre-approval often leads to touring homes outside your actual qualifying range, which is an emotionally expensive habit to develop. Get the letter before you set foot in a showing.
Underestimating the Cash Required
First-timers consistently budget for the down payment and forget that closing costs arrive as a separate check. At a $518,000 purchase price, 2.5% in closing costs adds roughly $13,000 on top of your down payment — cash the seller is not covering unless you've specifically negotiated a seller concession. Reserves matter too: lenders want to see that you have funds remaining after closing, and having nothing left in the bank the day you get your keys is a financially precarious start to homeownership.
Ignoring Location Within the City
Post Falls covers more ground than most buyers expect, and the part of town you choose shapes daily life in ways the listing photos don't capture. Before making an offer, drive to your workplace from the property — at the time of day you'd actually leave — rather than relying on a map app's optimistic estimate. The experience of living in North Prairie versus West Seltice is meaningfully different, independent of price, and that difference compounds over months of daily routine. Local agents who work this market regularly can tell you which pockets tend to suit which lifestyles; use that knowledge before you sign.
Local Expert Takeaway: Post Falls is genuinely more accessible than Coeur d'Alene for a first-time buyer, but 'more accessible' doesn't mean easy. The market is competitive, cash requirements are real, and the buyers you're competing against often arrive with West Coast equity behind them. Your edge as a first-timer is preparation: pre-approval letter in hand before you tour, inspection contingency intact, and a realistic picture of which neighborhoods fit your work location and lifestyle. Kootenai County's pace of new construction means you have options beyond resale — but those homes move quickly too, and builders in active subdivisions like Prairie Falls sometimes accept contingent offers only when inventory is high. Know your cash position before you walk into a model home.
Quick Takeaways & FAQs
✅ Kootenai County added housing units faster than any Idaho county between 2024 and 2025, giving Post Falls first-timers real new-construction options alongside resale inventory.
⚠️ Post Falls scored 82/100 on Redfin's competitiveness scale — offers without a pre-approval letter are routinely ignored in this market, even at the entry level.
📍 Closing costs in Idaho typically run 2%–3% of the purchase price and arrive as a separate cash requirement on top of your down payment — budget for both from the start.
What is the median home price in Post Falls, Idaho?
How much cash do I need to buy a home in Post Falls as a first-time buyer?
Is Post Falls a competitive housing market for first-time buyers?
What loan types are available to first-time buyers in Post Falls?
Should I waive the home inspection to win a bidding war in Post Falls?
Moving to Idaho?
Tell us what you need help with and we'll connect you with local resources.
