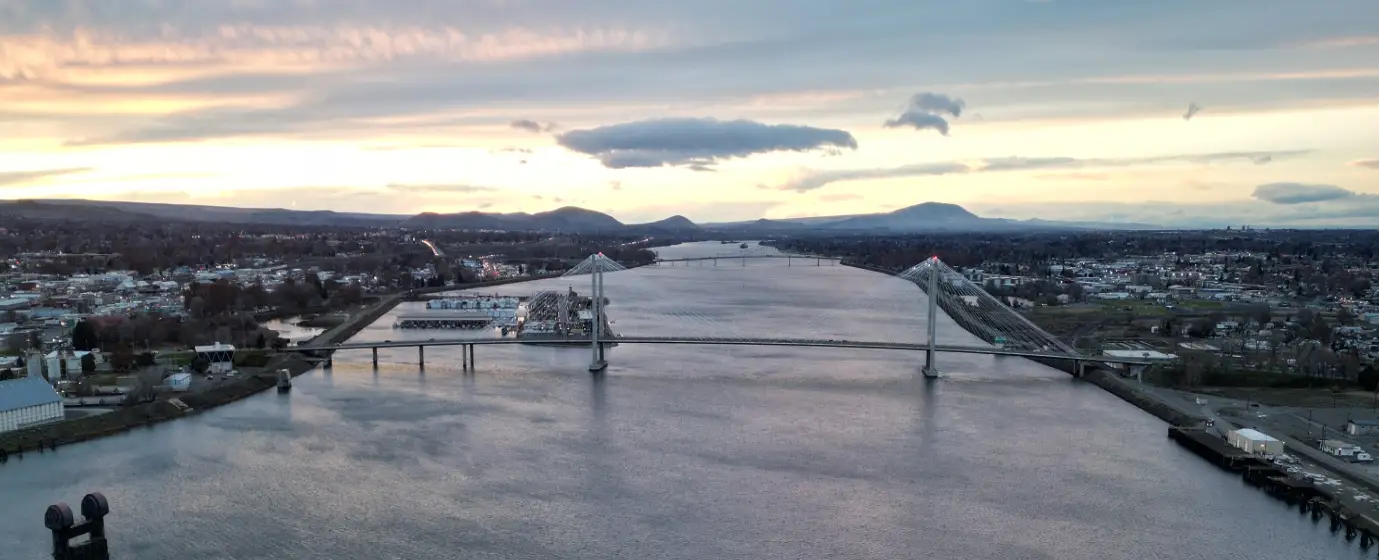
Maybe your company is transferring you to the Hanford Site or Pacific Northwest National Laboratory, and someone in HR mentioned West Richland as the quieter alternative to Richland proper. Maybe you've been renting in Kennewick and your landlord just raised the rent again. Whatever brought you here, the first thing to understand about buying in West Richland is that the market does not reward hesitation. Homes are spending a median of approximately 5 days on market as of mid-2026, and they are routinely selling above their list prices — the sale-to-list ratio sits at roughly 101.3%. That number doesn't sound dramatic until you've lost two offers in a week.
West Richland is a city of about 18,820 people tucked against the Yakima River just west of Richland, anchored economically by the cluster of federal research and cleanup contractors that define the broader Tri-Cities labor market. Families with school-age children represent a significant share of buyers here, which is part of why entry-level inventory disappears so quickly. The Van Giesen Street corridor is mid-renovation through December 2026, adding lanes, sidewalks, and curbing that will reshape the city's commercial spine.
On price, West Richland sits at a Zillow Home Value Index typical value of $499,865 for 2026 — meaningfully below what comparable suburban inventory costs in the Seattle metro, but not a bargain market by Tri-Cities standards. That figure reflects a competitive, growing city where new single-family permits (109 issued through early September 2025) are being absorbed quickly. Washington State 30-year fixed mortgage rates are running approximately 6.75% as of late August 2026, so the math on monthly payments is real and worth running carefully before you fall in love with a house.
Whether you're making your first offer or just starting to research, the sections below walk through what a first-timer's budget actually buys here, the step-by-step purchase process, a plain-numbers affordability snapshot, and the specific mistakes that keep costing first-time buyers in this market.
The West Richland First-Time Buyer Reality
The Zillow Home Value Index puts the typical West Richland home at $499,865 for 2026. That figure is the realistic center of the market — not the floor. Entry-level inventory, meaning older construction, smaller square footage, or homes in need of cosmetic work, starts closer to the low-to-mid $400,000s. Genuinely move-in-ready homes in newer subdivisions like Riesling Estates or The Lakes tend to push above that typical value, not below it.
For a first-timer, the honest framing is this: West Richland is a not quite starter-home market. The price point requires a meaningful down payment, solid credit, and — critically — a pre-approval letter in hand before you ever schedule a showing. Sellers here are receiving multiple offers within days of listing. An offer without pre-approval documentation doesn't get taken seriously.
The competitive pressure comes from a specific local dynamic: the Tri-Cities federal employment base — Hanford contractors, PNNL researchers, Battelle staff — produces a high concentration of dual-income households with strong, stable incomes. The median household income of $119,892 reflects that reality. First-time buyers competing in this pool often feel the squeeze most acutely in the $400,000–$480,000 range, where FHA-financed offers run up against buyers putting 10–20% down. Understanding which price bands you can compete in — before you start touring — is the single most important thing a first-timer can do.
The Homebuying Process in West Richland, Step by Step
Step 1: Get Pre-Approved — Fully, Not Just Pre-Qualified
Pre-qualification is a phone call and a soft credit pull. Pre-approval is a full underwritten commitment, with income documents verified and credit reviewed. In a market where homes go under contract in roughly 5 days, sellers and their agents treat anything less than a full pre-approval as a soft offer. Get the real document before you tour a single home.
Step 2: Set Your Real Search Range
Your pre-approval letter will show a maximum. Your actual search range should be 10–15% below that ceiling, leaving room to compete at or above list price without blowing your budget. In West Richland's current market, offering at list is the starting point — not a winning strategy. Budget your offer price, not just your purchase price.
Step 3: Work With an Agent Who Knows the Local Inventory Pipeline
West Richland's new construction pipeline — 109 permits issued through early September 2025 — means some first-timers successfully buy from a builder and avoid the multiple-offer scramble. An agent plugged into what's coming to market along the Van Giesen corridor or in developing neighborhoods like Watermark can be the difference between bidding against five buyers and being first in line.
Step 4: Make a Competitive Offer — With the Right Contingencies
First-timers often make one of two opposite errors: they either waive every contingency to compete, or they load up an offer with so many conditions it reads as weak. The middle path in West Richland is to protect yourself on inspection and financing, but to keep your inspection period tight — 5 to 7 business days is standard here — and to show an earnest money deposit that signals commitment. Escalation clauses (automatically beating competing offers up to a cap) are common and worth discussing with your agent.
Step 5: Inspection, Appraisal, and the Closing Stretch
Washington State requires a seller disclosure statement, and West Richland's growing stock of newer construction means many homes will be clean — but not all. Inspection results are your negotiation lever, not a reason to automatically walk away. Your lender will order an appraisal; in a market where offers routinely exceed list price, an appraisal gap (where the appraised value comes in below the purchase price) is a real risk. Discuss with your lender how you'd handle that gap before you make an above-list offer. Closing in Washington typically takes 30–45 days from accepted offer to keys.
The step first-timers most consistently underestimate is Step 1 — not because they don't know it matters, but because they start shopping online first and fall in love with homes before they know what they can actually finance. By the time they get the pre-approval, the house is gone.
How Much Home Can You Afford in West Richland
The table below shows estimated cash requirements at closing for several realistic West Richland purchase scenarios. These are estimates — closing costs vary by lender, title company, and negotiated seller concessions. Use these as planning anchors, not guarantees. The engine below the table will run payment estimates for your specific scenario.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5% down) — entry-level | $400,000 | $14,000 (3.5%) | $8,000–$12,000 | $22,000–$26,000 |
| FHA (3.5% down) — near median | $460,000 | $16,100 (3.5%) | $9,000–$13,000 | $25,100–$29,100 |
| Conventional (3% down) — entry-level | $400,000 | $12,000 (3%) | $8,000–$12,000 | $20,000–$24,000 |
| Conventional (3% down) — near median | $499,865 | $15,000 (3%) | $10,000–$14,000 | $25,000–$29,000 |
| Conventional (5% down) — mid-market | $499,865 | $25,000 (5%) | $10,000–$14,000 | $35,000–$39,000 |
| Conventional (10% down) — above median | $550,000 | $55,000 (10%) | $11,000–$15,000 | $66,000–$70,000 |
A few things worth knowing about these numbers. FHA loans require mortgage insurance premiums (an upfront fee rolled into the loan, plus a monthly premium) — your total payment will be higher than a conventional loan at the same purchase price, even if the down payment is lower. Conventional loans with less than 20% down carry private mortgage insurance (PMI) that drops off once you hit sufficient equity, which is a meaningful long-term advantage over FHA in most cases.
Washington has no state income tax, which affects how buyers from other states should recalibrate their budget math. The effective property tax rate in West Richland is approximately 1.07% annually — factor that into your ongoing cost picture even though the interactive calculator below handles the detailed payment breakdown.
One honest caution: in a market where offers are routinely landing above list price, your cash-needed figure can change fast. If you're targeting a $460,000 home and you offer $475,000 to win it, your down payment percentage is now calculated on $475,000 — not $460,000. Plan for a 5–10% buffer above your target-scenario cash number.
Looking to buy in West Richland? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a West Richland quote.
Common First-Time Buyer Mistakes in West Richland
Mistake 1: Shopping Before You Have Pre-Approval
This sounds obvious, and first-timers still do it constantly. Scrolling listings and scheduling tours before your pre-approval is complete means you'll see homes you cannot move on fast enough to buy. In a market where the median days on market is roughly 5 days, the window from "I found a house I love" to "that house is under contract" can be 72 hours. Your pre-approval needs to exist before your first showing, not during.
Mistake 2: Waiving the Inspection Contingency to Compete
Some buyers, frustrated after losing multiple offers, start waiving inspection contingencies entirely. That's a significant financial risk in any market — and West Richland's mix of newer subdivisions and older ranch-style homes means conditions vary widely from street to street. A better move: keep the inspection contingency, but commit to a tight timeline and make clear you'll work collaboratively on findings rather than using inspection as a renegotiation tool. Sellers respond to that framing.
Mistake 3: Assuming Address and Boundary Details Don't Matter
West Richland's newer subdivisions and developing areas near the Van Giesen corridor can sit in unexpected pockets where city services, utility districts, or other address-tied details vary block by block. Two homes a few streets apart may not share the same service providers or zoning classifications. Before you make an offer on any home you're seriously considering, verify the specific address details that matter to your situation — a 60-second check that buyers consistently skip during the excitement of a fast-moving offer process.
Mistake 4: Underbudgeting the Total Cash Requirement
First-timers consistently focus on the down payment number and underprepare for closing costs. In Washington, buyers typically pay 1.5–3% of the purchase price in closing costs — lender fees, title insurance, escrow, prepaid homeowners insurance, and prepaid property taxes. On a $460,000 purchase, that's roughly $7,000–$14,000 on top of your down payment, before you move a single piece of furniture. Add in an inspection fee ($400–$600 is typical locally), possible appraisal gap coverage if you win an above-list bidding situation, and early maintenance or repair costs on a new-to-you home, and the real cash requirement is almost always higher than the down payment figure suggests. Budget for all of it, not just the down payment line.
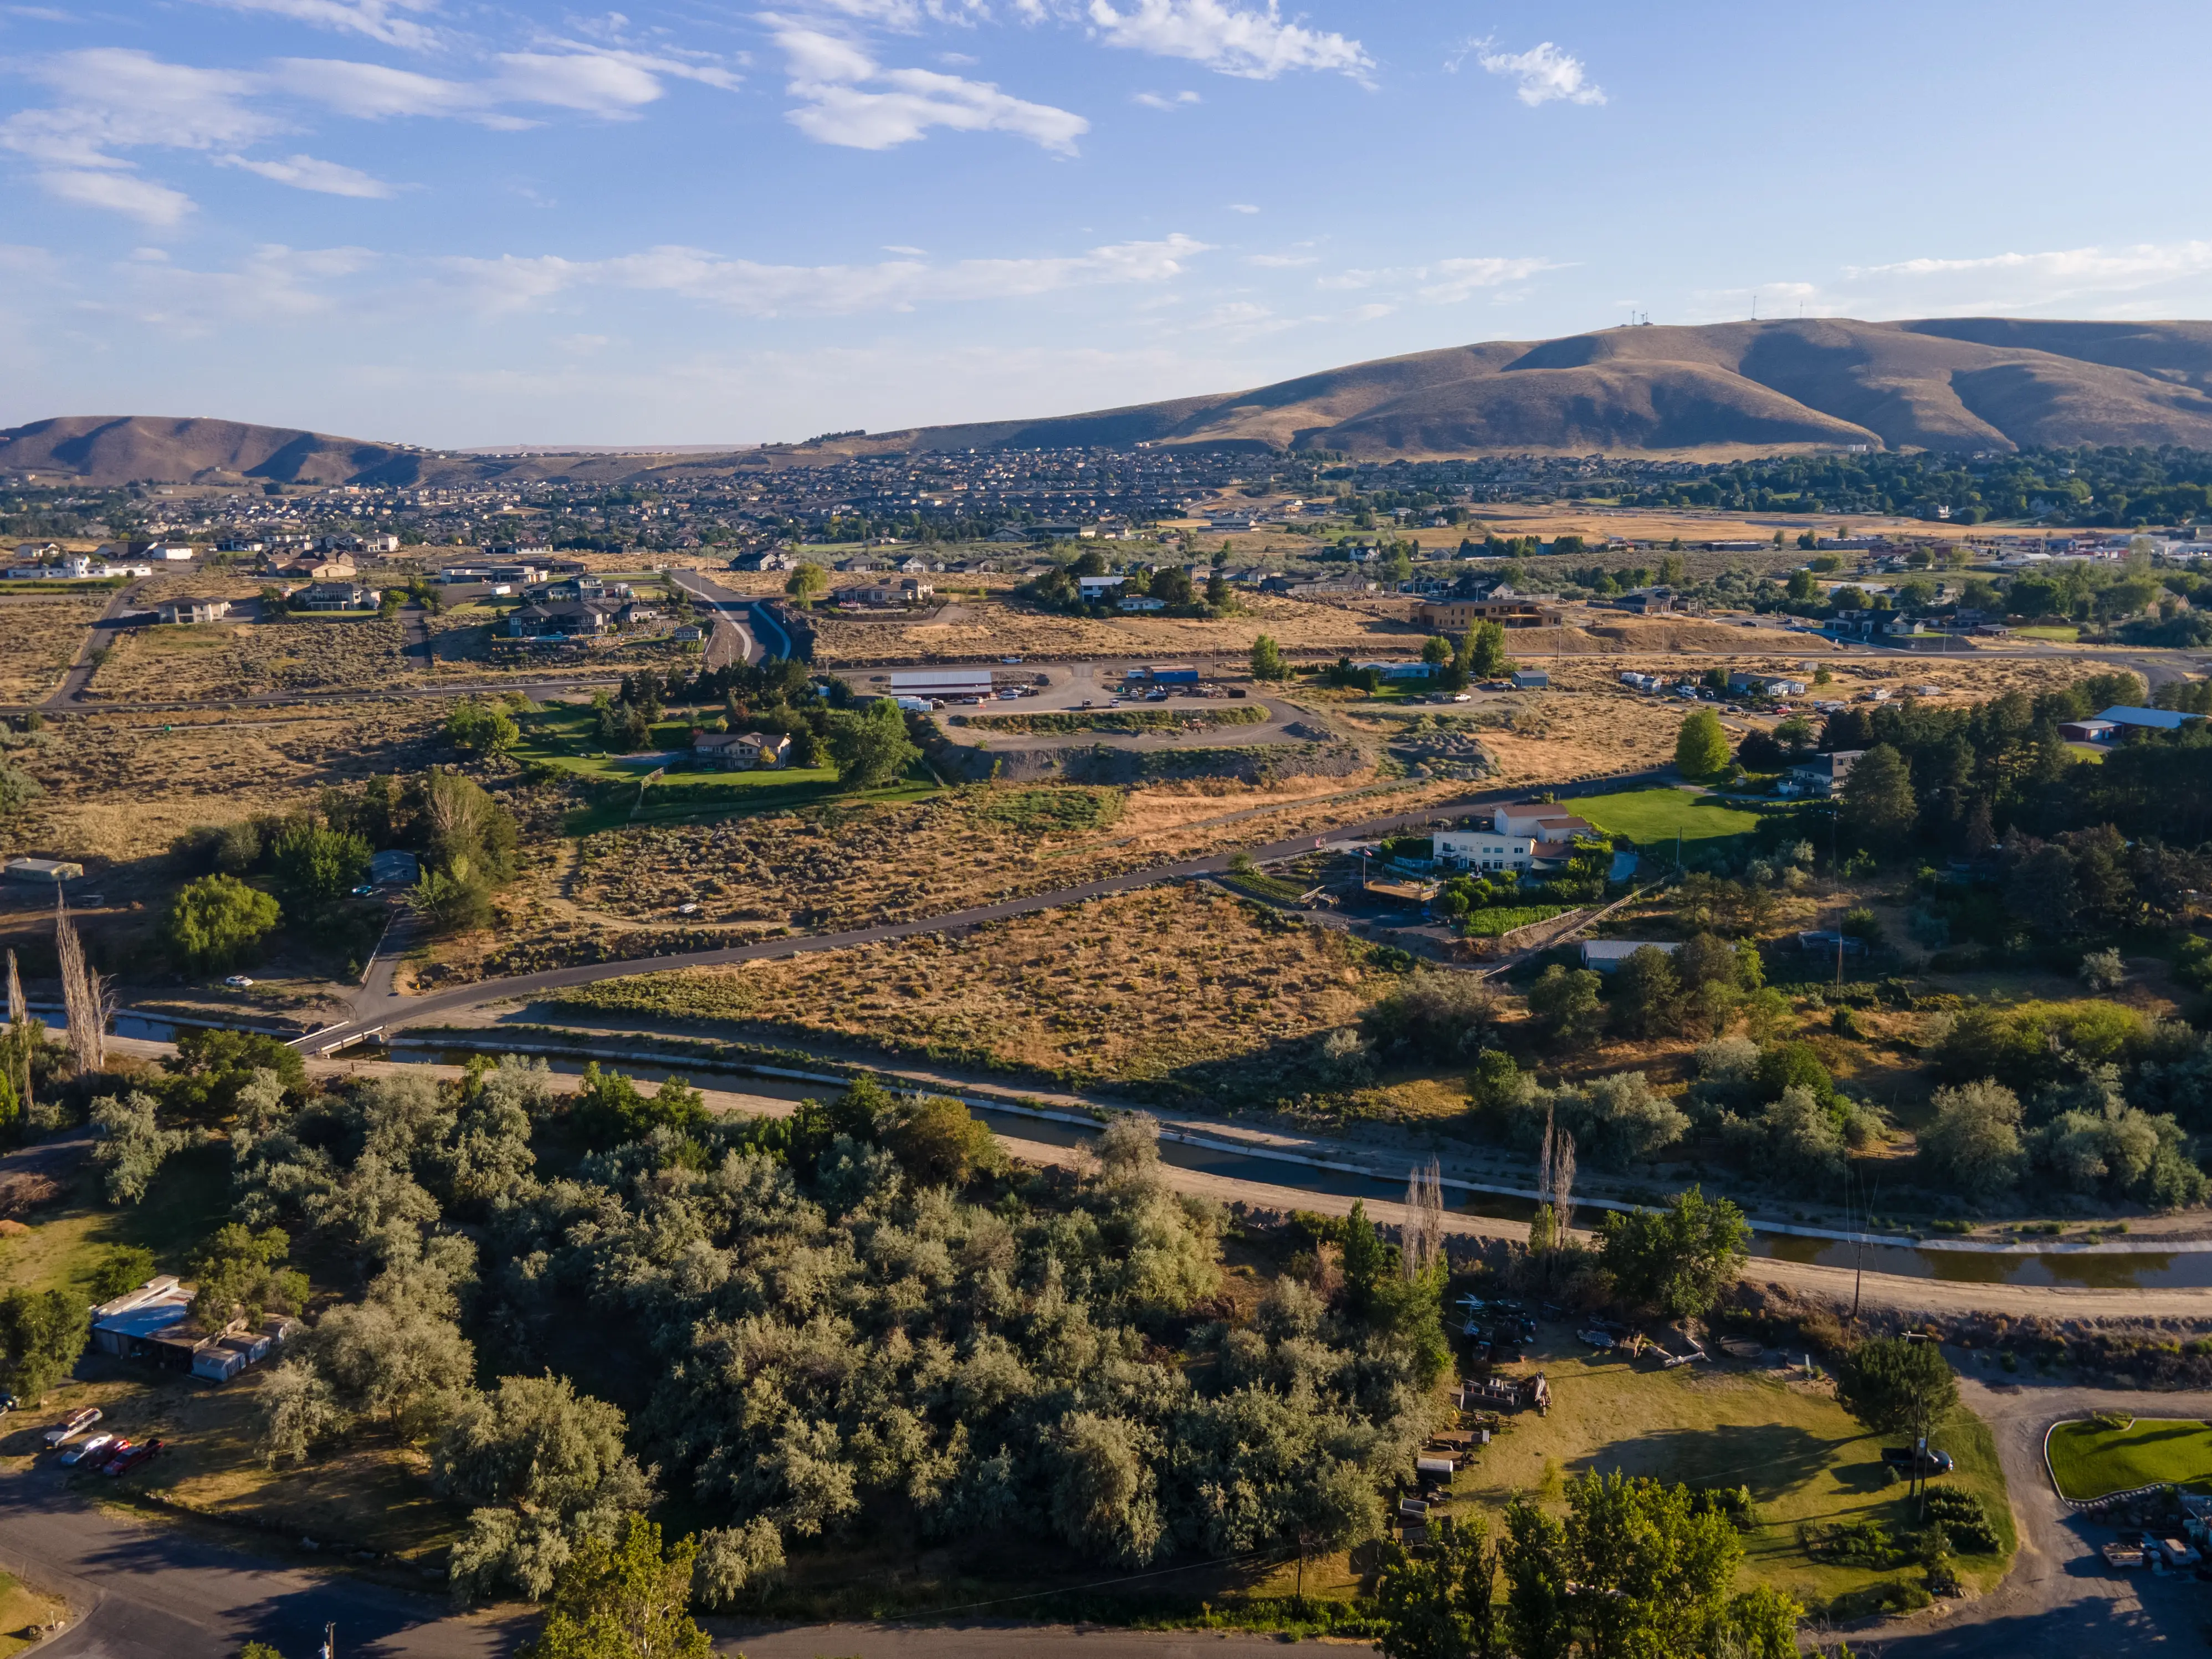
Local Expert Takeaway: West Richland's first-time buyer window is real, but it's narrow. The typical home value sits just under $500,000, inventory moves in days, and sellers routinely receive above-list offers. The buyers who succeed here are the ones who get fully pre-approved before they tour, leave room in their offer budget to compete, and don't blow their cash reserves on the down payment alone — closing costs and post-move expenses are real. If you're eyeing the Van Giesen corridor's newer developments or the Riesling Estates and Watermark neighborhoods, know that new construction inventory from the city's active permit pipeline is your best shot at avoiding a bidding war. Get the paperwork done first, and you'll be ahead of most of the competition before the listing even hits the market.
Quick Takeaways & FAQs
✅ West Richland's federal employment base — Hanford contractors, PNNL, Battelle — drives a strong, stable buyer pool that keeps the market competitive even when interest rates rise.
⚠️ Homes here are selling in a median of roughly 5 days and routinely above asking price, so touring without a completed pre-approval is a setup for repeated disappointment.
📍 Washington's lack of a state income tax changes the monthly budget math significantly for buyers relocating from California, Oregon, or other income-tax states — factor that into your long-term affordability calculation.
What credit score do I need to buy a home in West Richland?
How fast do homes sell in West Richland?
Is it worth buying new construction in West Richland instead of resale?
What are closing costs like for buyers in West Richland, Washington?
Can I buy a home in West Richland under $400,000?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
