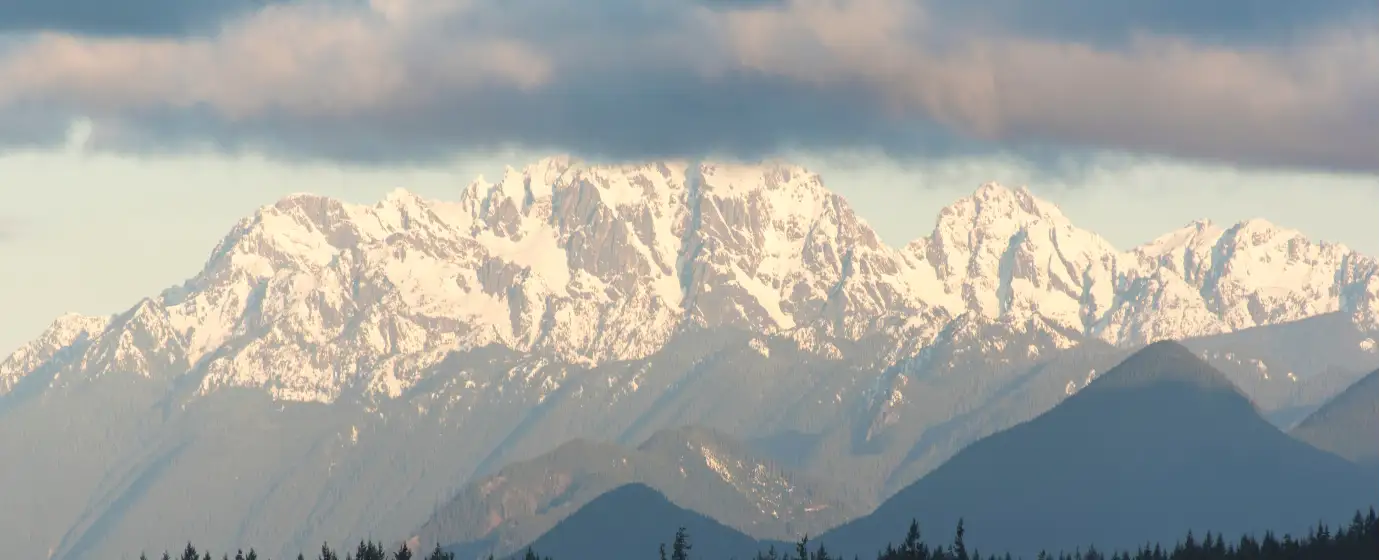
Maybe you've been renting in Bremerton and finally feel ready to buy. Maybe you've been priced out of Gig Harbor and someone pointed you toward Port Orchard as the more affordable side of Kitsap County. Either way, here's what the spreadsheet won't tell you: Port Orchard is growing fast enough that the window for relatively accessible pricing — compared to the broader Puget Sound region — is narrowing. The city sits across Sinclair Inlet from Bremerton, connected by the passenger ferry and framed by waterfront along historic Bay Street, and it has absorbed steady demand from commuters, defense workers, and remote workers who discovered it during the pandemic.
The city's housing market runs on a mix of drivers that first-timers don't always anticipate. Puget Sound Naval Shipyard in nearby Bremerton creates a large pool of buyers who know their timelines, move decisively, and sometimes have VA loan benefits — which means you're competing against experienced buyers even when the listing count looks comfortable. The Zillow Home Value Index for Port Orchard sits at $565,709 as of July 2026, up roughly 1.9% over the prior year, and that figure masks real variation across the city's distinct areas. Understanding where you land in the price range before you ever tour a home is the most important thing this guide can help you do. For a full breakdown of what daily expenses look like on top of a mortgage payment, see the cost of living in Port Orchard page.
Port Orchard's quality-of-life draws are real and worth naming. The waterfront farmers market runs every Saturday from 9 a.m. to 2 p.m., April through October. Whiskey Gulch on Bay Street and Peninsula BevCo on Harrison Avenue give the downtown a genuine local texture — the kind of walkable evening that makes a neighborhood feel like a community rather than a subdivision. Uncle Dave's Cafe on SE Lund Avenue is the kind of unpretentious diner that regulars treat as a weekly ritual. These aren't amenities bolted onto a commuter town; they're signs that Port Orchard has enough of its own identity to hold people who aren't just here for the ferry.
Whether you're deciding between renting another year or making an offer, the sections below walk through what your budget actually buys in Port Orchard right now, the step-by-step process for buying here, an honest affordability snapshot, and the specific mistakes that cost first-timers the most in this market.
The Port Orchard First-Time Buyer Reality
The city-wide Zillow Home Value Index of $565,709 (July 2026) is useful as a baseline, but it can mislead a first-timer into thinking they have more runway than they do. That median is pulled upward by waterfront and golf-community properties that sit well beyond what most first-timers are financing. Your local agent's knowledge of specific pockets within the city matters enormously for finding inventory that actually fits your budget.
The market is described as "somewhat competitive" — not the frenzied bidding wars of 2021–2022, but not forgiving either. Homes are selling in approximately 22 days on average (three months ending June 2026), and the well-priced ones go faster: the sharpest listings go pending in as few as 4 days and close at roughly 3% above asking. Two offers on a home is the average, which sounds manageable until you're the losing offer on three consecutive houses and start making compromises you didn't intend to make.
One pricing dynamic worth internalizing early: the 2026 FHA loan limit for Kitsap County is $541,287 for a single-family home. If your target price exceeds that ceiling — which it may, given the market median — you'll need to evaluate conventional loan options. That's not a barrier, but it does change your down payment math. Plan your budget around these realities before you fall in love with a specific address.
The Homebuying Process in Port Orchard, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
This is the step first-timers most often skip or defer, and it costs them. In Port Orchard's market, a listing that seemed like it would sit for two weeks can go pending over a weekend. Sellers here — many of whom are defense-community homeowners who understand logistics — take pre-approval letters seriously and will not wait for you to catch up. Get a full underwritten pre-approval, not just a pre-qualification estimate, before you schedule your first showing.
Step 2: Define Your Search Radius Honestly
Port Orchard's geography shapes the decision in ways that a simple map doesn't communicate. If you're commuting to Puget Sound Naval Shipyard or the broader Bremerton area, your drive from Mile Hill or Tremont is roughly 20 minutes — manageable. If you're commuting to Seattle, you're combining a drive to the Bremerton ferry terminal with a 60-minute passenger crossing, which is a lifestyle choice, not just a commute. Be honest about which neighborhoods give you a sustainable daily rhythm before you commit to a ZIP code.
Step 3: Write Offers With Your Agent's Local Intelligence
Port Orchard offers often need to move within 24–48 hours of a listing going live. The second step first-timers most often get wrong locally is writing a weak or slow offer on a well-priced home because they're waiting for a second showing or more negotiating leverage. In this market, leverage comes from preparation — clean financing, a reasonable earnest money deposit (typically 1–3% of purchase price in Kitsap County), and an escalation clause on competitive listings.
Step 4: Inspection and Appraisal
Washington State strongly favors keeping your inspection contingency intact as a first-time buyer. Homes in Port Orchard's older stock — particularly around Bay Street and Manchester — can carry deferred maintenance surprises: aging roofs, older electrical panels, or moisture issues common in the marine climate. An inspection waiver on a home you've only seen once is a significant financial risk for buyers without deep cash reserves. The appraisal typically follows within a week of mutual acceptance and is ordered by your lender.
Step 5: Closing
Washington is an escrow state; a title and escrow company handles the closing process, and you'll typically sign final documents 1–3 days before the actual funding date. Closing costs in Washington generally run 2–3% of the purchase price, covering lender fees, title insurance, escrow fees, and prepaid items like homeowners insurance and the initial property tax deposit. Budget for this cash separately from your down payment — it is not optional and is not covered by your loan.
How Much Home Can You Afford in Port Orchard
The table below shows estimated cash-needed scenarios at common Port Orchard price points. Closing costs are estimated at 2.5% of purchase price — a reasonable mid-range for Kitsap County transactions. These are approximations to help you plan; your lender's Loan Estimate will give you exact figures. The interactive calculator below this section will help you model monthly payments.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2.5%) | Cash Needed at Table |
|---|---|---|---|---|
| FHA 3.5% — entry condo/townhome | $380,000 | $13,300 (3.5%) | ~$9,500 | ~$22,800 |
| FHA 3.5% — below-median SFR | $460,000 | $16,100 (3.5%) | ~$11,500 | ~$27,600 |
| FHA 3.5% — near FHA limit | $530,000 | $18,550 (3.5%) | ~$13,250 | ~$31,800 |
| Conventional 3% — below-median SFR | $460,000 | $13,800 (3%) | ~$11,500 | ~$25,300 |
| Conventional 5% — near city median | $565,000 | $28,250 (5%) | ~$14,125 | ~$42,375 |
| Conventional 10% — above-median SFR | $650,000 | $65,000 (10%) | ~$16,250 | ~$81,250 |
Note that FHA financing at Kitsap County's 2026 loan limit of $541,287 means a purchase price above roughly $561,000 at 3.5% down would exceed the FHA ceiling — buyers at or above the city median will generally need a conventional loan program. Keep in mind that Washington's effective property tax rate in Port Orchard runs approximately 0.80% annually, a figure worth building into your total monthly budget alongside principal, interest, and homeowners insurance — what lenders call PITI.
Looking to buy in Port Orchard? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Port Orchard quote.
Common First-Time Buyer Mistakes in Port Orchard
Waiving the Inspection on an Older Home
Port Orchard's inventory includes a meaningful share of homes built in the 1970s–1990s, particularly in areas like Manchester and along the older Bay Street corridor. The marine climate accelerates certain maintenance issues — roof wear, crawl space moisture, and wood rot — that don't always show up in photos. Waiving your inspection contingency to compete with a cash buyer is a reasonable strategy for new construction; on a 40-year-old split-level, it's a risk that can turn into a $20,000–$40,000 repair bill in the first two years of ownership.
Shopping Before Pre-Approval
Hot listings in Port Orchard go pending in as few as 4 days. Buyers who tour homes before completing their pre-approval lose time at exactly the wrong moment — the moment a well-priced home hits Zillow. Pre-approval also forces a realistic reckoning with your actual budget, which is harder to do once you've emotionally attached to a specific home. Do the financial work first; let it define your search, not the other way around.
Underestimating Cash-to-Close
First-timers consistently underestimate how much cash needs to be liquid at closing. Your down payment is the headline number, but closing costs, the earnest money deposit, prepaid homeowners insurance, and the initial property tax escrow deposit add thousands on top of it. At a $500,000 purchase price, plan for $35,000–$45,000 in total cash depending on your loan type and negotiated credits — not just the down payment line item your lender quoted at pre-qualification.
Ignoring the FHA Loan Limit Before Falling in Love With a Price Point
Port Orchard's market median sits close enough to the 2026 FHA loan limit of $541,287 that many first-timers start their search assuming FHA financing works at any price point they find online. It doesn't. A home listed at $570,000 — not an unusual number in this market — puts you above the FHA ceiling for Kitsap County, which means you need a conventional loan and, at a 3% down payment, roughly $17,000 in down payment alone plus closing costs. Finding this out mid-offer on a home you've already toured twice is one of the most avoidable mistakes in the process. Run your loan type through your lender's calculator before you set your search maximum, not after.
Local Expert Takeaway: Port Orchard's market rewards buyers who do their homework early and move confidently when the right home appears. Get your full pre-approval in hand — not just an estimate — before you tour anything. Know whether your price target works with FHA financing or requires conventional; that single answer reshapes your down payment math significantly. Budget your total cash-to-close honestly, including closing costs and prepaid escrow items on top of your down payment. And keep your inspection contingency intact, especially on older homes near Bay Street and Manchester where the marine climate has had decades to find weak points. The buyers who succeed here aren't the ones who move the fastest — they're the ones who were already prepared when the right listing dropped.
Quick Takeaways & FAQs
✅ Port Orchard's Zillow Home Value Index of $565,709 (July 2026) sits noticeably below comparable Puget Sound markets, giving first-timers meaningful purchasing power relative to Gig Harbor or the Seattle Eastside.
⚠️ The 2026 FHA loan limit for Kitsap County is $541,287 — buyers targeting homes at or above the city median will need to qualify for a conventional loan program, which changes down payment planning significantly.
📍 The Port Orchard waterfront farmers market runs every Saturday from 9 a.m. to 2 p.m., April through October — the kind of recurring community anchor that makes first-time buyers feel like they've landed somewhere with actual neighborhood life.
What credit score do I need to buy a home in Port Orchard with an FHA loan?
How competitive is Port Orchard's housing market for first-time buyers?
Does the FHA loan limit affect buyers in Port Orchard?
How much cash do I actually need to close on a home in Port Orchard?
Is it better to buy in Port Orchard now or wait for prices to drop?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
