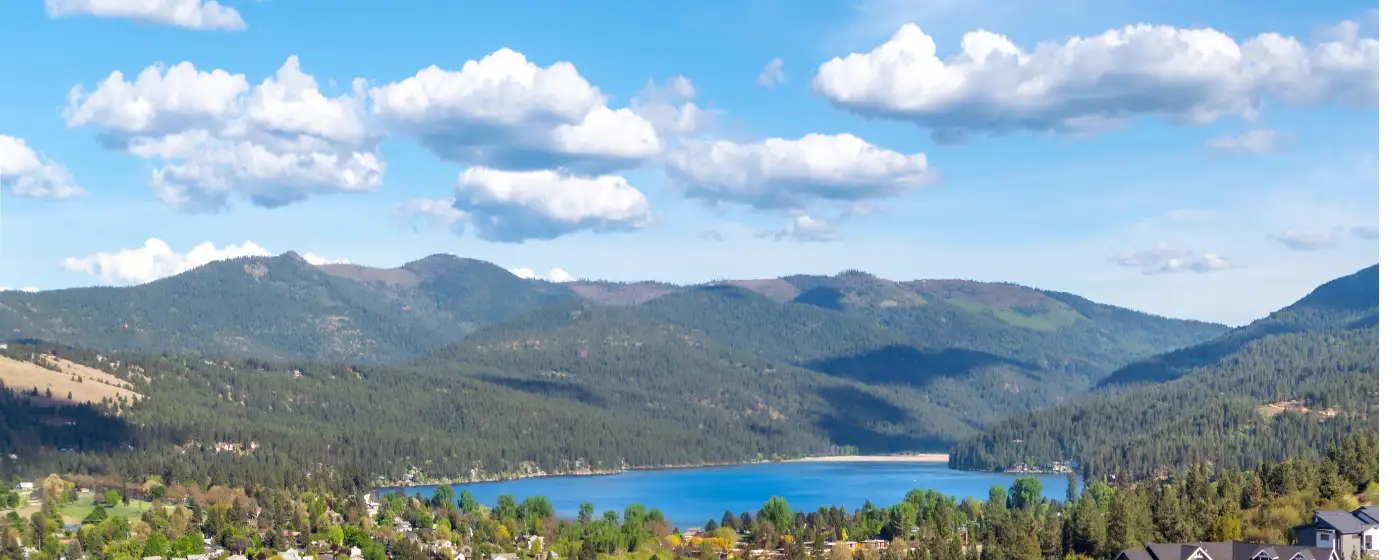
You've heard Liberty Lake is a step up from Spokane Valley without the Coeur d'Alene price tag — and that's mostly true. But what first-timers consistently underestimate is how fast this market moves. Homes here are going to pending in roughly 17 to 20 days on average, and the ones in move-in condition in well-regarded subdivisions like Villages at Stonehill or MeadowWood can disappear in five days or less. Liberty Lake sits along I-90 at the Washington-Idaho border, about 20 minutes east of downtown Spokane — close enough to commute, far enough to feel like its own place, anchored by the lake itself and a walkable town center that most Spokane suburbs simply don't have.
The city's economic base is unusually stable for a community of roughly 13,000 people. Itron, a smart metering technology company, is headquartered here. STCU and Numerica Credit Union both have significant operations in Liberty Lake. Amphenol Network Solutions adds a manufacturing component. That mix of tech, finance, and manufacturing creates a buyer pool with real purchasing power — which is part of why this market holds its value even as surrounding areas soften. Competition from other well-qualified buyers is a fact of life here, not an occasional annoyance. The full cost-of-living picture explains how local incomes translate to day-to-day expenses beyond housing.
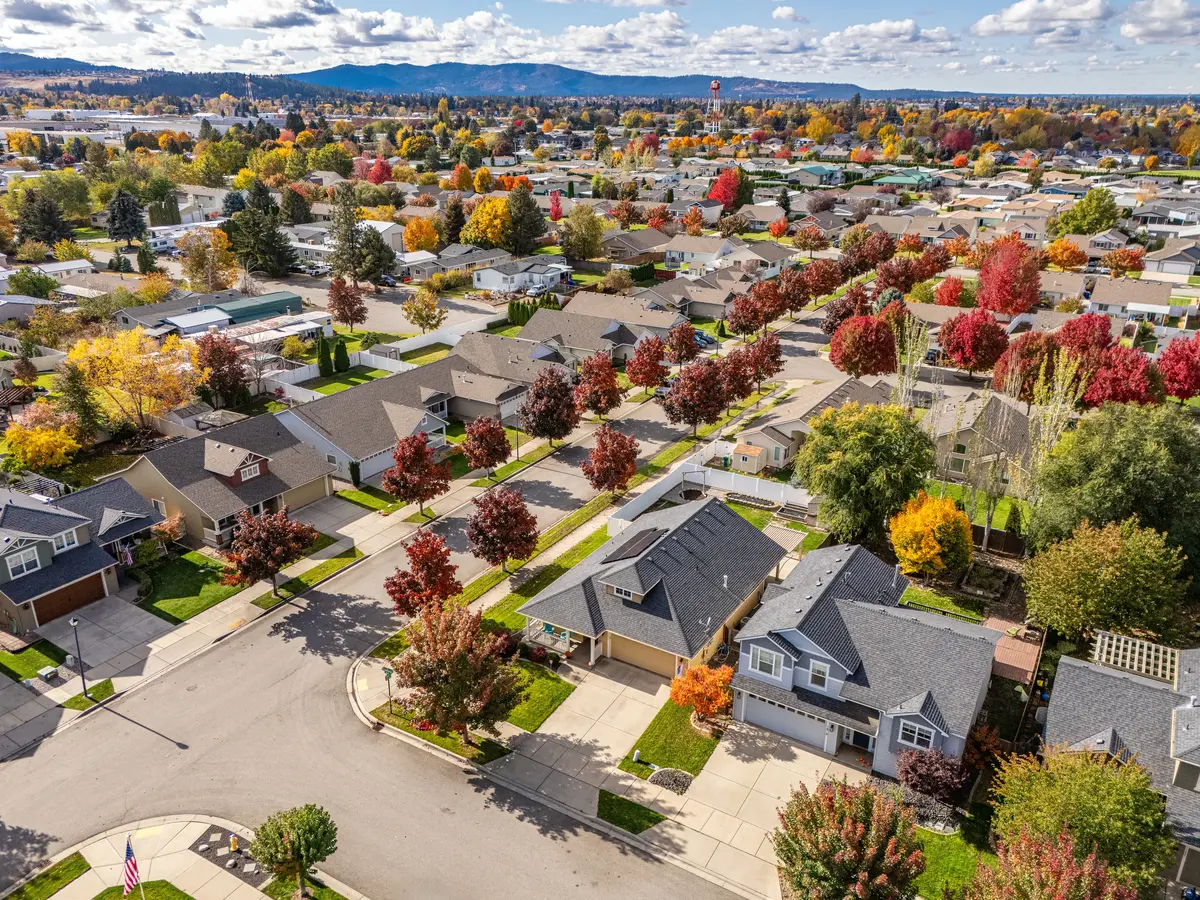
Liberty Lake's housing stock skews modern. The city was largely built out from the early 2000s onward, which means fewer of the deferred-maintenance surprises common in older Spokane neighborhoods. New construction is still active — Lennar had listings in Stonehill as recently as mid-2026 — so first-timers have options across the spectrum from resale townhomes to brand-new detached homes. The tradeoff is that entry-level inventory is thin, and the gap between what you can qualify for and what's actually available on a given Tuesday can be frustrating.
Whether you're comparing Liberty Lake to Post Falls across the Idaho line or trying to decide if you can afford to stay in the area rather than moving further out, the sections below walk through what a first-timer's budget actually buys here, the step-by-step buying process in this specific market, a budget snapshot table, and the four mistakes that most often derail first-time buyers locally.
The Liberty Lake First-Time Buyer Reality
The Zillow Home Value Index for Liberty Lake stands at $580,200 as of mid-2026 — down a modest 2.5% from the prior year, but still a number that demands honest budget math before you fall in love with a listing. That figure is a city-wide average across attached and detached homes; entry points for a two-bedroom townhome or a smaller detached home can come in noticeably below it, while larger or lake-adjacent homes push well above.
What that average doesn't tell you is the competitive pressure underneath it. In December 2025, supply sat at just 2.9 months and homes sold at 99.08% of asking price. Redfin rates the market as "very competitive" — hot homes go pending in roughly five days. For a first-timer who needs time to think, that pace is genuinely disorienting the first time you experience it.
The practical takeaway: don't plan on bidding significantly under list and winning. Offers that are clean, fully pre-approved, and close to asking — sometimes at asking — are what moves in this market. That's a different mental model than buyers arrive with after seeing prices dip slightly year-over-year. The slight softening hasn't handed power to buyers; it has just slowed the pace from frantic to competitive.
The Homebuying Process in Liberty Lake, Step by Step
Step 1: Get Pre-Approved — Before You Tour a Single Home
Pre-approval is not the same as pre-qualification. Pre-qualification uses numbers you self-report; pre-approval means a lender has reviewed your credit score, income documentation, and outstanding debts and issued a letter specifying the maximum purchase price and loan type. In a market where desirable homes go pending in five days, showing up with only a pre-qualification letter is effectively showing up without one.
Your pre-approval letter will specify whether you're using a conventional loan, an FHA loan, a VA loan, or another program — and that matters to sellers in Liberty Lake, where multiple-offer situations are common. Get the letter before you schedule your first showing.
Step 2: Find a Local Agent Who Knows This Market
An agent who primarily works Spokane Valley or the South Hill will know the region but may not know the specific subdivision dynamics in Liberty Lake — which phases of Stonehill have HOA restrictions that affect financing, which parts of Rocky Hill have steeper terrain affecting future resale, or where the school attendance boundaries shift. Liberty Lake is small enough that hyper-local knowledge matters.
Step 3: Shopping — Be Honest About Your Must-Haves
Liberty Lake's housing stock is modern and relatively uniform compared to older Spokane neighborhoods. You're unlikely to find a 1960s craftsman bungalow here; you will find attached townhomes, planned-community detached homes, and new construction. If you're hoping for a large lot or mature trees, you need to be selective — many subdivisions prioritize density and community amenities over yard size.
Step 4: Making an Offer
With only 2.9 months of supply and homes selling at 99% of asking, this is not the market to open dramatically low. First-timers often make the mistake of anchoring to the list price as a ceiling they can negotiate down from. In Liberty Lake, that ceiling is closer to the floor on anything priced fairly.
Escalation clauses, flexible closing timelines, and minimizing unnecessary conditions are tools your agent should discuss with you. The one contingency you should not waive as a first-timer is the financing contingency — more on that in the mistakes section.
Step 5: Inspection and Appraisal
Because Liberty Lake's stock is mostly post-2000 construction, major structural surprises are less common than in older markets. That doesn't mean you skip the inspection. HOA documents (mandatory reading for any attached or planned-community home), sewer scope results, and roof age are the three things that most often produce negotiating moments after inspection in this market.
Washington State also requires a homebuyer education seminar — a free five-hour course available online — for buyers using state housing finance programs. Even if your loan doesn't require it, the course covers budgeting and homeownership responsibilities in a way most first-timers find genuinely useful.
Step 6: Closing
Washington uses escrow-based closings. Plan for roughly 30 to 45 days from accepted offer to keys. Budget your closing costs carefully — they are a separate cash requirement from your down payment, and underestimating them is one of the most common first-timer stumbles locally. The budget section below shows the actual numbers.
How Much Home Can You Afford in Liberty Lake
The table below shows estimated cash-at-closing requirements for different purchase price scenarios in Liberty Lake. Closing costs are estimated at 2–3% of the purchase price, which is typical for Washington State and covers title insurance, escrow fees, lender fees, and prepaid items. These are approximations — your actual figures depend on your lender, your loan terms, and negotiated seller credits.
Note that the 2026 FHA loan limit for Spokane County (which includes Liberty Lake) is $541,287 for a single-family home. Purchases above that figure are not eligible for FHA financing, which is why the higher scenarios in the table default to conventional terms.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–3%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA minimum (3.5% down) | $420,000 | $14,700 (3.5%) | $8,400–$12,600 | ~$23,100–$27,300 |
| FHA — near county limit | $520,000 | $18,200 (3.5%) | $10,400–$15,600 | ~$28,600–$33,800 |
| Conventional (3% down) — entry | $450,000 | $13,500 (3%) | $9,000–$13,500 | ~$22,500–$27,000 |
| Conventional (5% down) — city average | $580,200 | $29,010 (5%) | $11,604–$17,406 | ~$40,614–$46,416 |
| Conventional (10% down) — city average | $580,200 | $58,020 (10%) | $11,604–$17,406 | ~$69,624–$75,426 |
| Conventional (20% down) — above average | $680,000 | $136,000 (20%) | $13,600–$20,400 | ~$149,600–$156,400 |
A few things worth flagging: FHA loans carry a 1.75% upfront mortgage insurance premium (typically rolled into the loan balance) plus 0.55% annual mortgage insurance paid monthly. For buyers putting less than 10% down on an FHA loan, that mortgage insurance lasts the life of the loan — a real long-term cost that factors into your true monthly obligation, which the mortgage calculator below will model for you.
Washington has no state income tax, which affects how much of your gross income you keep relative to buyers relocating from states with income taxes — relevant context for the cost-of-living comparison. Liberty Lake's effective property tax rate is approximately 0.83%, which is notably lower than most of the Pacific Northwest coast.
One more practical note: most Liberty Lake purchases fall well within conventional financing territory. The city's typical home price of $580,200 sits comfortably below the 2026 baseline conventional loan limit for Spokane County, so the majority of buyers here have full access to conventional loan products without reaching for alternative financing structures.
Looking to buy in Liberty Lake? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Liberty Lake quote.
Common First-Time Buyer Mistakes in Liberty Lake
Mistake 1: Touring Homes Before You Have Pre-Approval
This is the single fastest way to lose a home in Liberty Lake. You find the right place in Stonehill on a Thursday, your agent submits an offer Friday morning — and the listing agent calls to say two other offers came in, both with pre-approval letters, both asking for a response by Friday afternoon. A pre-qualification letter in that situation is not competitive. The pre-approval process takes two to five business days with most lenders; start it before you want to be ready, not after.
Mistake 2: Waiving the Financing Contingency to Compete
In hot markets, buyers sometimes waive the financing contingency to make their offer look cleaner. For a first-timer who has not been through the appraisal and underwriting process before, this is a significant risk. If the home appraises below your purchase price and you've waived the financing contingency, you're on the hook to cover the gap in cash or walk away and potentially lose your earnest money. In Liberty Lake, where prices are real and appraisals can lag on rapidly moving inventory, keep the financing contingency unless your lender has given you very specific guidance otherwise.
Mistake 3: Underbudgeting the Cash You'll Need at Closing
First-timers consistently focus on the down payment number and mentally stop there. Closing costs in Washington State — escrow fees, title insurance, lender origination fees, prepaid property taxes, and homeowners insurance at funding — typically add another 2 to 3% of the purchase price on top of your down payment. On a $580,000 purchase, that's an additional $11,600 to $17,400 in cash you need available at closing, separate from any reserves your lender requires you to hold. Budget for the full number, not just the down payment line.
Mistake 4: Ignoring HOA Terms in Planned Communities
Liberty Lake's modern housing stock means a significant share of available inventory sits inside homeowners associations — particularly in Villages at Stonehill, The Villas at Big Trout, and MeadowWood. HOA fees, restrictions on rentals, and rules about modifications directly affect both your monthly budget and the home's future financing eligibility. Some HOA structures can make conventional financing more complicated if the association's reserve fund is underfunded or if too high a percentage of units are investor-owned. Read the HOA documents during your inspection period, not after closing.
Local Expert Takeaway: Liberty Lake is an approachable first purchase compared to Coeur d'Alene or the Seattle suburbs, but it is not a slow market where you can make relaxed decisions. With homes averaging around $580,200 and going pending in under three weeks, the buyers who succeed here show up pre-approved, have their closing cash fully assembled (not just the down payment), and understand that clean offers near asking are the norm — not the exception. Knowing the subdivision dynamics — which HOAs have rental restrictions, which phases of Stonehill are still under active construction — is what separates buyers who close from buyers who keep losing offers.
Quick Takeaways & FAQs
✅ Liberty Lake's housing stock is predominantly modern construction from the 2000s onward, meaning fewer deferred-maintenance surprises than older Spokane neighborhoods — a genuine first-timer advantage.
⚠️ Homes here go to pending in 17–20 days on average, and the most desirable listings in communities like Stonehill can disappear in five days — touring without pre-approval in hand is a reliable way to lose a home you wanted.
📍 The 2026 FHA loan limit for Spokane County is $541,287 — homes priced above that threshold (which includes many Liberty Lake listings near the city average of $580,200) require conventional financing, so know your loan type before you start shopping.
What credit score do I need to buy a home in Liberty Lake, WA?
Is Liberty Lake a buyer's market or seller's market right now?
Can I use an FHA loan to buy in Liberty Lake?
How long does it take to close on a home in Liberty Lake?
What are closing costs in Liberty Lake, and how much cash do I actually need?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
