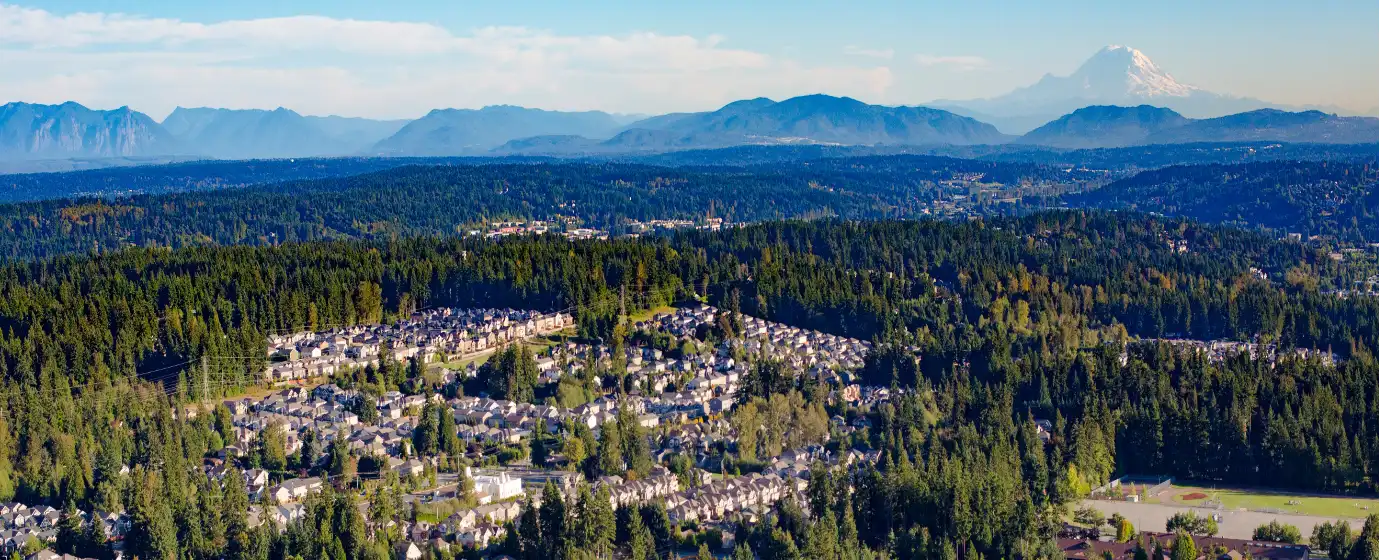
Maybe your company moved you to the Eastside and you're done throwing rent money at an apartment in Kirkland. Maybe you've been watching Seattle prices for two years, did the math, and someone in your office mentioned Bothell. Either way, you've landed in one of the more interesting first-time buyer markets on the Eastside: genuinely competitive, but meaningfully more accessible than the cities directly to the south and west — and, as of 2026, with more breathing room than buyers have had since before the pandemic.
The Zillow Home Value Index for Bothell stood at $951,587 as of June 2026 — a number that stops most first-timers cold. But context matters: comparable single-family homes in neighboring Kirkland routinely exceed that figure by a wide margin, which means Bothell is often the first realistic foothold on the Eastside for buyers priced out of those markets. A dense cluster of life sciences and tech employers keeps year-round buyer demand unusually stable, and the city's position along the SR-522 and I-405 corridors makes it a practical base for commuters across the region. For more on what drives Bothell's economy and community, see the Living in Bothell overview.
The good news for 2026: inventory nearly doubled year-over-year, homes are now taking 26 to 33 days to sell rather than the 6 to 10 days buyers faced in 2024, and there is genuine room to negotiate. The market is still a seller's market — supply sits around 1.5 to 2.5 months, well below the 5-month neutral threshold — but it no longer demands the waived-everything, offer-sight-unseen desperation of recent years. Townhomes and condos, which have lagged single-family appreciation for years, offer relative value for buyers who want to get into the market at a lower entry point. For the full cost-of-living picture, see the Bothell cost-of-living page.
This guide walks through what a first-timer's budget actually buys here, the step-by-step purchase process with the specific missteps locals make most often, a concrete budget snapshot table, and the four mistakes that cost Bothell buyers real money.
The Bothell First-Time Buyer Reality
At a Zillow Home Value Index of $951,587 (June 2026), the median Bothell home is not a starter home in any traditional sense. First-timers need to walk in with clear eyes: below $700,000, you're looking almost exclusively at condos and townhomes — and that's not a consolation prize. Condo values have lagged single-family appreciation for years, which means relative value exists in that segment right now.
The county line running through Bothell is the detail most first-timers don't know and should. Bothell straddles King and Snohomish counties, and the property tax structure differs between them. That split also means that two separate districts serve different portions of the city — if schools factor into your decision, verify the specific address before you make an offer, not after. A house that looks identical to its neighbor may sit in a completely different district.
The market shift of 2026 is real and worth using. Homes sitting 26 to 33 days gives you time to schedule a proper inspection, compare financing options, and make a considered offer rather than a panicked one. That said, well-priced listings near major employment corridors still draw multiple offers. The window is wider than it was — it's not open.
The Homebuying Process in Bothell, Step by Step
Step 1: Get Pre-Approved — Before You Tour Anything
In the Seattle metro, submitting an offer without a pre-approval letter is effectively disqualifying. Pre-approval is not the same as pre-qualification: pre-qualification relies on numbers you self-report, while pre-approval involves a lender reviewing your actual income documents, credit report, and asset statements. The result is a conditional commitment letter specifying the loan amount you qualify for — that letter is what Bothell sellers want to see before they take your offer seriously.
The process typically takes 5 to 7 business days in Washington State. Start before you fall in love with a house. And once you have that letter, treat your financial profile as frozen: no new credit cards, no car loan, no large cash transfers, no job changes. Any of those can alter your debt-to-income ratio or credit score enough to unwind the lender's approval before closing.
Step 2: Define Your Search
Work with your agent to set realistic parameters — price ceiling, minimum square footage, county preference, and commute tolerance. Bothell's geography matters here: homes near SR-522 and I-405 offer faster access to Seattle and Kirkland but carry more road noise. Neighborhoods further north tend to be quieter and somewhat less expensive, but the drive to the city adds minutes that compound over a week.
Step 3: Make a Competitive Offer
In 2026, the all-cash, no-contingency offer is less common than it was in 2022 and 2023 — but it hasn't disappeared. For most first-timers using financing, the offer structure that works is a clean pre-approval letter, an earnest money deposit that signals seriousness (typically 1–3% of purchase price in this market), and realistic timelines. Escalation clauses are worth discussing with your agent on any listing that's been active fewer than two weeks.
Step 4: Inspection and Appraisal
Do not waive your inspection on a first home. This is the step first-timers under competitive pressure most often get wrong: the fear of losing a house leads buyers to skip the one process designed to surface $30,000 problems before they become your $30,000 problems. A general inspection plus a sewer scope (standard practice in the Seattle suburbs for older homes) is non-negotiable.
Your lender will order an appraisal separately. If the appraised value comes in below the purchase price, you'll need to cover the gap in cash, negotiate a price reduction, or walk. Know your appraisal contingency options before you're in that conversation.
Step 5: Closing
Washington State closings typically happen through an escrow company, not an attorney. You'll sign a stack of documents, wire your closing funds (verified wire instructions only — wire fraud targeting homebuyers is real), and receive keys once the deed records. From accepted offer to keys typically runs 30 to 45 days with financing.
How Much Home Can You Afford in Bothell
The table below lays out what different purchase prices and loan structures actually require at the closing table. These are estimates — your lender will produce exact figures based on your credit profile, the specific property, and current rates. Use this as a planning tool, not a commitment.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5% down) — condo/townhome entry | ~$650,000 | ~$22,750 (3.5%) | ~$13,000–$16,000 (2–2.5%) | ~$36,000–$39,000 |
| Conventional (3% down) — condo/townhome | ~$700,000 | ~$21,000 (3%) | ~$14,000–$17,500 (2–2.5%) | ~$35,000–$38,500 |
| Conventional (5% down) — entry SFR | ~$800,000 | ~$40,000 (5%) | ~$16,000–$20,000 (2–2.5%) | ~$56,000–$60,000 |
| Conventional (10% down) — mid-range SFR | ~$900,000 | ~$90,000 (10%) | ~$18,000–$22,500 (2–2.5%) | ~$108,000–$112,500 |
| Conventional (20% down) — near-median SFR | ~$950,000 | ~$190,000 (20%) | ~$19,000–$23,750 (2–2.5%) | ~$209,000–$213,750 |
| Conventional (20% down) — above-median SFR | ~$1,100,000 | ~$220,000 (20%) | ~$22,000–$27,500 (2–2.5%) | ~$242,000–$247,500 |
Closing costs in Washington State typically run 2 to 2.5% of the purchase price for buyers, covering lender fees, title and escrow, prepaid homeowners insurance, and prepaid property taxes. The 20% down scenarios eliminate private mortgage insurance (PMI), which meaningfully reduces monthly carrying costs — your lender can run the PMI breakeven for you based on current rates.
First-timers often underestimate the cash reserve lenders want to see after closing. Most lenders prefer you to have 2 to 3 months of housing payments remaining in savings post-close, separate from your down payment and closing funds. Budget for that before you set your ceiling.
* All figures are planning estimates only. Actual amounts depend on loan type, interest rate, credit profile, and property-specific factors.
Looking to buy in Bothell? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Bothell quote.
Common First-Time Buyer Mistakes in Bothell
Mistake 1: Touring Before You Have a Pre-Approval Letter
It feels harmless to walk through a few open houses before you've talked to a lender. In Bothell's market, it's a setup for heartbreak. You find the right house on a Saturday. By Tuesday, when your pre-approval finally comes through, it's under contract. Pre-approval takes 5 to 7 business days — start that process the moment you get serious, not the moment you find a listing you like.
Mistake 2: Waiving Inspection to Win a Bidding War
Some buyers waive the inspection contingency entirely to make their offer more competitive. On a newer Downtown Bothell townhome with full seller disclosures and recent records, you might be able to have a nuanced conversation with your agent about inspection timing. On a 1980s single-family home where you can't see the sewer line, skipping the inspection is how first-time buyers become owners of a $40,000 lateral replacement problem within the first year. Waiving an inspection contingency is a negotiating lever; treat it like one, not like a checkbox.
Mistake 3: Not Verifying Which District Serves a Specific Address
Bothell's split across King and Snohomish counties means two different districts serve different addresses within the same city. Buyers sometimes assume every Bothell address feeds into the same one. It doesn't. Verify the boundary for any specific address using the district's official lookup tool before you make an offer — a house that looks identical to its neighbor may be assigned completely differently.
Mistake 4: Forgetting What Happens After Pre-Approval
Once your lender issues a pre-approval letter, first-timers sometimes treat it as a finish line. It isn't — it's a snapshot of your financial profile on that date. Opening a new credit card for the furniture you're already planning to buy, financing a car to handle the new commute, or switching jobs mid-transaction can each unravel your loan before closing. Your lender will pull your credit again before funding. Keep your financial picture exactly as it was the day you got that letter.
Local Expert Takeaway: Bothell's 2026 market is the most navigable it's been for first-timers in years — more inventory, longer days on market, and real room to conduct due diligence. But 'more room' is not the same as 'easy.' The buyers who succeed here get pre-approved before they tour, budget honestly for cash-at-table (down payment plus 2–2.5% closing costs plus a post-close reserve), verify the specific district boundary before they fall in love with an address, and don't waive inspection on older construction. Townhomes and condos near Downtown Bothell along the Beardslee Boulevard corridor offer the most realistic entry points for buyers who want in at a lower price than the single-family median — and that corridor is a genuinely livable place to land while you build equity.
Quick Takeaways & FAQs
✅ Inventory in Bothell nearly doubled year-over-year in early 2026, giving first-time buyers more time to evaluate homes and negotiate than at any point since before the pandemic.
⚠️ The Zillow Home Value Index for Bothell sits at $951,587 (June 2026), meaning most first-timers need at least $36,000–$60,000 in liquid cash just to reach the closing table — often more.
📍 Bothell straddles King and Snohomish counties, and not every city address is served by the same district — always verify a specific address's assignment before making an offer.
What is the minimum down payment to buy a home in Bothell, WA?
How long does it take to buy a house in Bothell from start to finish?
Is Bothell still a seller's market in 2026?
Does Bothell fall in King County or Snohomish County — and does it matter for buyers?
What credit score do I need to buy a home in Bothell?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
