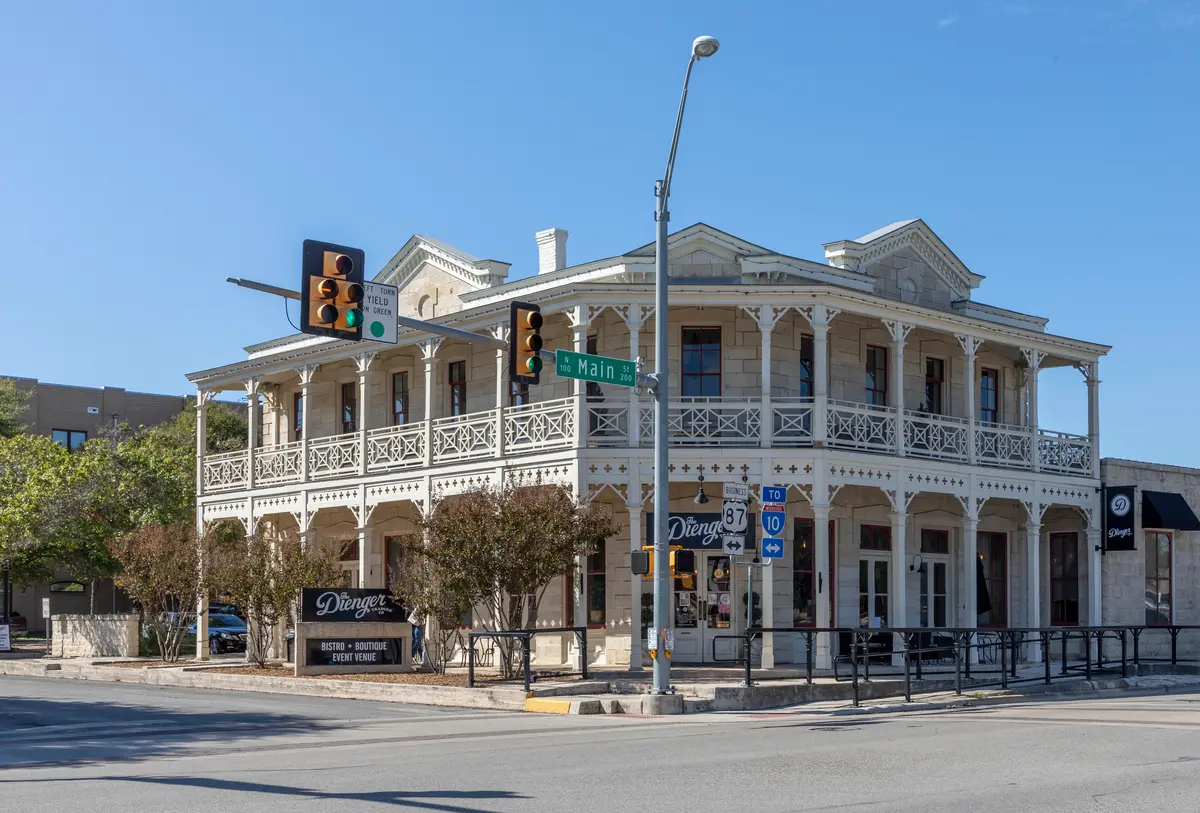
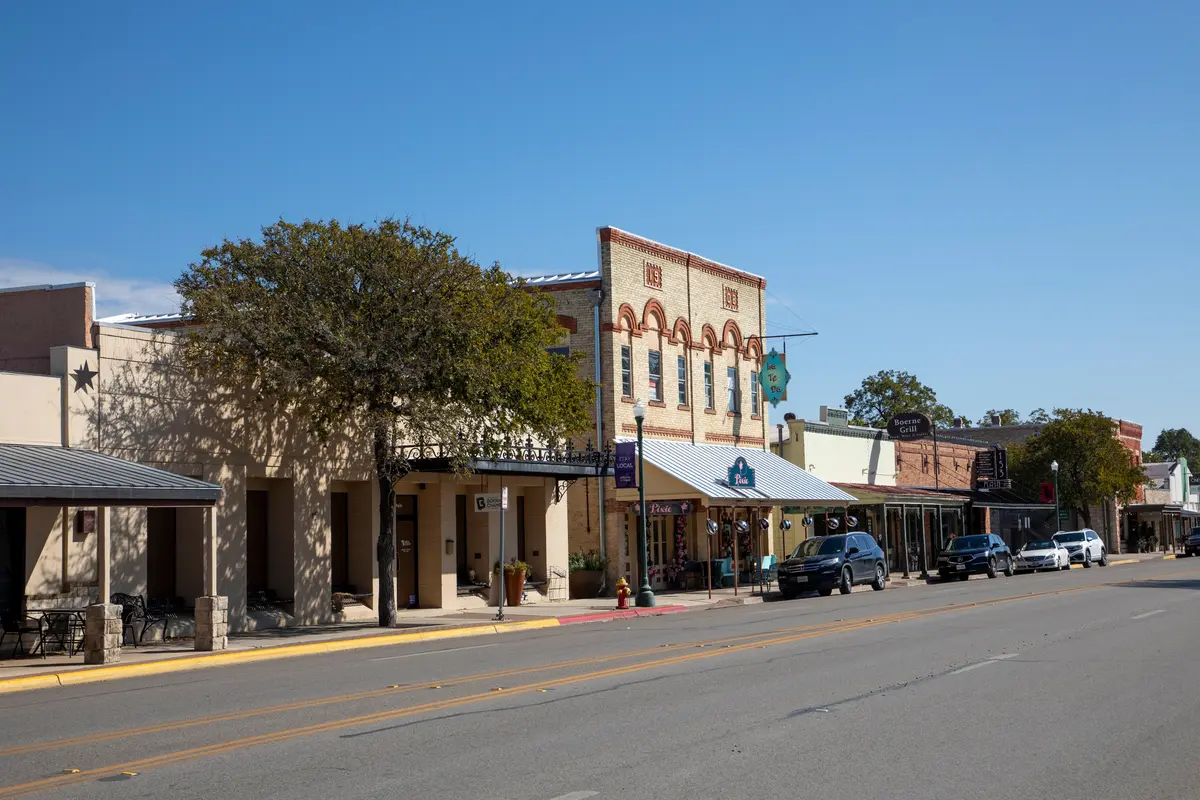
Maybe you've been renting in San Antonio and the math finally tilted toward buying. Maybe you drove through Boerne on a weekend — past the limestone storefronts on Main Street, past Cibolo Creek, past the Hill Country horizon — and started wondering what it would cost to actually live here. The honest answer: more than most first-timers expect, and less than they fear if they enter the process prepared. Boerne sits about 30 minutes from San Antonio along I-10, which makes it genuinely commutable while still feeling like a different world. That combination of access and Hill Country character is exactly why Kendall County has been among the fastest-growing counties in the nation for several consecutive Census cycles.
The economic backbone here is real and diversified. Boerne Independent School District — which holds an A rating, according to the Texas Education Agency — is the city's largest employer and a major draw for families with school-age children. Mission Pharmacal Company and Albany Engineered Composites anchor the private-sector side, and a significant share of residents commute to San Antonio for work at employers like USAA. That commuter profile shapes the buyer pool: you are competing with dual-income households who have already stress-tested the I-10 drive and decided the trade-off is worth it. Sustained inbound migration has kept demand real and consistent, which matters when you are trying to understand what you are stepping into as a buyer.
Cost of living here is above the Texas median, and the cost-of-living breakdown goes deeper on that reality. The typical home price as of July 2026, per the Zillow Home Value Index, is $562,046 — a figure that sits noticeably above what the city's median household income can comfortably carry on its own. Entry-level inventory exists below that figure, but it competes. The Hill Country topography that makes Boerne beautiful also limits how much new land can be subdivided, which keeps supply constrained in ways that flat-terrain Texas markets do not face. Day-to-day life centers on the Main Street Historic District, Boerne City Park, and the Cibolo Nature Center — the kind of outdoor, walkable amenities that make the mortgage feel worth it on a Saturday morning.
Whether you are just starting to save or are ready to schedule showings, the sections below walk through what the Boerne market actually looks like for a first-time buyer, the step-by-step purchase process, a realistic budget table, and the specific mistakes that cost local first-timers the most.
The Boerne First-Time Buyer Reality
The typical home price in Boerne is $562,046 as of July 2026 (Zillow Home Value Index). That number is the market's center of gravity, not its floor. Entry-level homes — smaller square footage, older construction, or lots farther from the historic core — do appear in the $380,000–$450,000 range, but they attract real competition from buyers who have already been pre-approved and are ready to move.
What this means practically: a first-timer who arrives without financing in place will lose. The market has shifted from the frenzied pace of 2021 toward something more balanced, with resale homes recently selling at roughly 95% of original list price and new construction offering more room to negotiate — sometimes landing near 89% of list. That breathing room is real, but it does not make Boerne a buyer's market in the traditional sense. Well-priced resale homes in Boerne Independent School District boundaries still draw multiple showings quickly.
New construction in communities like Esperanza or Balcones Creek can be a legitimate path for first-timers because builders sometimes offer closing-cost incentives that sellers on the resale market won't match. The catch: new builds often carry a premium over the city-wide typical figure, and builder contracts are written to protect the builder. Going into a builder's sales office without independent representation is one of the most expensive mistakes a Boerne first-timer can make. For a fuller picture of which neighborhoods fit different buyer profiles, the neighborhoods guide breaks down the character and feel of each community.
The Homebuying Process in Boerne, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
In Boerne, touring before pre-approval is not just inefficient — it is a way to fall in love with a home you cannot bid on competitively. Local listing agents routinely ask whether buyers are pre-approved before scheduling showings, and sellers reviewing multiple offers will set aside any offer that arrives without a current lender letter. Get the pre-approval first, even if you are months away from being ready to move.
Two loan types dominate among first-time buyers here. FHA financing requires as little as 3.5% down and carries the most forgiving credit score thresholds, but it requires mortgage insurance — a monthly cost that does not disappear until you refinance or reach sufficient equity. Kendall County's FHA loan limit sits above the baseline for most Texas counties, which means FHA financing covers the majority of entry-level inventory in Boerne — check with your lender for the current figure, as limits adjust annually. Conventional financing at 3% down is available through Fannie Mae programs for first-time buyers and avoids some of FHA's upfront costs, though private mortgage insurance still applies until you reach 20% equity. Veterans and surviving spouses should ask their lender specifically about VA financing — no down payment, no mortgage insurance, and meaningful in this market given Boerne's proximity to San Antonio's military installations.
Step 2: Shop With Purpose
Boerne's inventory is not deep. Shopping without a clear list of non-negotiables — school boundary, commute tolerance, minimum square footage — means wasting weeks on homes that never fit. Decide before you start whether a Boerne ISD address is required or merely preferred; the district boundary matters more than most newcomers realize, and some addresses that feel like Boerne feed into neighboring districts.
Step 3: Write a Competitive Offer
Resale homes that are priced accurately tend to draw offers within the first week or two of listing. Your offer should include a pre-approval letter, a reasonable earnest money deposit (typically 1% of the purchase price in this market), and an option period. Texas uses a standard option period — usually 7 to 10 days — during which you pay a small option fee for the right to terminate for any reason. First-timers often want to shorten or waive this to compete. Do not. The option period is when your inspector works, and walking away from a major defect is far cheaper than owning it.
Step 4: Inspection, Appraisal, and Survey
Texas Hill Country homes have quirks worth inspecting carefully: limestone foundations that move differently than slab foundations in flat-terrain Texas, older septic systems in rural-adjacent lots, and HVAC systems that run hard through long summers. A thorough general inspection is non-negotiable. If the home has a well or septic, budget for those inspections separately — they are not included in a standard general inspection and they matter enormously for homes outside the city's water service area.
The appraisal is ordered by your lender and determines whether they will lend the agreed purchase price. If the home appraises below contract price, you will need to renegotiate with the seller, cover the gap in cash, or walk away using your financing contingency. In a more balanced market, appraisal gaps are less common than in 2021-2022, but they still happen on Hill Country properties where comparable sales are sparse.
Step 5: Closing
Texas closings are handled by title companies rather than attorneys. One detail that surprises nearly every first-timer in the state: Texas property taxes are paid in arrears, meaning the annual bill covers a year that has already passed. At closing, the seller credits you for their prorated share of the current year's taxes — taxes that you will then pay when the bill arrives. Budget for this credit to show up on your settlement statement and understand that your first full tax bill will arrive after you move in, not at closing.
How Much Home Can You Afford in Boerne
Closing costs for buyers in Texas typically run 2–5% of the purchase price, covering lender fees, title company charges, appraisal, and recording costs. The estimates below use 3% as a realistic midpoint for planning purposes. These are approximations — your actual figures will vary by lender, loan type, and negotiated seller concessions. The interactive calculator below this section lets you model your own scenario with current rate inputs.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (3%) | Cash Needed at Table |
|---|---|---|---|---|
| FHA 3.5% Entry-level | $390,000 | $13,650 (3.5%) | ~$11,700 | ~$25,350 |
| Conventional 3% Entry-level | $390,000 | $11,700 (3%) | ~$11,700 | ~$23,400 |
| FHA 3.5% Near city median | $562,000 | $19,670 (3.5%) | ~$16,860 | ~$36,530 |
| Conventional 3% Near city median | $562,000 | $16,860 (3%) | ~$16,860 | ~$33,720 |
| Conventional 5% Mid-range | $480,000 | $24,000 (5%) | ~$14,400 | ~$38,400 |
| Conventional 10% Mid-range | $480,000 | $48,000 (10%) | ~$14,400 | ~$62,400 |
A few Texas-specific line items to know before you sit down at the title company. The effective property tax rate in Boerne runs approximately 1.18% — a meaningful annual obligation your lender will escrow monthly, and the full picture is on the cost-of-living page. Owner's title insurance in Texas is a seller cost set by the state — you cannot negotiate it, and neither can they — but you will still pay for your own lender's title policy and your share of escrow fees. Factor those in when your lender provides the Loan Estimate document, which federal law requires within three business days of application.
Looking to buy in Boerne? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Boerne quote.
Common First-Time Buyer Mistakes in Boerne
Touring Before You Have a Lender Letter
This is the single most common and most costly mistake in a market where well-priced homes draw offers quickly. Agents here will still show you a home without pre-approval, but when the right one comes along, you will be writing an offer with one hand tied behind your back. Get pre-approved — fully, not pre-qualified — before you schedule a single showing.
Assuming the Builder's Sales Office Represents You
New construction communities in Boerne have on-site sales agents whose job is to represent the builder. They are good at their jobs. A first-timer walking in without their own agent often ends up signing a contract that locks in the builder's preferred lender, waives important contingencies, and leaves thousands of dollars in negotiable upgrades or closing-cost contributions on the table. Bring representation to a builder's office, or accept that you are negotiating alone against professionals.
Underestimating the Cash Needed at Closing
The down payment is the number first-timers rehearse, but it is rarely the biggest surprise at closing. Add 3–3.5% for closing costs, then remember the Texas property-tax proration: you will receive a credit from the seller for their share of the current year's taxes, but that credit does not reduce what you owe — it reduces what you pay at closing while you prepare to pay a full year's bill when it arrives in October. Budget for both simultaneously.
Ignoring School Boundary Reality
Boerne ISD — which holds an A rating, according to the Texas Education Agency — is the draw that brings many families here. But not every address in the Boerne area falls within the district. Some properties that market themselves with Boerne zip codes feed into neighboring districts, and boundary lines can shift with rezoning. If a Boerne ISD address is a hard requirement, verify the boundary with the district directly before going under contract, not after. The schools page has the full picture on the district.
Skipping the Option Period to Win the Offer
In a competitive situation, a seller's agent may suggest that waiving or shortening the option period makes an offer more attractive. That is true from the seller's perspective. From yours, the option period is the window in which your inspector works, your lender orders the appraisal, and you have a legal right to walk away without losing your earnest money. Boerne's Hill Country terrain — the rocky soil, the older septic systems in rural-adjacent lots, the HVAC demands of a Texas summer — makes a thorough inspection especially important. Losing an option fee is far less painful than discovering a foundation issue after you've closed.
Local Expert Takeaway: Boerne rewards first-time buyers who do their homework before they fall in love with a house. The market is more buyer-friendly than it was three years ago — new construction in particular leaves room to negotiate — but the cash requirements are real, and the closing-cost surprises are specifically Texan. Budget at least 3% of your purchase price for closing costs on top of your down payment, verify school boundary assignments directly with Boerne ISD before going under contract, and get a full pre-approval letter in hand before you tour anything. The buyers who get caught flat-footed here are almost always the ones who skipped one of those three steps.
Quick Takeaways & FAQs
✅ Kendall County's FHA loan limit sits above the Texas baseline, giving first-time buyers using FHA financing more borrowing room than in most Texas counties — ask your lender for the current figure, as limits adjust annually.
⚠️ The typical Boerne home price of $562,046 (July 2026) sits noticeably above what the city's median household income can comfortably carry alone, meaning most first-time buyers here need a strong dual income or significant savings.
📍 Texas property taxes are paid in arrears — expect a seller tax credit at closing and then a full annual bill arriving in October, a one-two punch that surprises nearly every out-of-state first-timer.
What is the minimum down payment to buy a home in Boerne, TX?
How much are closing costs for buyers in Boerne, Texas?
Is Boerne a good place for first-time buyers, or is it too expensive?
Do I need to verify school district boundaries before buying in Boerne?
What is the FHA loan limit for Boerne and Kendall County?
Moving to Texas?
Tell us what you need help with and we'll connect you with local resources.
