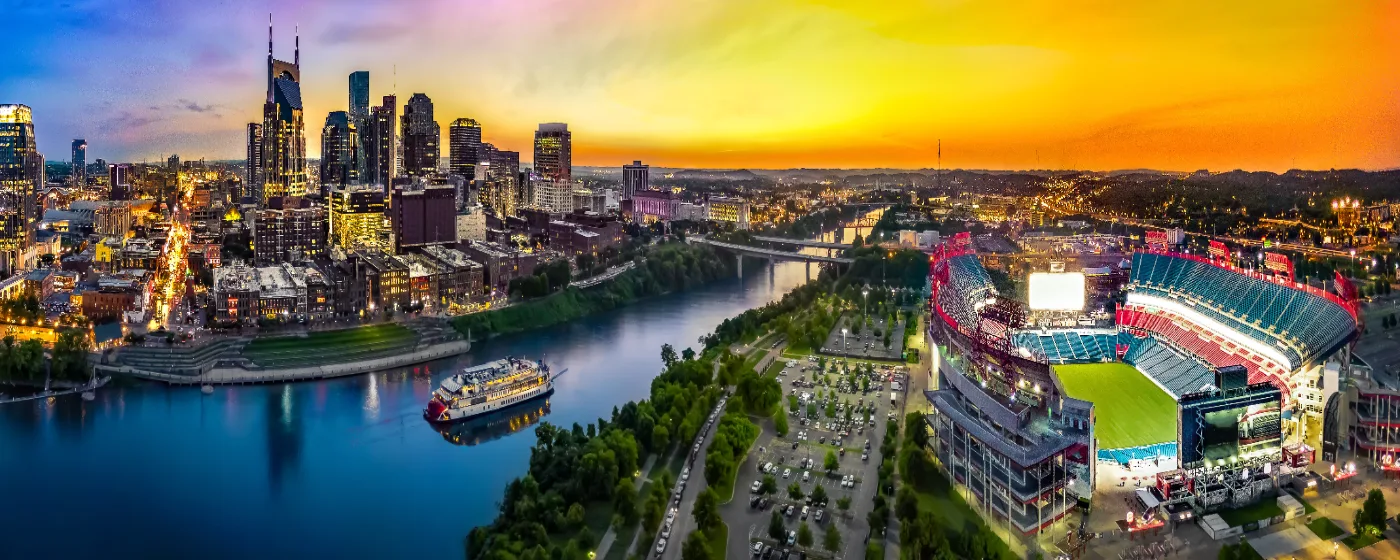
Maybe your company relocated you to Nashville and renting is starting to feel like throwing money at the fastest-growing city in the South. Maybe you've watched the market cool from its pandemic-era insanity and you're wondering if now is finally your window. Either way, the question on the table is the same: can a first-time buyer actually make this work in a city where the typical home price has settled well above what most households earn? The honest answer is yes — but the gap between the Zillow number and a closing table is wider here than in most mid-sized American cities, and you need to understand the mechanics before you fall in love with a house.
Nashville's economy is one of the reasons housing costs what it does. Vanderbilt University Medical Center and HCA Healthcare anchor the employment base; Bridgestone Americas and the State of Tennessee add manufacturing and government stability; and Oracle and Amazon have planted regional footprints here as well. That diversity keeps demand for housing steady even when national markets soften. The city's 721,074 residents also benefit from something most large metros can't offer: Tennessee levies no state income tax, which meaningfully stretches take-home pay and buying power compared with similarly priced metros in California or the Northeast.
The market that first-timers are walking into is considerably more hospitable than the one that defined Nashville from 2020 through 2022. The frenzy has moderated into something closer to balance. Roughly 15–17% of active listings in Davidson County have seen price reductions — which means overpriced homes sit, and a buyer who knows how to read a price history has real negotiating leverage. That said, the best-priced and best-presented homes still move quickly, so preparation matters as much as patience. The median household income of $75,197 sits meaningfully below what it takes to carry the typical home here, which means financing strategy isn't optional — it's where the plan either works or doesn't.
The sections below walk through what your budget actually buys in Nashville, the step-by-step process from pre-approval to closing, a budget snapshot table with realistic cash-at-table estimates, and the four mistakes that most reliably derail first-time buyers in this market.
The Nashville First-Time Buyer Reality
The Zillow Home Value Index puts Nashville's typical home price at $429,741 as of August 2026. That number is real and it is the anchor for every budget conversation you will have with a lender. What it doesn't tell you is that entry-level inventory — the starter homes that first-timers actually compete for — tends to cluster in areas like Antioch and Madison, where prices run below that city-wide figure, while neighborhoods like East Nashville, Inglewood, and Bellevue push above it. The neighborhoods page breaks down which areas sit where relative to that median.
The sub-$300,000 market exists but is thin — mostly condos, townhomes with HOA fees, or properties that need significant work. Climb toward the city median and you're looking at Donelson, which sits right at that figure, or at the competitive pockets of East Nashville and Inglewood above it. At each price point, the character of the neighborhood and what deferred maintenance you're accepting changes significantly.
The market's shift toward balance is genuine good news for first-timers. The median household income here sits about $40,000 below what it takes to comfortably carry the typical home at current rates — which is a structural challenge, not a temporary one. That gap is why financing mechanics matter so much in Nashville. It is also why the difference between a 3% and 3.5% down payment, or between a seller concession on closing costs and paying them yourself, can determine whether a deal pencils out at all. For more on how Nashville's costs stack up against neighboring markets like Franklin and Brentwood — both noticeably higher — see the cost-of-living page.
The Homebuying Process in Nashville, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
This is the step Nashville's local brokers flag most consistently, and it is the one first-timers most often skip. Getting pre-approved is not the same as getting pre-qualified. Pre-qualification is a lender's estimate based on self-reported numbers; pre-approval means a lender has pulled your credit, reviewed your income documentation, and issued a letter with a specific loan amount. In Nashville's market, a seller will not take your offer seriously without it — and more importantly, you will not know your real budget until you have it.
Do this before you walk into a single open house. The psychological cost of falling in love with a home that is $60,000 above your actual approval ceiling is real, and it happens more often than agents like to admit.
Step 2: Hire a Buyer's Agent and Start Shopping
A buyer's agent costs you nothing out of pocket in Tennessee — seller-paid commission structures still dominate the market here. Choose someone who works specifically in the neighborhoods you're targeting; the difference between Antioch and East Nashville in terms of what to inspect for, what to offer, and what to negotiate is significant. Your agent should be pulling comps, not just listing alerts.
Step 3: Make an Offer with the Right Contingencies
Nashville's moderated market means you generally do not need to waive inspection or financing contingencies to be competitive — on homes that have been sitting without activity. Where first-timers go wrong is treating every listing as if it's 2021: some well-priced homes in desirable pockets still move quickly, and coming in with a lowball offer or excessive contingency demands will lose you the house. Read the listing history before you decide how aggressive to be.
Step 4: Inspection, Appraisal, and the Due-Diligence Window
Tennessee uses an "Offer to Purchase" contract with a defined due-diligence period — typically 10 to 15 days in Davidson County. Do not skip or shorten the home inspection. Nashville's housing stock includes a significant proportion of mid-century construction that may have older HVAC systems, galvanized plumbing, or foundation issues related to the area's variable soil. The inspection is the single best investment a first-time buyer makes. If the appraisal comes in below the purchase price, you have options: renegotiate the price, make up the gap in cash, or walk away. Know which one you're prepared to do before the appraisal happens.
Step 5: Closing
Tennessee is an attorney-closing state, which means a licensed attorney — not just a title company — oversees the transaction and handles the deed. Budget for closing costs in the range of 2% to 4% of the purchase price, covering lender fees, title insurance, the attorney fee, prepaid property taxes, and homeowners insurance escrow. Davidson County property tax bills arrive in October and are due by the end of February; at closing, you will likely prepay a prorated portion into escrow. That prepaid amount is one of the most commonly underestimated line items on a first-time buyer's closing disclosure.
How Much Home Can You Afford in Nashville
The table below gives you a realistic picture of what different purchase prices require at the closing table. Closing cost estimates reflect the 2%–4% range typical for Davidson County and include lender fees, title, attorney, and prepaids. These are estimates — your actual figures will vary based on your lender, the specific property, and negotiated seller concessions. The interactive calculator below the table lets you run your own numbers at current rates.
One structural advantage Nashville buyers carry: the effective property tax rate here is approximately 0.81%, meaningfully below the national average. That difference shows up in your monthly payment and in how far your income stretches. Tennessee's lack of a state income tax provides additional headroom that buyers arriving from high-tax states often underestimate until they see their first Tennessee paycheck.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — entry-level | $290,000 | ~$10,150 (3.5%) | ~$5,800–$8,700 | ~$16,000–$19,000 |
| FHA (3.5%) — at city median | $429,741 | ~$15,041 (3.5%) | ~$8,600–$17,200 | ~$24,000–$32,000 |
| Conventional (3%) — entry-level | $290,000 | ~$8,700 (3%) | ~$5,800–$8,700 | ~$14,500–$17,500 |
| Conventional (3%) — at city median | $429,741 | ~$12,892 (3%) | ~$8,600–$17,200 | ~$21,500–$30,000 |
| Conventional (10%) — move-up entry | $500,000 | ~$50,000 (10%) | ~$10,000–$20,000 | ~$60,000–$70,000 |
| Conventional (20%) — avoid PMI | $429,741 | ~$85,948 (20%) | ~$8,600–$17,200 | ~$95,000–$103,000 |
FHA loan limits in Davidson County are set well above the typical Nashville purchase price, which means FHA financing is a genuine option for the vast majority of first-time buyers here — not a fallback reserved for the lowest price points. The HomeReady conventional loan option from Fannie Mae allows as little as 3% down for income-qualifying buyers and does not require perfect credit.
One note on private mortgage insurance (PMI): both FHA and low-down-payment conventional loans carry mortgage insurance costs. FHA loans include an upfront mortgage insurance premium at closing plus an ongoing monthly premium. Conventional loans with less than 20% down carry PMI, but it falls off automatically once you reach 20% equity — FHA mortgage insurance has different cancellation rules depending on your loan terms. Ask your lender to show you both scenarios side by side at your specific purchase price.
Looking to buy in Nashville? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Nashville quote.
Beyond the Monthly Mortgage Payment — What to Factor In
- The property tax rate above — The 0.81% used in the estimate is the median effective rate — tax actually paid as a share of market value — published by Ownwell, 2026. Half of local homes pay more and half pay less: your own bill depends on that property's assessed value and any exemptions it qualifies for, which can differ a lot from its market price. Confirm with the Davidson County assessor before you budget.
- Total cost of ownership — Your monthly mortgage payment is just the baseline. Depending on the specific city, county, and service district, homeownership costs also include local utility fees, municipal surcharges, and special assessments (such as water, sewer, storm drainage, or local energy taxes) that vary by location.
- Independent due diligence — Because these recurring local costs and municipal fees change depending on the exact property address, buyers must research them independently during their transaction process.
Tax laws, local municipal fees, and utility costs change frequently and individual situations vary. This page is general information, not tax or legal advice — always consult a qualified tax professional, CPA, or local municipal offices for personalized guidance.
Common First-Time Buyer Mistakes in Nashville
Shopping Without a Pre-Approval Letter
It bears repeating because it remains the most common error: touring homes without a lender letter in hand is not a low-stakes warm-up exercise. In Nashville's current market, a seller whose home has been sitting may still move faster than you expect once a well-qualified offer arrives. Showing up unprepared means you lose the house, or worse, you rush a financing decision under pressure that you should have made calmly two weeks earlier.
Waiving the Inspection to Compete
The pandemic-era pressure to waive inspections has largely passed in Nashville — but some buyers still do it, either from habit or bad advice. Nashville's existing housing stock has real risks: aging HVAC systems are common in mid-century homes in Donelson and Madison, and the city's clay-heavy soil can stress foundations in ways that aren't visible on a walkthrough. A waived inspection saves you nothing at closing and can cost you tens of thousands in the first year of ownership. Keep it.
Ignoring School Boundary and Commute Reality
Metro Nashville Public Schools holds a B- rating, according to Niche, and the district is large enough — 78,040 students enrolled in 2024-25 — that individual school quality varies significantly by zone. Two houses on the same block can feed into different elementary schools depending on where a boundary line falls. If school assignment matters to your household, verify the specific zoning for any address you're seriously considering, not just the general neighborhood reputation. Similarly, Nashville's interstate network means commute times vary wildly depending on which direction you're traveling and at what hour. A home that looks well-located on a map can sit on the wrong side of a daily bottleneck. See the schools page for the district breakdown.
Underestimating the Cash Needed at Closing
First-time buyers consistently budget for the down payment and forget about everything else. Closing costs in Davidson County realistically run 2% to 4% of the purchase price — on a $430,000 home, that is $8,600 to $17,200 before you've bought a single piece of furniture. Add the prepaid property tax escrow, the first year of homeowners insurance paid at closing, and any earnest money not credited at settlement, and the cash requirement at the table is almost always higher than buyers expect. Build the full closing cost range into your savings target from day one, not as an afterthought once you're under contract.
One practical lever: ask for seller concessions toward closing costs as part of your offer. In a market where 15–17% of listings have already taken a price reduction, a seller who has been sitting on a home often prefers a clean offer with a concession request over a lowball price reduction. Your agent should be modeling this trade-off every time you write an offer.
Local Expert Takeaway: Nashville is genuinely more accessible than it was three years ago — homes are sitting longer, price reductions are common, and sellers are negotiating. But the gap between the city's typical home price and the median household income is real, which means cash planning and financing mechanics are what separate buyers who close from buyers who keep renting. Get pre-approved first, budget for the full closing cost range (not just the down payment), keep your inspection contingency, and pay close attention to school boundaries and commute direction before you commit to a neighborhood. The market will reward preparation here more than it rewards urgency.
Quick Takeaways & FAQs
✅ Tennessee has no state income tax, which meaningfully extends buying power for Nashville residents compared with similarly priced markets in other states.
⚠️ The median household income in Nashville sits about $40,000 below what it takes to comfortably carry the typical home — financing strategy and cash planning are non-negotiable, not optional add-ons.
📍 Roughly 15–17% of Davidson County listings have taken price reductions, giving prepared buyers real negotiating leverage on homes that have been sitting — but well-priced homes in popular pockets still move fast.
What credit score do I need to buy a home in Nashville with an FHA loan?
How much cash do I actually need to buy a home in Nashville as a first-time buyer?
Is Nashville a competitive market for first-time buyers right now?
What are closing costs in Nashville and who pays them?
What is the FHA loan limit in Davidson County?
Moving to Tennessee?
Tell us what you need help with and we'll connect you with local resources.
