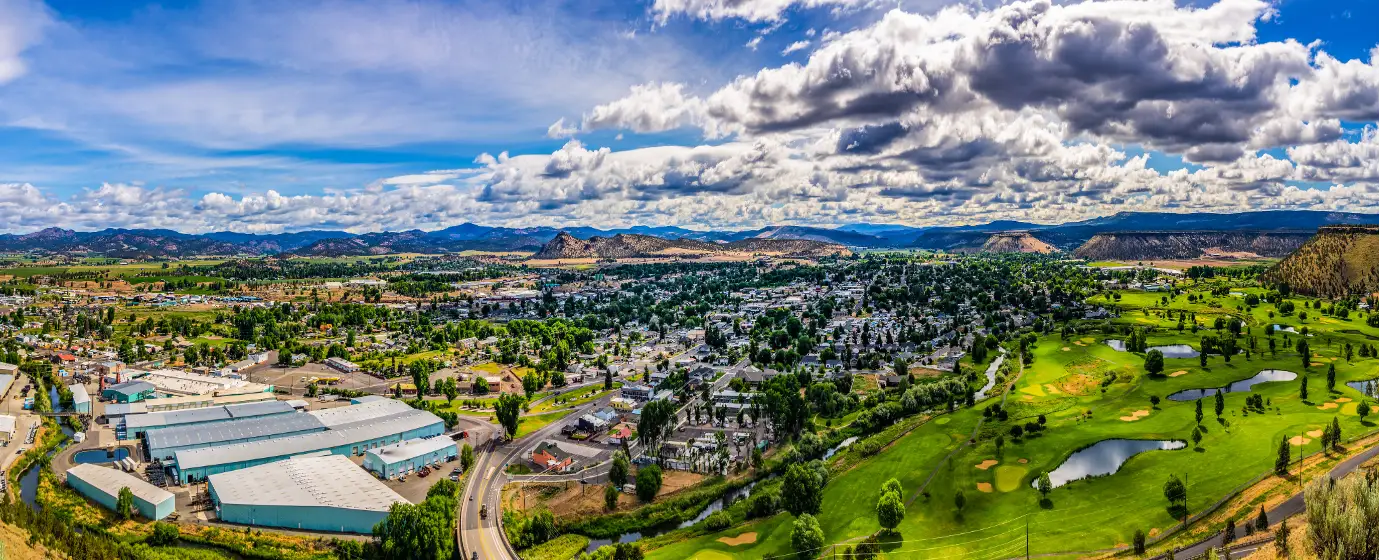
Maybe you've been priced out of Bend and someone mentioned Prineville. Maybe you've been renting in Central Oregon and finally feel ready to stop. Either way, the number that tends to stop people in their tracks is the typical home price: $433,014 (Zillow Home Value Index, July 2026) — real money, but noticeably below what you'd spend in Bend or Redmond for a comparable property. Prineville sits about 35 minutes to Bend along US-26, which means you can access a larger city's jobs and services without paying a larger city's home prices. That gap is the central reason first-time buyers keep landing here.
Prineville is a city of 11,917 that punches above its population in economic stability. Meta and Apple both operate hyperscale data center campuses here, and the Crook County School District, Crook County government, the City of Prineville, and Les Schwab Tire Centers' corporate operations round out the employer base. That mix gives the local economy a foundation most small Oregon cities don't have, which matters to lenders reviewing your file and matters to you when you're deciding whether the market you're buying into is stable. The Crook County School District holds a B- rating, according to Niche, if schools factor into your decision — the schools page has the full picture.
The effective property tax rate in Crook County is 0.56% — well below the national median and one of the genuine financial advantages of buying here rather than in a higher-tax Oregon county. On the cost side, the median household income in Prineville is $74,922, which sits below what it takes to comfortably carry the typical home at current prices, so budgeting honestly matters more here than in markets where incomes and prices align more closely. The good news: Prineville's zip code (97754) qualifies for USDA Rural Development loans, which means zero-down financing is a real option for buyers who meet the income limits — something Bend buyers simply don't have access to.
Whether you're trying to figure out what your budget actually buys, how to navigate the local buying process, or what mistakes to avoid, the sections below cover the Prineville first-time buyer reality from the ground up.
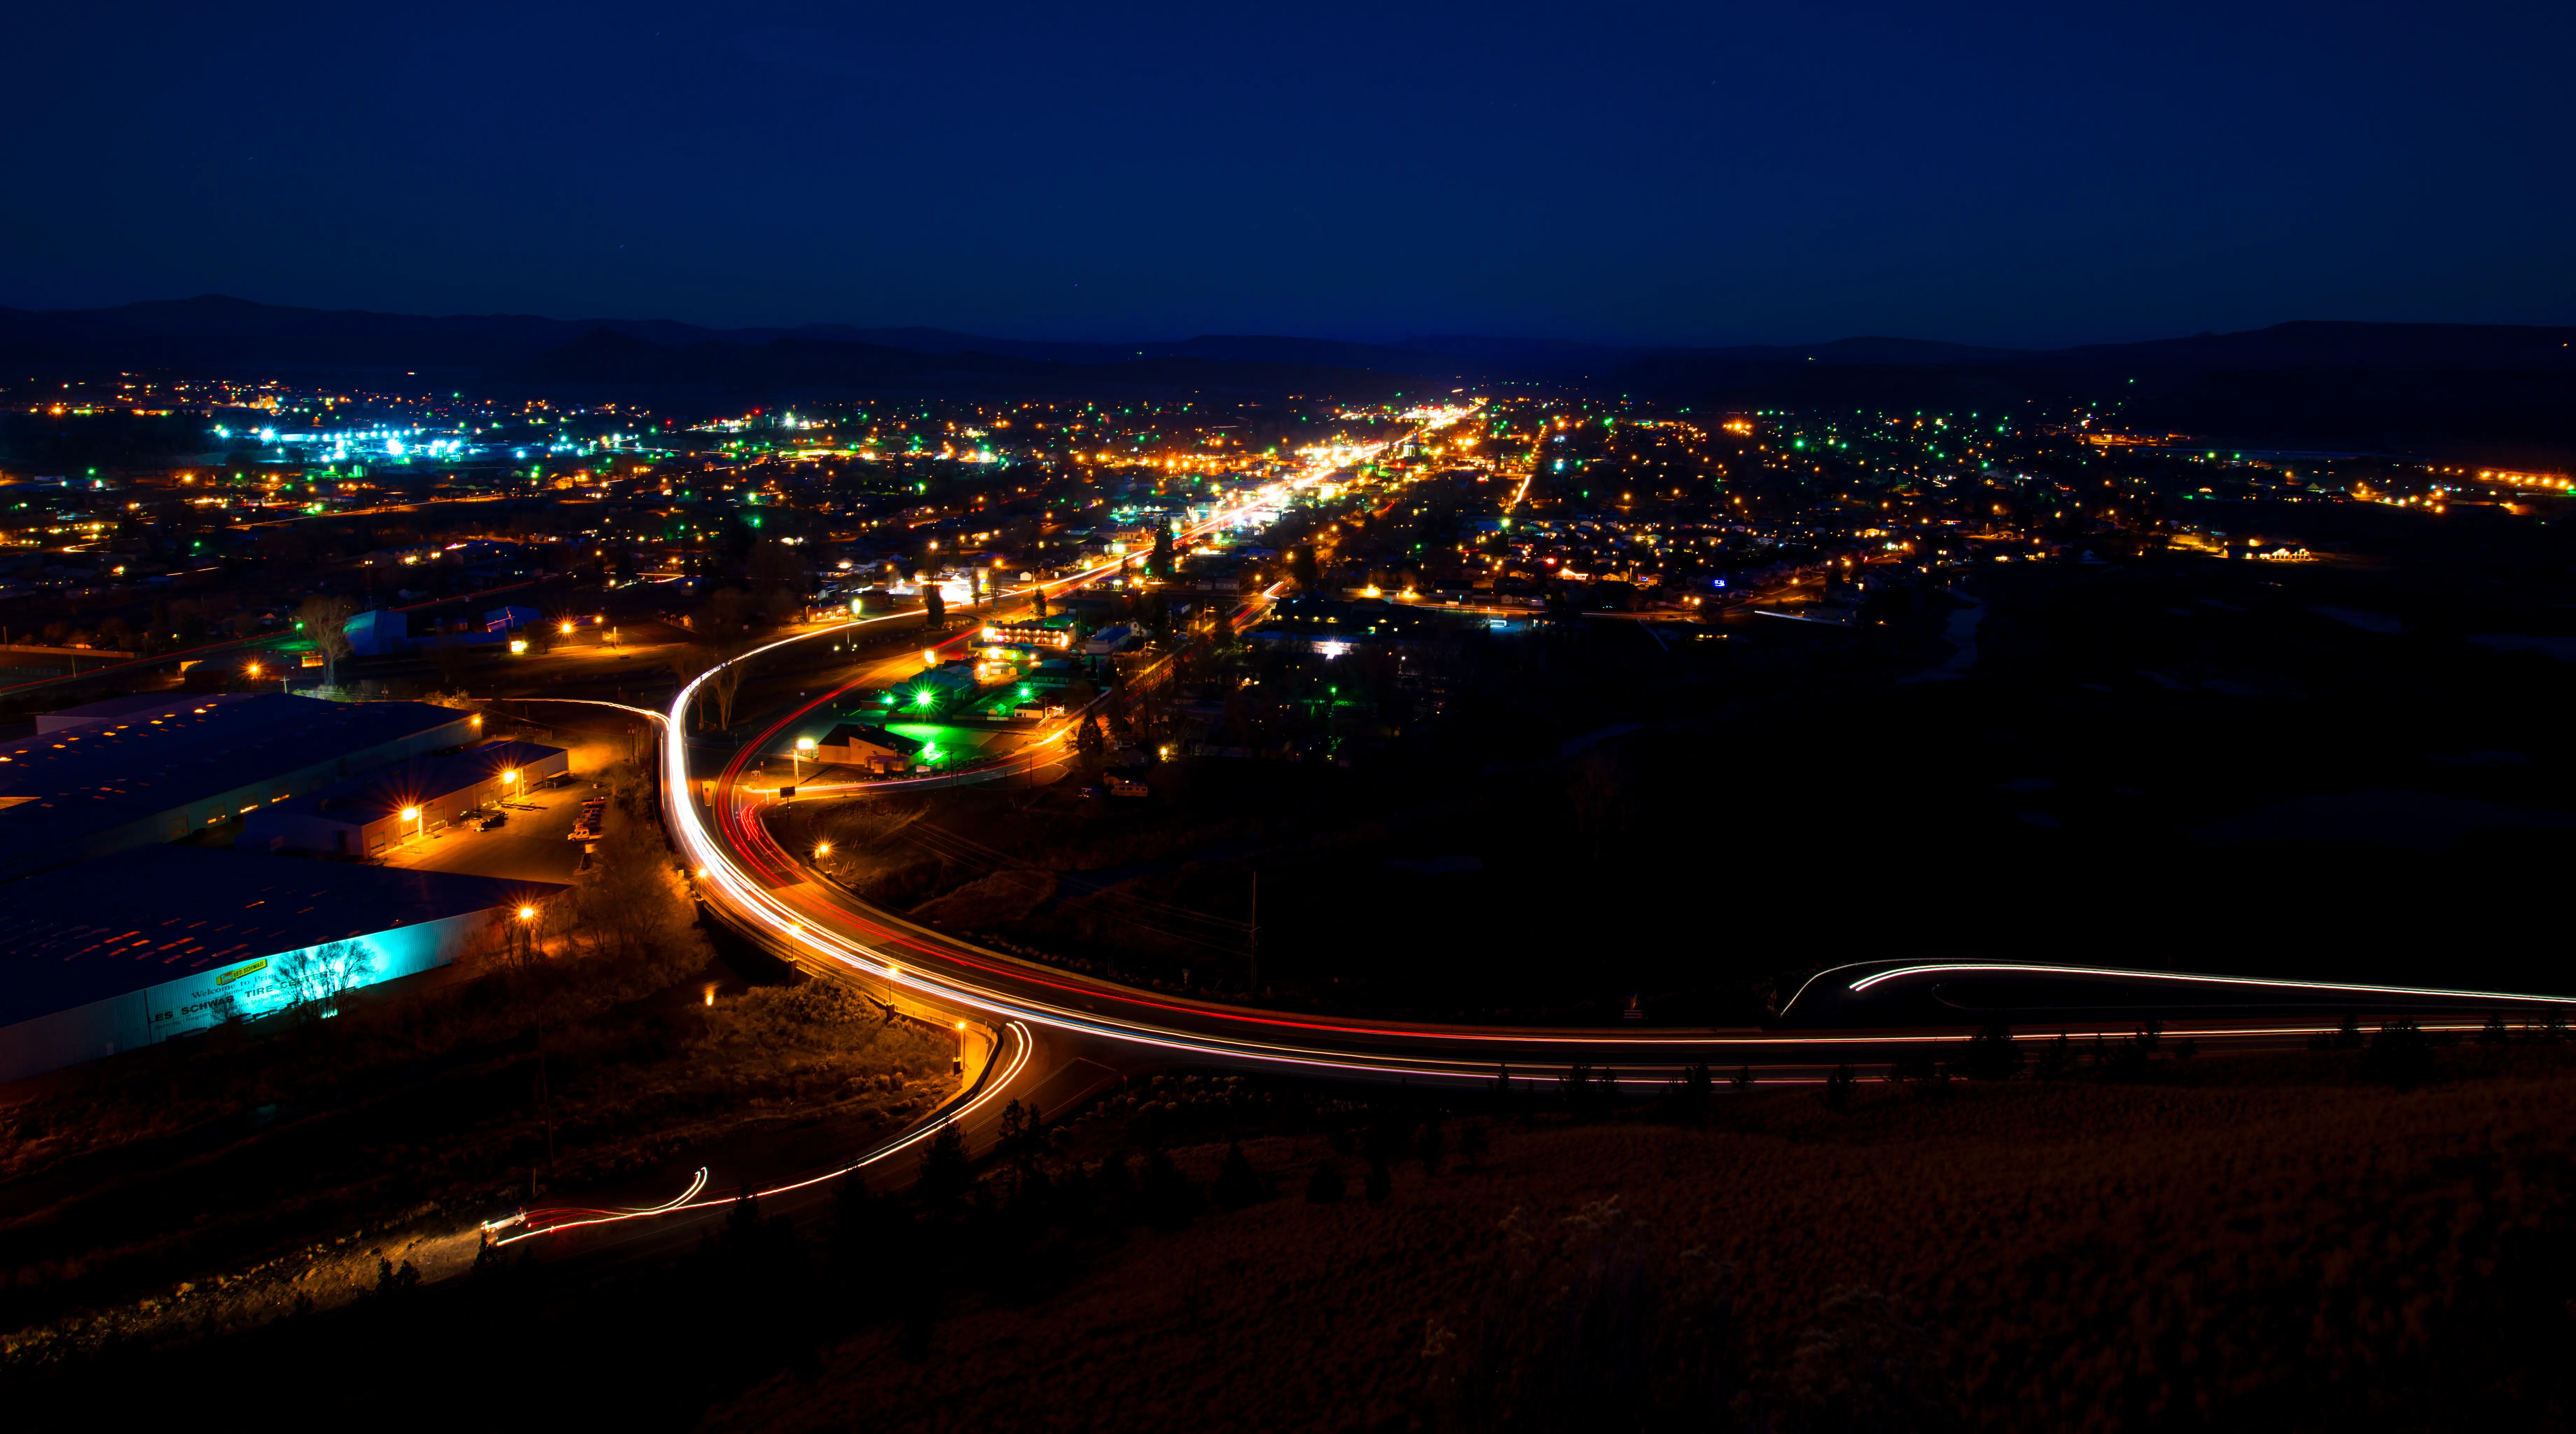
The Prineville First-Time Buyer Reality
The typical home price in Prineville is $433,014 (July 2026), and that figure tells only part of the story. Entry-level homes — older construction, smaller lots, properties needing some work — start closer to the low-to-mid $300,000s. Well-maintained three-bedroom homes in established neighborhoods like West Hills or near Downtown Prineville push into the $400,000s and above. The neighborhoods guide breaks down what each area of town feels like on the ground.
The affordability math is tighter than the price tag alone suggests. The median household income here is $74,922, which falls short of what most lenders want to see for a comfortable carry of the typical home. That doesn't mean homeownership is out of reach — it means your loan program choice, your down payment, and your closing cost reserves all matter more than they would in a market where incomes and prices line up cleanly.
One real advantage that often surprises buyers: Prineville qualifies for USDA Rural Development financing, which allows zero down payment for eligible buyers. FHA loans require a minimum 3.5% down with a credit score of 580 or higher. Conventional loans at 3% down are available but come with private mortgage insurance until you build equity. The pace of the market here is deliberate rather than frantic — homes tend to sit longer than they did during peak seller conditions — which gives first-time buyers more time to do due diligence and negotiate without the pressure of a ten-offer weekend.
The Homebuying Process in Prineville, Step by Step
Step 1: Get Pre-Approved Before You Look at a Single Home
This is the step most first-time buyers in Prineville skip, and it costs them. Sellers in a small market move fast once the right offer arrives, and showing up without a lender letter means you're not a real buyer yet. Local lenders with Prineville experience — including Guild Mortgage and New American Funding, both of which have loan officers serving this market — can walk you through FHA, VA, USDA, and conventional options before you fall in love with a property you can't finance.
USDA eligibility is worth confirming early. If your household income falls under the Crook County moderate-income limit (approximately $119,850 for a household of one to four), a USDA Section 502 Guaranteed Loan can finance 100% of the appraised value with no down payment required. That changes your entire cash-to-close calculation. Confirm your eligibility directly with a USDA-approved lender — the numbers are subject to annual adjustment.
Step 2: Search with a Local Agent Who Knows the Market
Prineville is a small inventory market. An agent who covers Bend may not know that Indian Rock Estates and Juniper Canyon are meaningfully different in feel and commute convenience, or which neighborhoods sit closest to US-26 for buyers who make that drive regularly. A locally focused agent surfaces listings faster and knows which sellers are motivated.
Step 3: Make an Offer with All the Right Contingencies Intact
Prineville's deliberate pace gives you leverage to negotiate, but don't confuse more time on market with a signal to skip contingencies. Keep your inspection contingency. Keep your financing contingency. An inspection in a market like this one — older housing stock, high desert climate, potential deferred maintenance — is not the place to cut corners. First-time buyers who waive the inspection to look more competitive on price often discover foundation issues or HVAC problems that a few hundred dollars of due diligence would have caught.
Step 4: Inspection, Appraisal, and Final Underwriting
Oregon requires a licensed inspector, and this is the step most often underestimated by first-timers in terms of time and attention required. The inspection report gives you negotiating leverage if problems surface. The appraisal confirms the lender's collateral value — if the home appraises below your purchase price on a USDA or FHA loan, you'll need to renegotiate or cover the gap in cash. Both steps happen after your offer is accepted and before closing.
Step 5: Close and Get the Keys
Oregon is an escrow state — a title or escrow company, not an attorney, handles the closing. You'll sign at the title company, wire your closing funds, and typically receive keys the same day the deed records. Budget two to four weeks from accepted offer to close for a standard purchase, though USDA loans sometimes run a week or two longer due to USDA's own review process. Factor that into any rental move-out timing.
How Much Home Can You Afford in Prineville
The table below shows approximate cash requirements at closing for several realistic purchase price scenarios in Prineville. All figures are estimates — actual closing costs vary by lender, loan type, title company, and negotiated seller concessions. Use these as planning ranges, not final numbers. The interactive mortgage calculator below the table will give you a payment estimate once you enter your own figures.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| USDA (0% down) | $310,000 | $0 | ~$6,200–$8,500 | ~$6,200–$8,500 |
| FHA (3.5% down) | $310,000 | ~$10,850 | ~$6,200–$8,500 | ~$17,050–$19,350 |
| FHA (3.5% down) | $390,000 | ~$13,650 | ~$7,800–$10,000 | ~$21,450–$23,650 |
| Conventional (3% down) | $390,000 | ~$11,700 | ~$7,800–$10,000 | ~$19,500–$21,700 |
| Conventional (5% down) | $433,000 | ~$21,650 | ~$8,660–$11,000 | ~$30,310–$32,650 |
| Conventional (10% down) | $433,000 | ~$43,300 | ~$8,660–$11,000 | ~$51,960–$54,300 |
Closing costs in Oregon typically run 2–3% of the purchase price and include lender fees, title insurance, escrow fees, prepaid homeowners insurance, and prepaid property taxes. Crook County's effective property tax rate of 0.56% is well below the national norm, which keeps the property tax prepaid component of closing costs lower than buyers coming from higher-tax states might expect — see the cost-of-living page for the full tax picture.
First-time buyers on tighter cash reserves should ask their agent to negotiate seller concessions toward closing costs — in a market where homes are sitting longer, sellers are often willing to contribute.
Looking to buy in Prineville? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Prineville quote.
Common First-Time Buyer Mistakes in Prineville
Shopping Before Pre-Approval
In a small inventory market like Prineville, the gap between browsing and buying can close very fast once a well-priced home appears. Buyers who haven't confirmed their loan program and credit qualification end up watching the right property go under contract to someone who had their paperwork ready. Get a full pre-approval — not just a pre-qualification — before you start touring.
Skipping or Waiving the Inspection
Prineville's housing stock includes a meaningful share of older homes, and the high desert climate is hard on roofs, HVAC systems, and wood framing. Waiving your inspection contingency to appear more competitive is a risk that rarely pays off here. A thorough inspection is one of the best investments you'll make in the buying process — and if problems surface, it gives you documented grounds to renegotiate or walk away. First-time buyers who skip it often learn why experienced buyers don't.
Overlooking the Commute and Lifestyle Trade-Off
Prineville is about 35 minutes to Bend, and that drive is easy to underestimate in the excitement of finding an affordable home. Over five years, that commute adds up — and US-26 through the canyon is a winter driving reality, not just a scenic route. If you or a partner commute to Bend or Redmond for work, spend a week driving the route at actual commute hours before you commit. What feels fine on a Saturday afternoon in October can feel very different on a February morning. For a fuller look at how daily life in Prineville actually works, the living in Prineville page covers commute and lifestyle in more depth.
Underbudgeting Cash to Close
First-time buyers consistently underestimate total cash to close because they focus on the down payment and forget the full closing cost stack — lender fees, title insurance, escrow, prepaid insurance, and prepaid taxes. On a $390,000 purchase with 3.5% down, you're looking at roughly $21,000–$24,000 needed before the keys change hands. USDA loans eliminate the down payment but still require closing costs of approximately $6,000–$10,000 depending on the purchase price. Build a cash cushion above your minimum — unexpected inspection repair negotiations or a short appraisal gap can require cash you won't have if you spent every dollar to get to the table.
Local Expert Takeaway: Prineville is one of the few Central Oregon cities where USDA zero-down financing is still on the table, and where the effective property tax rate of 0.56% meaningfully lowers the long-term cost of ownership compared to higher-tax markets. The catch is that the typical home price of $433,014 (July 2026) sits above what the median local income comfortably supports — which means your loan program, your reserves, and your pre-approval need to be airtight before you start seriously looking. The market here rewards patient, prepared buyers: homes take longer to move than they did in peak years, sellers are more willing to negotiate, and a well-structured offer with contingencies intact is not a weakness. Do the financial groundwork first, confirm your USDA eligibility if income allows, and line up a local lender who knows Crook County before you fall in love with a listing.
Quick Takeaways & FAQs
✅ Prineville is USDA loan-eligible (zip code 97754), meaning qualified first-time buyers can purchase with zero down payment — an option not available in Bend or Redmond.
⚠️ The typical home price of $433,014 (July 2026) exceeds what the median local household income comfortably supports, so budgeting honestly and choosing the right loan program matters more than in higher-income markets.
📍 Crook County's effective property tax rate of 0.56% is well below the national median, which reduces the long-term ownership cost and lowers the property-tax component of your closing costs.
Does Prineville qualify for USDA home loans?
What is the minimum down payment to buy a home in Prineville?
How much should I budget for closing costs in Prineville?
Is the Prineville housing market competitive for first-time buyers?
How does the Prineville school district factor into buying a home here?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
