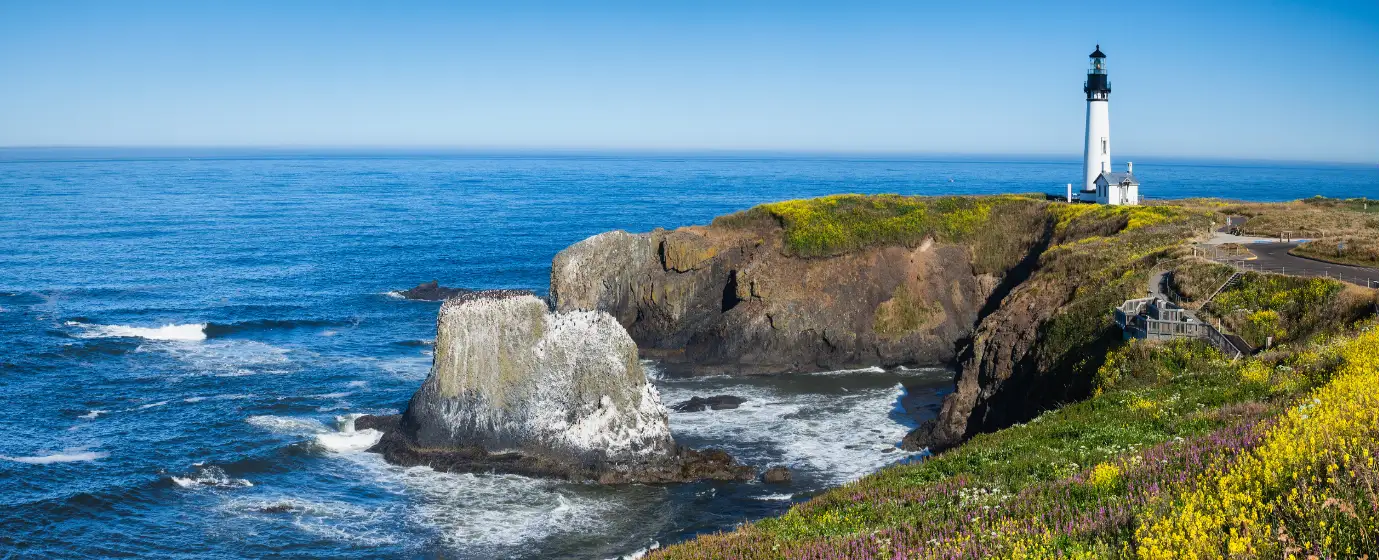
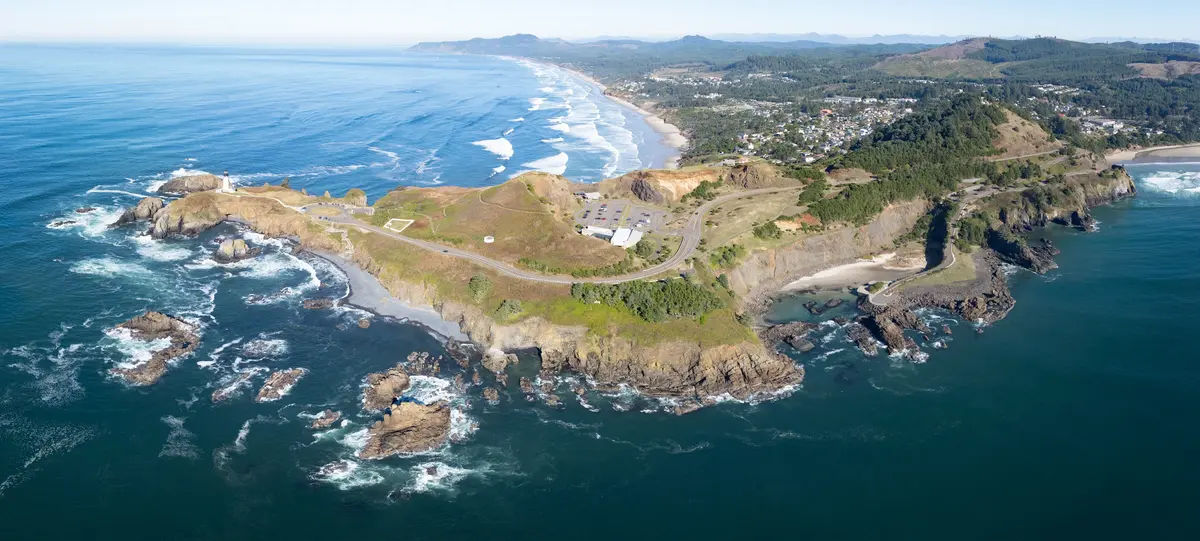
Maybe your rent feels like a mortgage payment and someone suggested looking at property on the Oregon Coast. Maybe you've been watching Newport from a distance, drawn by the idea of owning something real in a place that doesn't feel like anywhere else. Either way, the first thing to understand is that Newport's housing market is not the same animal as Portland's or Eugene's — it moves differently, prices differently, and comes with a layer of coastal-specific due diligence that most first-time buyers from inland don't see coming. The city of 10,833 sits where US-101 and US-20 (the Corvallis-Newport Highway) converge at the Pacific, which puts it at the end of a long road for most of the state and at the beginning of something else entirely for people who actually live here.
Newport is the economic anchor of Lincoln County. The major employers — Samaritan Pacific Communities Hospital, the Lincoln County School District, Oregon Department of Fish and Wildlife, the City of Newport itself, and the NOAA Marine Operations Center — provide a stable but modest local job base. The median household income sits at $60,568, which is below what most lenders consider comfortable for carrying the typical home here. That gap is real, and understanding it is the starting point for every first-timer's plan. Loan program selection matters here more than in markets where incomes and prices are better aligned. For full cost-of-living context, the cost of living page has the complete breakdown.
The typical home in Newport is priced at $454,809 (Zillow Home Value Index, July 2026). That number sits well below what buyers face in Depoe Bay to the north, and meaningfully above Toledo and South Beach. The housing stock itself is more varied than many first-timers expect: roughly half of Newport's units are single-family detached homes, with duplexes, converted apartments, condos, and manufactured homes making up the rest. Manufactured homes offer the most accessible entry points in this market; site-built homes account for the majority of active inventory and command proportionally higher prices. Conditions have shifted toward buyers in recent years, and sellers are more willing to offer concessions — covering a portion of closing costs or buying down your rate — than they were during the peak years.
Whether you've never bought a home anywhere or you're moving from a different state, this guide walks through what a first-timer's budget actually buys in Newport, the step-by-step process including the two steps buyers most often get wrong, a realistic budget snapshot table, and the specific mistakes that cost Newport buyers the most.
The Newport First-Time Buyer Reality
Newport is not a market where you will find a starter home for $250,000. The typical home price is $454,809 (July 2026), and the entry point for a site-built single-family home runs higher than that figure suggests if you're filtering for move-in-ready condition. Manufactured homes are the realistic path into the market below that threshold, and they are a legitimate option here — not a consolation prize, but an actual category of inventory that a range of buyers pursue intentionally.
The income-to-price gap is the defining constraint for Newport's first-time buyers. The median household income in the city is $60,568, which falls well short of what most lenders calculate as comfortable for carrying the typical home at current rates. That doesn't mean buying is impossible — it means loan program selection, down payment size, and debt management are not abstract planning exercises. They are the difference between qualifying and not.
Two federal programs matter more here than most Oregon markets. The current FHA loan limit for Lincoln County covers most Newport purchases, so FHA's low down-payment path with more forgiving credit requirements than conventional financing is widely accessible here. More unusually, every community in Lincoln County qualifies for USDA Rural Development financing, which offers 100% financing with no down payment required for buyers whose household income falls within the program's income limits. Buyers should verify their specific address through USDA's eligibility tool, since qualification is confirmed property by property, not just by city. Newport's coastal location also adds a layer that inland markets skip: tsunami inundation zone disclosures, flood zone mapping, and coastal inspection requirements are standard parts of any transaction here, and they affect both insurability and long-term cost.
The Homebuying Process in Newport, Step by Step
Step 1: Get Pre-Approved — Before You Tour Anything
Pre-approval is not the same as pre-qualification. Pre-qualification is a rough estimate based on self-reported numbers. Pre-approval involves a hard credit pull, verified income documents — paycheck stubs, W-2s, tax returns — and an actual underwriting review. Sellers and their agents in Newport's market treat the two very differently. If you show up to a showing without a pre-approval letter, you are not a buyer yet.
Shop at least two or three lenders before settling on one. Multiple credit inquiries from mortgage lenders within a 45-day window count as a single inquiry against your credit score, so you lose nothing by comparing. One lender may have better terms on an FHA loan while another has a better conventional product. Given Newport's USDA eligibility, it is worth confirming whether your specific address qualifies — not every lender in the state actively originates USDA loans.
Step 2: Define Your Search with Coastal Specifics in Mind
Newport's neighborhoods vary considerably in flood zone exposure, elevation, and tsunami inundation risk. Oregon law requires sellers to disclose whether a property sits within a mapped tsunami inundation zone on the standard disclosure form — but elevation is what determines actual risk. A home technically within a mapped zone at 40 feet of elevation is in a dramatically different situation than one at sea level in the same zone. Oregon's geologic hazard mapping tools include elevation data, and a buyer who understands how to read them before touring is a more effective buyer.
Tsunami inundation zones and FEMA flood zones are two separate mapping systems measuring different risks. A property can be in one and not the other. Properties in Special Flood Hazard Areas typically require flood insurance, which adds to the monthly carrying cost the engine's calculator can help you model.
Step 3: Make the Offer — and Know What to Negotiate
In the current coastal Oregon market, sellers are more willing to offer concessions than during the peak years — covering a portion of closing costs, buying down your rate, or crediting for repairs. First-time buyers who ask for nothing leave money on the table. A seller concession that covers two points of closing costs meaningfully reduces what you need to bring to closing, which matters most when cash reserves are tight.
Step 4: Inspection — Coastal, Not Generic
A standard home inspection is not enough on the Oregon Coast. Your inspector should specifically evaluate moisture control, corrosion on metal components, siding condition for weather damage or warping, hurricane ties, and seismic retrofitting. These are issues that an inspector trained primarily on inland homes may underweight. Ask explicitly whether they have experience with coastal properties before you book one.
Step 5: Appraisal and Closing
If you're using FHA or USDA financing, an appraisal is required and will be ordered by your lender after the offer is accepted. The appraisal must meet the program's minimum property standards, which can occasionally surface deferred maintenance issues the inspection also flagged. Oregon closings typically go through a title company, and closing costs generally run 2–5% of the purchase price. Budget for the higher end of that range until you have a Loan Estimate in hand — your lender is required to provide that document early in the process so you can plan from a real number rather than a rough estimate.
How Much Home Can You Afford in Newport
The table below maps several realistic purchase scenarios against the cash you'd need at closing. Closing cost estimates assume 2–5% of the purchase price; the lower end applies when sellers cover a portion. Down payments are shown at the minimum for each loan type. The interactive calculator below the table lets you adjust rates, term, and property tax to model your specific situation — use these rows as starting points, not final answers.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| USDA (0% down, income-eligible) | $350,000 | $0 | $7,000–$17,500 | ~$7,000–$17,500 |
| FHA (3.5% down) — manufactured home entry | $280,000 | ~$9,800 | $5,600–$14,000 | ~$15,400–$23,800 |
| FHA (3.5% down) — near city typical | $454,809 | ~$15,900 | $9,100–$22,700 | ~$25,000–$38,600 |
| Conventional (3% down) — near city typical | $454,809 | ~$13,600 | $9,100–$22,700 | ~$22,700–$36,300 |
| FHA (3.5% down) — site-built above median | $520,000 | ~$18,200 | $10,400–$26,000 | ~$28,600–$44,200 |
| Conventional (5% down) — site-built above median | $520,000 | $26,000 | $10,400–$26,000 | ~$36,400–$52,000 |
Seller concessions — increasingly common in the current coastal market — can reduce the closing cost portion of these figures by several thousand dollars. At current interest rates, use the calculator below to see how each purchase price affects your estimated monthly payment.
One structural note: the FHA ceiling for Lincoln County covers all rows in this table, so FHA eligibility is not a barrier at any of these price points. USDA requires verifying your specific property address through the USDA eligibility tool, since qualification is address-by-address, not blanket citywide. If you're purchasing with rental income intentions, verify current city zoning rules before committing — Newport's short-term rental regulations are actively evolving and allowances are limited largely to tourist and commercially zoned areas.
Looking to buy in Newport? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Newport quote.
Common First-Time Buyer Mistakes in Newport
Shopping Before Pre-Approval
This is the most common and most costly mistake in Newport's market. Buyers who tour homes without a pre-approval letter in hand don't know what they can actually offer — and when a well-priced property comes available, they lose it in the days it takes to get documentation together. The coastal inventory, especially at entry-level price points, is not so deep that you can afford to be unready. Get the letter before you tour anything.
Treating the Inspection Like an Inland Inspection
A buyer who skips the inspection or uses an inspector unfamiliar with coastal construction is taking a specific kind of risk. Salt air, frequent rain, and seismic activity create conditions that accelerate problems most buyers never think to check: corroded fasteners, moisture intrusion behind siding, decks without proper hurricane ties, foundation issues related to shifting soils. These are not hypothetical concerns. Ask your inspector about their coastal experience before you book, and do not waive the inspection contingency here regardless of competitive pressure.
Ignoring Tsunami and Flood Zone Disclosures
Oregon law requires the seller to disclose tsunami inundation zone status on the property disclosure form, and most Newport buyers see that disclosure and move on without understanding what it means for insurance, resale, and long-term livability. Elevation is the variable that matters most — two homes in the same mapped zone can face very different risk profiles. Separately, FEMA flood zones and tsunami zones use different maps measuring different risks, and a property near the water may require flood insurance that significantly affects your monthly costs. Review Oregon's publicly available geologic hazard elevation maps for any property you're seriously considering before making an offer.
Underbudgeting Cash at Closing
Closing costs in Oregon typically run 2–5% of the purchase price. On a $454,809 purchase, that's a range of roughly $9,000 to $22,700 on top of your down payment. First-time buyers routinely budget for the down payment and then get surprised by what arrives in the final settlement statement three days before closing. Add to that the cost of a coastal-specific inspection, homeowners insurance that accounts for wind and flood exposure, and any immediate repairs — and the total cash needed at the table can land well above what a simplified calculator suggested. Build in a buffer, and ask your lender for the Loan Estimate as early in the process as possible so you can plan from a real number rather than a rough estimate.
Local Expert Takeaway: Newport is one of the few Oregon coastal cities where USDA 100% financing is available — every address in Lincoln County qualifies by geography — and where the FHA county ceiling sits high enough to cover most purchases at or above the typical home price. That combination makes the financing landscape more accessible than the income-to-price gap initially suggests. The catch is coastal-specific: tsunami zone disclosures, moisture and seismic inspection requirements, and evolving short-term rental rules are not paperwork formalities here. They are real variables that affect insurance cost, resale, and what the home actually costs to own. First-time buyers who do that homework before making an offer — and who get a pre-approval letter before they tour — are in a materially better position than those who learn it mid-transaction.
Quick Takeaways & FAQs
✅ Every address in Lincoln County qualifies for USDA 100% financing, and the FHA loan limit for Lincoln County covers most Newport purchases — giving first-time buyers more loan options here than in many Oregon markets.
⚠️ Newport's median household income falls well below what's typically needed to carry the typical home comfortably, making loan selection and cash planning more critical here than in higher-income markets.
📍 Oregon law requires tsunami inundation zone disclosure on every property sale — but elevation, not the zone designation alone, is what determines real risk, so review Oregon's geologic hazard elevation maps for any home you're serious about.
What is the typical home price in Newport, Oregon right now?
Can I use an FHA loan to buy a home in Newport, Oregon?
Does Newport qualify for USDA home loans with no down payment?
What do I need to know about tsunami zones when buying in Newport?
How much cash do I need to buy a home in Newport as a first-time buyer?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
