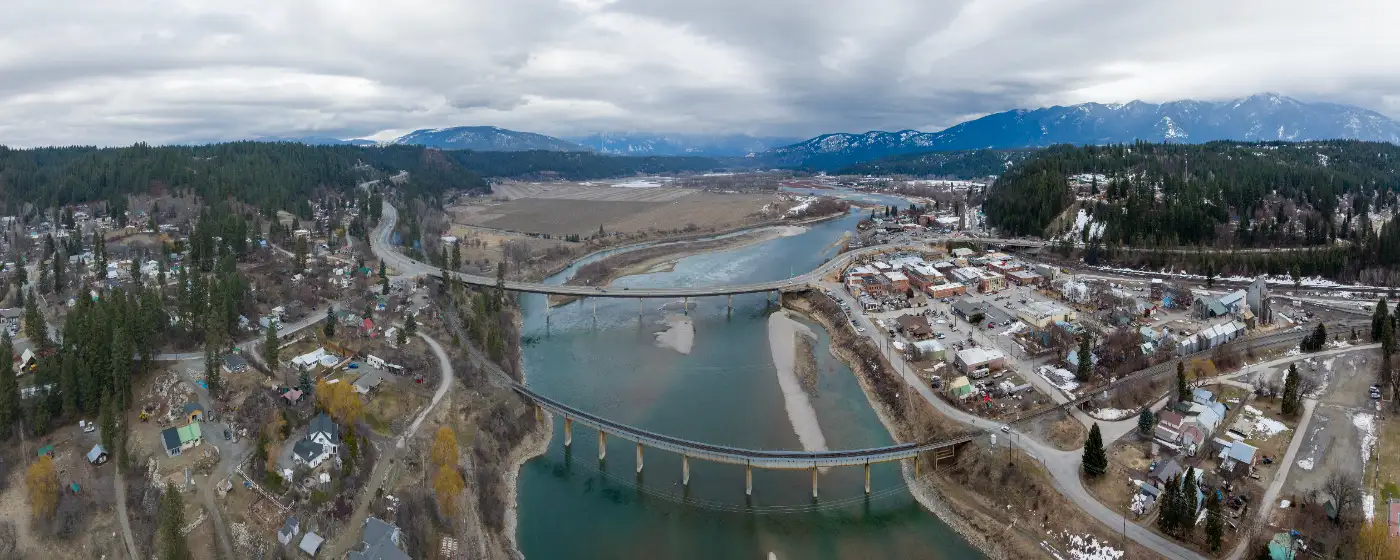
Maybe you've been priced out of the Boise or Spokane markets and someone mentioned North Idaho. Maybe you're already working in Bonners Ferry and you're done paying rent. Whatever brought you here, the first thing to understand about buying a home in Bonners Ferry is this: the prices that look affordable on paper are real — but the inventory is thin, and the market moves faster than a small-town zip code would suggest. The median sale price here sits at $360,000 (mid-2026 median sold price), and that figure is within reach for a first-time buyer with steady income and the right loan structure — but only if you show up prepared.
Bonners Ferry is a working town of about 2,700 people anchored by the lumber industry, local government, and the Kootenai Tribe's gaming and hospitality operations. Those employers define the local economy and set the realistic income ceiling for most buyers here. The median household income sits at $52,500 — meaning a $360,000 purchase is a genuine stretch for many first-timers, and getting your financing structure right before you ever set foot in a house is not optional. Boundary County's effective property tax rate of approximately 0.32% is well below the Idaho statewide average, which meaningfully lowers your monthly carrying cost compared to most markets. See the full cost-of-living breakdown for how all the numbers stack up.
The inventory picture is what surprises most first-timers after a month of searching. Bonners Ferry has essentially no condos or townhomes on the market — the active listings are almost entirely single-family homes and land. That concentration means you're competing for a narrow pool of product, and when a well-priced house hits the MLS, it doesn't always sit for six weeks. Homes average about 2% below list price at closing and go pending in roughly 26 days — giving buyers modest room to negotiate, but not the months-long runway some expect.
This guide walks through what your budget actually buys in today's Bonners Ferry market, the step-by-step buying process as it plays out locally, a concrete budget snapshot across common loan scenarios, and the specific mistakes that cost first-time buyers here time, money, or the house itself.
The Bonners Ferry First-Time Buyer Reality
The $360,000 median sale price positions Bonners Ferry as one of the more accessible markets in North Idaho — noticeably below what comparable homes fetch in Sandpoint, roughly 45 minutes south. But affordable is relative when your household income is near the local median of $52,500. At that income, a conventional lender will typically qualify you for a purchase in the $280,000–$340,000 range before factoring in debts, which means the median-priced home sits just at or slightly above comfortable territory for many first-timers without a co-borrower or meaningful savings.
The entry-level homes in this market — those priced well below median — tend to be older single-family construction with some deferred maintenance baked into the price. As you move toward and above median, you gain better condition and occasionally newer builds. At the upper end of what most first-timers can qualify for, you start seeing homes with modest acreage in the surrounding valley. For a deeper look at what specific price bands correspond to in each part of town, the neighborhoods guide breaks that down.
The market is not a bidding-war environment by Boise or Coeur d'Alene standards — but it's not a buyer's market either. Well-conditioned homes in the right price band can go pending in under two weeks. The practical takeaway for a first-timer: you have time for due diligence on most listings, but you cannot afford to spend two weeks getting pre-approved after finding the house you want. Preparation is the variable that separates buyers who close from buyers who miss.
The Homebuying Process in Bonners Ferry, Step by Step
Step 1: Get Pre-Approved — Before You Tour Anything
This is the step first-time buyers most commonly skip or delay in Bonners Ferry, and it's the one that costs them houses. Pre-approval is not a formality here — sellers in a small inventory market expect to see it with any offer. A pre-qualification letter (the quick, unverified version) is not the same thing. Get the full pre-approval: tax returns, pay stubs, bank statements, the whole package reviewed by an underwriter.
Step 2: Understand Your Loan Options for This Market
Three loan types fit most Bonners Ferry first-timers. FHA loans require 3.5% down and are available up to $524,225 in Boundary County — well above the current median, so nearly every home here qualifies. Conventional loans with 3% down are also available and carry no upfront mortgage-insurance premium, though private mortgage insurance applies until you reach 20% equity. USDA Direct loans deserve serious attention here: Bonners Ferry qualifies as a USDA-designated rural area, and the USDA Single Family Housing Direct program carries a rate of 5.250% (as of August 1, 2026) with no down payment required for income-eligible borrowers — though maximum loan amounts are determined by your income and household size, not a fixed ceiling. Talk to a lender about USDA eligibility early; the income limits are specific and the approval timeline is longer than FHA or conventional.
Step 3: Work With a Local Agent and Search Realistically
Bonners Ferry's MLS inventory is small enough that an agent who monitors it daily matters. Set up automated alerts and factor in distance from town when filtering areas — some of the most appealing rural properties look close on a map but add meaningful time to everyday errands and appointments.
Step 4: Make an Offer That Reflects Local Norms
With homes averaging about 2% below list price at closing, you have some negotiating room — but opening 10–12% below asking on a move-in-ready listing will likely end the conversation. A reasonable opening on a well-maintained home is 2–4% below list with standard contingencies intact. The mistake first-timers most often make here is waiving the inspection contingency to compete — don't do it. Older construction in North Idaho means older plumbing, aging roofs, and wood-framing issues that an inspector will catch and a seller concession can address.
Step 5: Inspection, Appraisal, and Closing
Budget 10–14 days for inspection scheduling — qualified inspectors in Boundary County are limited and book out. Your lender will order an appraisal independently; if the appraisal comes in below purchase price, you'll need to renegotiate, cover the gap in cash, or walk. Closing costs in Idaho typically run 2–3% of the purchase price; budget for that cash on top of your down payment. Title companies in Bonners Ferry handle most closings locally, and the process from accepted offer to keys typically takes 30–45 days.
How Much Home Can You Afford in Bonners Ferry
The table below shows estimated cash requirements at closing for several realistic Bonners Ferry purchase scenarios. Closing cost estimates are ranges (typically 2–3% of purchase price in Idaho) and are approximate — your lender's Loan Estimate will give you exact figures for your specific transaction. These are estimates only; actual amounts vary by lender, loan terms, and negotiated seller concessions.
| Scenario | Purchase Price | Loan Type / Down % | Down Payment | Est. Closing Costs | Total Cash Needed |
|---|---|---|---|---|---|
| Starter fixer-upper | $260,000 | FHA / 3.5% | ~$9,100 | ~$5,200–$7,800 | ~$14,300–$16,900 |
| Starter fixer-upper | $260,000 | Conventional / 3% | ~$7,800 | ~$5,200–$7,800 | ~$13,000–$15,600 |
| Near-median home | $320,000 | FHA / 3.5% | ~$11,200 | ~$6,400–$9,600 | ~$17,600–$20,800 |
| Near-median home | $320,000 | USDA Direct / 0% | $0 | ~$6,400–$9,600 | ~$6,400–$9,600 |
| At-median / move-in ready | $360,000 | FHA / 3.5% | ~$12,600 | ~$7,200–$10,800 | ~$19,800–$23,400 |
| At-median / move-in ready | $360,000 | Conventional / 3% | ~$10,800 | ~$7,200–$10,800 | ~$18,000–$21,600 |
| Above median / acreage | $430,000 | Conventional / 5% | ~$21,500 | ~$8,600–$12,900 | ~$30,100–$34,400 |
The USDA Direct scenario illustrates why income-eligible buyers should explore that program first — closing costs become the only cash hurdle, and at Bonners Ferry's price points, that's a manageable target even on a tight savings timeline. Boundary County's effective property tax rate of approximately 0.32% keeps annual tax bills notably low compared to most Idaho markets, which helps with monthly cash flow once you're in the home.
Looking to buy in Bonners Ferry? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Bonners Ferry quote.
Common First-Time Buyer Mistakes in Bonners Ferry
Mistake 1: Shopping Before You Have a Pre-Approval Letter in Hand
In a market with limited inventory, this is the single most expensive habit a first-timer can have. You find a house that checks every box, you call an agent, and you learn another buyer submitted an offer with a pre-approval letter yesterday. The Bonners Ferry market doesn't move at big-city speed — but it moves fast enough that touring without pre-approval is how you lose houses to buyers who did their homework first.
Mistake 2: Waiving the Inspection to Win a Multiple-Offer Situation
Some buyers, feeling pressure after losing a house or two, decide to drop the inspection contingency to make their offer more attractive. In a market built largely on older single-family construction, this is a serious financial risk. A roof replacement in North Idaho, or remediation for the kind of moisture issues that come with a wet climate near the Kootenai River, can run well into five figures. Keep your inspection contingency.
Mistake 3: Underbudgeting the Cash You Need at Closing
First-timers often laser-focus on the down payment and forget that closing costs in Idaho typically add another 2–3% of the purchase price on top. On a $360,000 home, that's roughly $7,200–$10,800 in additional cash due at closing — title fees, lender origination, prepaid homeowners insurance, and escrow reserves. Showing up to closing short on cash is not a recoverable situation. Build the full cash-needed figure — down payment plus closing costs — into your savings goal from day one.
Mistake 4: Not Factoring Distance Into Your Location Decision
Bonners Ferry's surrounding valley offers appealing rural properties, and the prices on land with a manufactured home or an older farmhouse can look very attractive compared to in-town options. What buyers sometimes underestimate is how much distance from the town center affects daily life — grocery runs, errands, and winter road conditions all compound when you're several miles out. Think through your realistic daily routine before choosing a property primarily for its price or acreage.
Local Expert Takeaway: Bonners Ferry's $360,000 median puts homeownership within reach for buyers who prepare carefully — but the combination of thin inventory (essentially all single-family, no condos or townhomes), an older housing stock that demands a real inspection, and closing cash requirements that regularly surprise first-timers means the process punishes improvisation. Get fully pre-approved before you tour. Keep your inspection contingency. And if your household income is at or below the local median, ask a lender specifically about USDA Direct eligibility before assuming FHA is your only low-down-payment option — at Bonners Ferry's price points, the difference in upfront cash between those two programs can be the difference between buying this year and buying in three years.
Quick Takeaways & FAQs
✅ Bonners Ferry's $360,000 median sale price and 0.32% effective property tax rate make it one of the more accessible entry points in North Idaho for first-time buyers on a real budget.
⚠️ Inventory is almost entirely single-family homes — no condos, no townhomes — so competition for move-in-ready listings at the median is real, and buyers without a pre-approval letter in hand regularly lose houses.
📍 Bonners Ferry qualifies as a USDA rural area, meaning income-eligible first-timers may qualify for a no-down-payment loan option at a rate of 5.250% (as of August 1, 2026) — a program many buyers here overlook entirely.
What credit score do I need to buy a home in Bonners Ferry?
How long does it take to close on a home in Bonners Ferry?
Are there condos or townhomes available for first-time buyers in Bonners Ferry?
Does Bonners Ferry qualify for USDA home loans?
How much cash do I realistically need to buy a home in Bonners Ferry?
Moving to Idaho?
Tell us what you need help with and we'll connect you with local resources.
