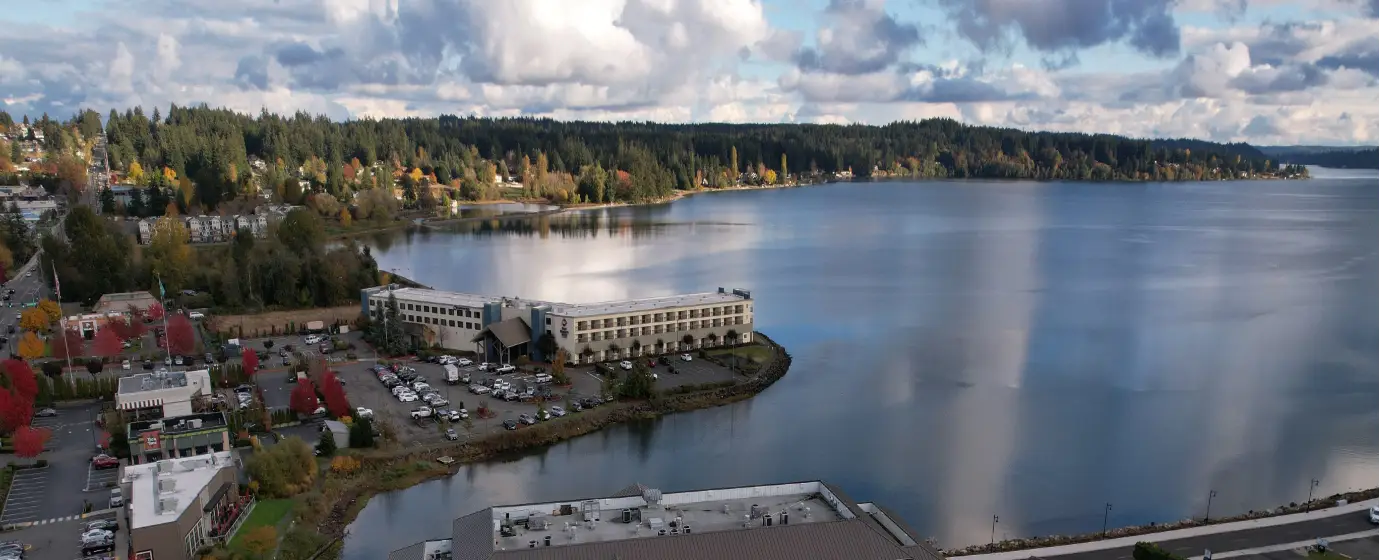
Maybe you've been renting in Kitsap County and watching prices climb, or maybe you're relocating from somewhere east of the Cascades and Silverdale just landed on your shortlist. Either way, you've probably asked the same question: can a first-time buyer actually get into this market without a decade of savings? The honest answer is yes — but only if you understand what the numbers actually mean here. Silverdale sits at the commercial core of Kitsap County, positioned along Highway 3 and a short drive from the Bremerton and Kingston ferry terminals that connect peninsula life to Seattle careers. Daily life here orbits Kitsap Mall, the Clear Creek Trail corridor, and the waterfront at Old Town Silverdale — not the pastoral quiet of Poulsbo or the urban density of Bremerton, but something in between.
The buyer pool in Silverdale is genuinely competitive in a way that surprises people coming from slower markets. Naval Base Kitsap and Puget Sound Naval Shipyard anchor the local economy, and military families — many of them veteran buyers with financing advantages — are a consistent presence in the buyer pool. Olympic College gives the city a year-round institutional steadiness that keeps demand from evaporating between PCS cycles. First-timers compete against move-up buyers, investors, and relocation buyers from the Seattle metro who've been priced out of King County. Understanding that competition is the first step to navigating it well.
Silverdale's cost of living runs noticeably above the national average — Kitsap County as a whole sits roughly 16% higher. For buyers who qualify, ownership can pencil out more favorably than renting in many scenarios, particularly given Washington's lack of a state income tax. The entry point isn't low, but the market has meaningfully slowed from its 2021 frenzy — homes now spend closer to 45–60 days on market rather than disappearing in days — which gives first-timers more breathing room than the last few years allowed.
Whether you're serious about buying in the next 90 days or still researching from out of state, the sections below walk through what your budget actually buys here, the step-by-step process in this specific market, an honest affordability snapshot, and the mistakes that cost Silverdale first-timers the most.
The Silverdale First-Time Buyer Reality
The Zillow Home Value Index for Silverdale sits at $609,559 as of May 2026 — up 1.7% over the prior year. For a first-timer, that number sets the floor of expectation, not the ceiling of possibility. See the full cost-of-living breakdown for context on how that median fits into everyday expenses here.
At that price point, roughly 3.5% down (the FHA minimum) means coming to the table with just over $21,000 in down payment alone — before closing costs, which typically add another 2%–5% of the purchase price in Kitsap County, covering inspection, appraisal, title, and escrow fees. The all-in cash requirement catches many first-timers off guard: on a $610,000 purchase, you're realistically budgeting $33,000–$52,000 total before you turn a key.
What does that buy? Entry-level inventory in Silverdale trends toward older ranch-style homes and smaller condominiums or townhomes nearer to the commercial corridor. With approximately 67 homes actively listed as of June 2026 (Northwest Multiple Listing Service data), supply is thin but not emergency-scarce. Homes are averaging around 2 offers and taking roughly 45–61 days to sell — a pace that gives you time to be methodical without being paralyzed.
The psychological shift from the 2020–2022 market is real. Sellers who bought near the peak may resist the new pace, which occasionally means overpriced listings sitting longer than they should. A first-timer with a realistic offer — not lowballing, but anchored to comparables — has more leverage today than at any point since 2019.
The Homebuying Process in Silverdale, Step by Step
Step 1: Get Pre-Approved — Before You Tour Anything
In Silverdale's market, showing up to a tour without a pre-approval letter is a liability, not just a formality. Listing agents here routinely inform sellers when an interested buyer is unfinanced, and sellers exercising multiple offers will simply skip to the pre-approved one. Get the letter first.
Several lenders maintain physical offices in Silverdale — CrossCountry Mortgage operates local branches, and Evergreen Home Loans and Fairway Independent Mortgage both have local presence. If you or a family member has military service, Navy Federal Credit Union is well-regarded among the large veteran and active-duty population here and familiar with VA loan mechanics specific to this market. Shop at least two lenders before committing.
Step 2: Define Your Search Before You Fall in Love
Silverdale's neighborhoods are genuinely distinct in character and price. Decide before your first tour whether proximity to the ferry corridors through Bremerton matters for a Seattle commute, or whether access to specific community amenities is the priority. Touring without these filters costs weeks.
Step 3: Make an Offer Grounded in Comparables
With homes averaging around 45–61 days on market, the panic-offer dynamic of 2021 is largely gone. Your agent should pull the last 90 days of closed sales in the target ZIP code via the Northwest Multiple Listing Service. Offers should be written to reflect that data — not what you hope the seller will accept.
The one contingency first-timers most often waive incorrectly here is the inspection contingency. Many Silverdale homes are 1980s–1990s construction with deferred maintenance items that an inspection surfaces. Waiving inspection to compete is a risk that tends to bite buyers 60 days after closing, not 6 months later.
Step 4: Inspection, Appraisal, and the Gap Problem
If your offer is accepted, you'll schedule a home inspection within the first few days (typically a 5–10 business day window in NWMLS contracts). Appraisals in Kitsap County can run 10–20 business days given appraiser availability on the peninsula. Plan your financing timeline accordingly — your lender should set these expectations at pre-approval.
An appraisal gap — where the appraised value comes in below the purchase price — is more likely in a market where some sellers are still pricing for 2022. Know before you write the offer whether you have cash reserves to cover a potential gap, or whether your offer should include an appraisal contingency as protection.
Step 5: Closing in Washington State
Washington is an escrow state, meaning a title/escrow company manages the closing — not an attorney. Closing typically runs 30–45 days from accepted offer. You'll do a final walkthrough within 5 days of closing to confirm the property's condition hasn't changed. Wire transfer scam attempts targeting real estate transactions are active in this region — always verify wiring instructions by phone with your escrow officer directly, not via email.
How Much Home Can You Afford in Silverdale
The table below shows five budget scenarios anchored to realistic Silverdale price points. Down payments are approximate minimums by loan type. Closing costs use the 2%–5% Kitsap County range and are shown at the midpoint (3%) for the estimate. These are estimates only — your lender will generate a Loan Estimate with your actual figures. The interactive calculator below this section handles monthly payment modeling.
| Scenario | Purchase Price | Loan Type | Down Payment | Est. Closing Costs (3%) | Total Cash Needed |
|---|---|---|---|---|---|
| FHA minimum — entry condo/townhome | ~$430,000 | FHA (3.5%) | ~$15,050 | ~$12,900 | ~$27,950 |
| Conventional low-down — entry SFR | ~$500,000 | Conventional (3%) | ~$15,000 | ~$15,000 | ~$30,000 |
| FHA — near city median | ~$560,000 | FHA (3.5%) | ~$19,600 | ~$16,800 | ~$36,400 |
| Conventional low-down — near city median | ~$610,000 | Conventional (3%) | ~$18,300 | ~$18,300 | ~$36,600 |
| Conventional 10% — mid-range SFR | ~$610,000 | Conventional (10%) | ~$61,000 | ~$18,300 | ~$79,300 |
| Conventional 20% — avoid PMI | ~$610,000 | Conventional (20%) | ~$122,000 | ~$18,300 | ~$140,300 |
One number buyers consistently underestimate: the closing cost range spans 2%–5%, and in Kitsap County — where ferry-accessible waterfront properties sometimes involve additional title complexity — landing at 4% rather than 2% is common. Budget closer to the high end and treat anything under it as a pleasant surprise.
Washington has no state income tax, which affects take-home pay calculations. The effective property tax rate in Silverdale is approximately 0.80% — a meaningful annual line item your lender will factor into your debt-to-income ratio. See the cost-of-living page for the full tax picture.
VA loans are a significant factor in this market. Active-duty and veteran buyers affiliated with Naval Base Kitsap can use VA financing with no down payment required and no private mortgage insurance, which meaningfully changes the cash-to-close equation — and makes military-affiliated buyers formidable competition for non-VA first-timers in the same price range.
Looking to buy in Silverdale? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Silverdale quote.
Common First-Time Buyer Mistakes in Silverdale
Mistake 1: Touring Before You Have a Pre-Approval Letter
This happens more often than agents like to admit. A buyer falls for a listing, books a showing, and learns at the tour that two pre-approved buyers are already circling. Without a letter in hand, you can't write an offer — and you've just spent emotional energy on a house you can't compete for. Silverdale's Northwest Multiple Listing Service listings move quickly enough that pre-approval is table stakes, not a follow-up step.
Mistake 2: Waiving the Inspection Contingency on Older Inventory
The pressure to waive inspections peaked in 2021 and hasn't fully gone away in buyers' minds, even though the market no longer demands it. Much of Silverdale's entry-level inventory — the 1,200–1,600 sq ft ranches that date to the 1980s and 1990s — frequently surfaces moisture intrusion, older electrical panels, and aging roofs on inspection. A standard NWMLS inspection contingency gives you the right to negotiate repairs or walk away. Surrendering that protection to shave a few days off your timeline is a risk the current market doesn't require you to take.
Mistake 3: Underbudgeting the Cash-to-Close
The down payment is the number people fixate on. The closing costs — inspection fees, appraisal, title insurance, escrow fees, prepaid property taxes, and homeowners insurance at closing — are the number that blindsides them. In Kitsap County, that range runs 2%–5% of the purchase price. On a $560,000 home at 4%, that's $22,400 in closing costs alone, separate from the down payment. Add a few thousand for moving, and the total cash-to-close is routinely $15,000–$25,000 more than buyers plan for when they first run the numbers.
Mistake 4: Ignoring the Commute Math Before Picking a Neighborhood
Silverdale attracts buyers who work in Seattle, and the ferry schedule is not forgiving of a slow drive to the Bremerton terminal. A house that looks convenient on a map can add 15–20 minutes to a morning that already involves a lengthy ferry crossing. First-timers who choose a neighborhood without running a commute simulation during rush hour regularly describe it as the thing they'd change about their purchase. Walk the Bremerton or Kingston terminal schedule before you write an offer in any neighborhood where Seattle commuting is part of your plan.
Local Expert Takeaway: Silverdale's first-time buyer window is more open than it's been since 2019 — homes are sitting 45–60 days and averaging just two offers, which means a prepared buyer with a real pre-approval and a comparables-grounded offer can compete without panic. The cash-to-close math is the hardest part: budget 3%–5% of the purchase price in closing costs on top of your down payment, get your pre-approval from a lender familiar with Kitsap County (CrossCountry Mortgage, Evergreen Home Loans, and Navy Federal all have local presence), and don't waive the inspection contingency on 1980s–1990s construction. That combination — cash-ready, pre-approved, inspection intact — is what separates buyers who close from buyers who spend six months watching listings and losing.
Quick Takeaways & FAQs
✅ Silverdale's market has meaningfully cooled from its 2021 peak — homes now average 45–61 days on market and roughly 2 offers, giving first-timers negotiating room that didn't exist three years ago.
⚠️ The biggest hidden cost isn't the down payment — closing costs in Kitsap County typically run 2%–5% of the purchase price, and first-timers routinely underestimate this by $10,000–$20,000.
📍 Military and veteran buyers using VA financing are a constant presence in this market given Naval Base Kitsap's proximity — non-VA first-timers need a tight pre-approval and inspection-contingency strategy to compete effectively.
What credit score do I need to buy a home in Silverdale, WA?
How long does it take to close on a home in Silverdale?
Is it better to buy or rent in Silverdale right now?
What are the biggest competition factors for first-time buyers in Silverdale?
Do I need 20% down to buy a home in Silverdale?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
