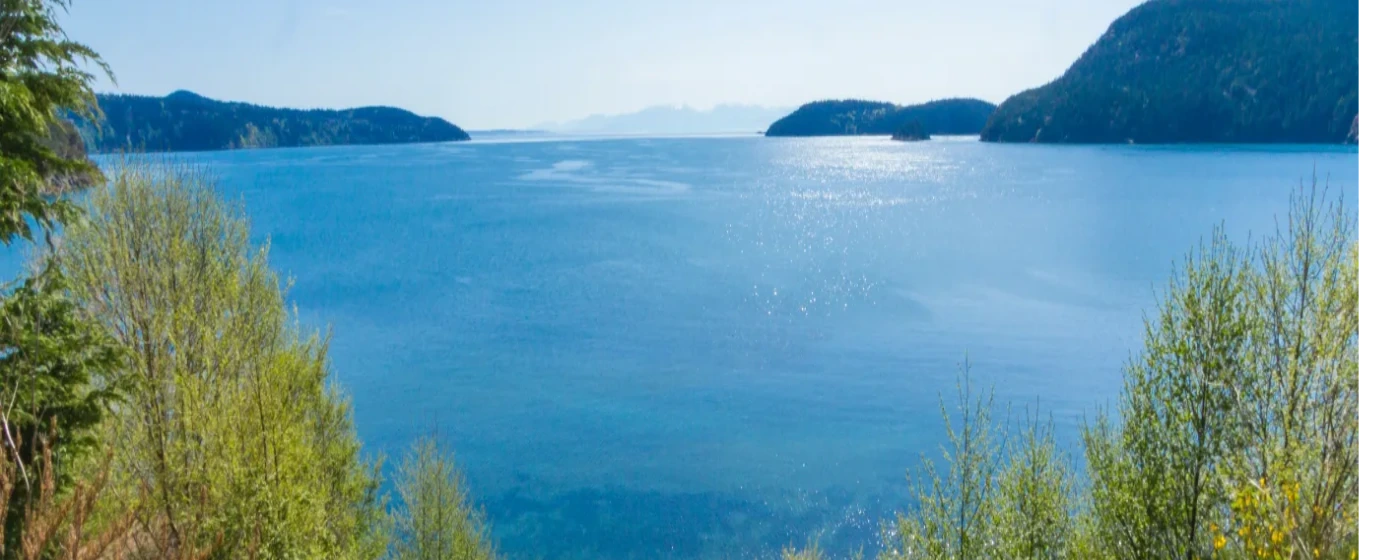
Maybe your company is relocating you here. Maybe you've been priced out of Bellingham and someone mentioned Anacortes. Either way, the first thing most first-timers say when they look up the numbers is: I didn't expect it to be this expensive for a small island town. With a Zillow Home Value Index of $690,991 (mid-2026) — see the full cost-of-living breakdown — Anacortes sits well above what its population of roughly 18,000 would suggest. The geography is the reason: this is a peninsula connected to the mainland by a single highway corridor, with ferry access to nearby island communities and a finite supply of buildable land. Prices here follow their own logic.
The market itself is more nuanced than the headline number implies. As of mid-2026, Anacortes is technically a balanced market — roughly 3 to 4 months of supply — which is a meaningful shift from the frenzied seller's conditions of recent years. Homes are selling at approximately 98.7% of list price and spending a median of 17 to 20 days on market before going pending. Well-priced homes in strong condition still attract multiple offers and can go pending in as few as four days. First-timers without a prior home sale to fund their down payment face a price-to-income ratio of roughly 7.5x against the city's median household income of $91,951 — a real affordability challenge that requires careful budgeting from the start.
What makes Anacortes workable for first-time buyers is that the entry points exist, if you know where to look. Older construction and smaller footprints — particularly in neighborhoods away from the waterfront — can come in noticeably below the city-wide median. The effective property tax rate of approximately 0.79% is among the more manageable in the Puget Sound region, and there is no Washington state income tax, which affects how far a paycheck stretches toward a mortgage. The trade-off is that inventory is thin in absolute terms — roughly 151 active listings as of June 2026 — so when an entry-level home hits the market, it moves quickly.
This guide covers the realistic budget picture for first-timers in Anacortes, the step-by-step buying process as it actually plays out here, a scenario-based affordability snapshot, and the specific mistakes that cost first-time buyers deals in this market.
The Anacortes First-Time Buyer Reality
The Zillow Home Value Index for Anacortes sits at $690,991 (mid-2026) — and that figure is the average, not the floor. Entry-level inventory does exist, but it typically means older construction, a smaller lot, or a location away from the water and Cap Sante Park views that push prices higher. Buyers willing to look beyond Old Town or Anaco Beach will find more room to negotiate and less competition per listing.
The market has cooled from its 2022 peak, but "balanced" doesn't mean easy. Anacortes is a lower-volume market — fewer than 200 active listings at any given time — which means a single good property can still draw a crowd. Month-to-month price swings here can look dramatic; year-over-year and trailing-average figures give a more reliable read than any single week's data. Budget based on trends, not on an outlier sale you saw on Zillow.
August through December is historically the better window to buy. Seller urgency tends to rise, spring-peak competition fades, and you are less likely to find yourself in a seven-offer situation on a three-bedroom in Old Town. If your timeline is flexible, patience has measurable value in this specific market.
The Homebuying Process in Anacortes, Step by Step
Step 1 — Get Pre-Approved Before You Tour Anything
In Anacortes, attending an open house without a pre-approval letter is not just premature — it's a liability. Many homes here receive multiple offers, some with waived contingencies, and listing agents will flag unrepresented buyers without financing documentation as low-priority. Guild Mortgage has a branch on Commercial Avenue in Anacortes; CrossCountry Mortgage also maintains a local presence. A local lender who knows NWMLS norms can make your offer read as more credible than an out-of-area letter from an online lender.
Step 2 — Find a Buyer's Agent Who Knows This Market
Not every agent who works Skagit County works Anacortes regularly. The ferry access, the island-adjacent pricing psychology, and the specific school boundary quirks within the local district are things a frequent local agent will flag that a generalist may miss. Ask how many Anacortes transactions they closed in the past 12 months, not how many years they've held a license.
Step 3 — Make Competitive Offers, Thoughtfully
Homes here sell at approximately 98.7% of list price on average, which sounds close to asking — but the range matters. A well-staged Old Town bungalow may land at 102% of list; a March Point-area home with deferred maintenance may sit for 30 days and accept 95%. Your agent's comparable sales analysis is the tool, not the list price itself.
The contingency question is where first-timers most often make their first mistake. In a multiple-offer situation, some buyers waive inspection contingencies to compete. Do not waive inspection on an older Anacortes home without fully understanding what you're giving up. Marine air and the island's humidity mean moisture intrusion, wood rot, and aging roofs are common inspection findings here — issues that cost real money. An escalation clause or a larger earnest money deposit are better competitive tools than dropping your inspection rights.
Step 4 — Inspection and Appraisal
Schedule your inspection immediately after mutual acceptance — inspectors in smaller markets like Anacortes book up faster than buyers expect. Budget for a general inspection plus a separate sewer scope on any home built before 1980; older plumbing is common in Old Town and parts of Similk Beach. If your loan requires an appraisal, note that the appraiser will use comparable sales across a relatively thin data pool — in a lower-volume market, an appraisal gap is a real possibility if you bid aggressively.
Step 5 — Closing
Washington is an escrow state, and most Anacortes transactions close through a local title-and-escrow company in Skagit County. Closing typically takes 30 to 45 days from mutual acceptance. Your final walk-through happens 24 to 48 hours before closing — use it, especially to check for any deferred maintenance items the seller agreed to address.
How Much Home Can You Afford in Anacortes
The table below is a planning tool, not a commitment. Closing costs are estimated at 2–3% of the purchase price and vary by lender, loan type, and negotiated seller credits. Down payment amounts reflect the loan program's minimum requirement — most buyers put down more if they can, to lower the monthly payment and avoid private mortgage insurance on conventional loans.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5% down) — entry-level | $500,000 | $17,500 (3.5%) | $10,000–$15,000 | ~$27,500–$32,500 |
| Conventional (3% down) — entry-level | $500,000 | $15,000 (3%) | $10,000–$15,000 | ~$25,000–$30,000 |
| FHA (3.5% down) — near median | $600,000 | $21,000 (3.5%) | $12,000–$18,000 | ~$33,000–$39,000 |
| Conventional (5% down) — near median | $650,000 | $32,500 (5%) | $13,000–$19,500 | ~$45,500–$52,000 |
| Conventional (10% down) — at median | $691,000 | $69,100 (10%) | $13,800–$20,700 | ~$82,900–$89,800 |
| Conventional (20% down) — at median | $691,000 | $138,200 (20%) | $13,800–$20,700 | ~$152,000–$158,900 |
The 20% scenario eliminates private mortgage insurance, which meaningfully affects your monthly carrying cost — use the mortgage calculator below to model the payment difference between the 10% and 20% scenarios at your target price.
One figure first-timers often underestimate: Washington's 0.79% effective property tax rate means roughly $5,459 annually on a home at the city-wide median — factor that into your affordability ceiling before, not after, you fall in love with a listing.
Looking to buy in Anacortes? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Anacortes quote.
Common First-Time Buyer Mistakes in Anacortes
Touring Without a Pre-Approval Letter
This is the most common and most costly mistake in this market. A desirable three-bedroom in Old Town or near Washington Park can go pending in four days. If you are still waiting on bank statements when mutual acceptance happens, you are already out. Get fully underwritten pre-approval — not just a pre-qualification letter — before you attend a single showing.
Waiving the Inspection to Win a Bidding War
Anacortes homes — especially anything built before 1990 in Old Town or Similk Beach — carry real inspection risk. Marine moisture, aging roofs, and older sewer laterals are not hypotheticals here; they show up on inspection reports regularly. Buyers who waive inspection to compete and then discover a failing sewer line or significant wood rot have no legal recourse. Offer an escalation clause or increase your earnest money instead. There is almost always a smarter way to compete.
Ignoring the Seasonal Buying Window
First-timers who arrive in Anacortes during the spring peak — March through June — face the sharpest competition and the tightest inventory. Buyers who wait until August or later historically find more listings, fewer competing offers, and sellers who have already reduced once. If your job start date or lease expiration gives you flexibility, timing your search toward the fall window is one of the few free advantages available in this market.
Underestimating Total Cash to Close
The down payment is only part of the cash required. Add closing costs (typically 2–3% of the purchase price), prepaid homeowners insurance, prepaid property taxes held in escrow, and any earnest money not already counted. On a $600,000 purchase with 5% down, buyers are routinely surprised to find they need $55,000 or more in liquid funds at closing — not $30,000. Run the full number before you make an offer, not after. A local lender at Guild Mortgage's Commercial Avenue branch or CrossCountry Mortgage's local office can produce a Loan Estimate that breaks this down to the dollar for your specific scenario.
Local Expert Takeaway: Anacortes is not a market where first-timers can afford to move slowly or show up underprepared. Pre-approval in hand, a local buyer's agent who closes deals in this market regularly, and a realistic cash-to-close figure are the three things that separate buyers who land a home from buyers who spend six months losing offers. The entry points exist — older construction away from the Old Town waterfront, smaller footprints in less competitive pockets — but they move fast. Time your search toward August through December if you can, skip the inspection waiver no matter how tempted you are, and treat the $690,991 city-wide median as a midpoint rather than a ceiling.
Quick Takeaways & FAQs
✅ Anacortes's 0.79% effective property tax rate is among the more manageable in the North Puget Sound region, and Washington's lack of a state income tax meaningfully stretches buyer purchasing power.
⚠️ With roughly 151 active listings at any given time and a median of 17–20 days on market, Anacortes inventory moves fast — first-timers who tour without a pre-approval letter routinely miss the homes they wanted.
📍 The best buying window in Anacortes is historically August through December, when spring-peak competition fades and sellers are more likely to negotiate on price or terms.
What is the minimum down payment to buy a home in Anacortes, WA?
Is Anacortes a buyer's market or seller's market right now?
What credit score do I need to buy a home in Anacortes?
How long does it take to close on a home in Anacortes?
Are there entry-level homes available in Anacortes for first-time buyers?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
