Maybe your company is relocating you here. Maybe you've priced out a mortgage in San Antonio and someone mentioned Gonzales as a legitimate alternative. Either way, the first thing that surprises people is how far a modest down payment actually goes in a market where the typical home sits well under $300,000. The catch — and there is always one — is that Gonzales is a small city of 7,239 people about 65 minutes to San Antonio, which means your commute math and your lifestyle expectations need to be calibrated honestly before you make an offer.
The city's economic backbone is more diversified than its size suggests. Gonzales Independent School District, Gonzales Healthcare Systems, Kitchen Pride Mushroom Farms, and Adams Extract & Spice together cover education, healthcare, and food manufacturing — a mix that has kept the local economy stable without depending on a single sector. The school district holds a C rating, according to the Texas Education Agency, with 2,516 students enrolled in 2025-26, which is worth understanding if school quality is a deciding factor for your family. See the full picture on the Gonzales schools page.
Texas property taxes run higher than the national average, and Gonzales is no exception. The effective property tax rate here is 1.52% — above the national median but manageable at local price points. The bigger budget reality is that Texas has no state income tax, so the property tax line carries more weight than it does in most states. Texas voters also approved a significant school-district homestead exemption increase in late 2025, which provides meaningful annual savings for primary-residence owners starting in 2026. The full cost-of-living picture, including utilities and groceries, lives on the cost-of-living page.
Whether you're buying your first home in Gonzales or seriously weighing the move, the sections below walk through what your budget realistically buys here, the step-by-step purchase process, an honest affordability snapshot, and the specific mistakes that trip up first-time buyers in this market.
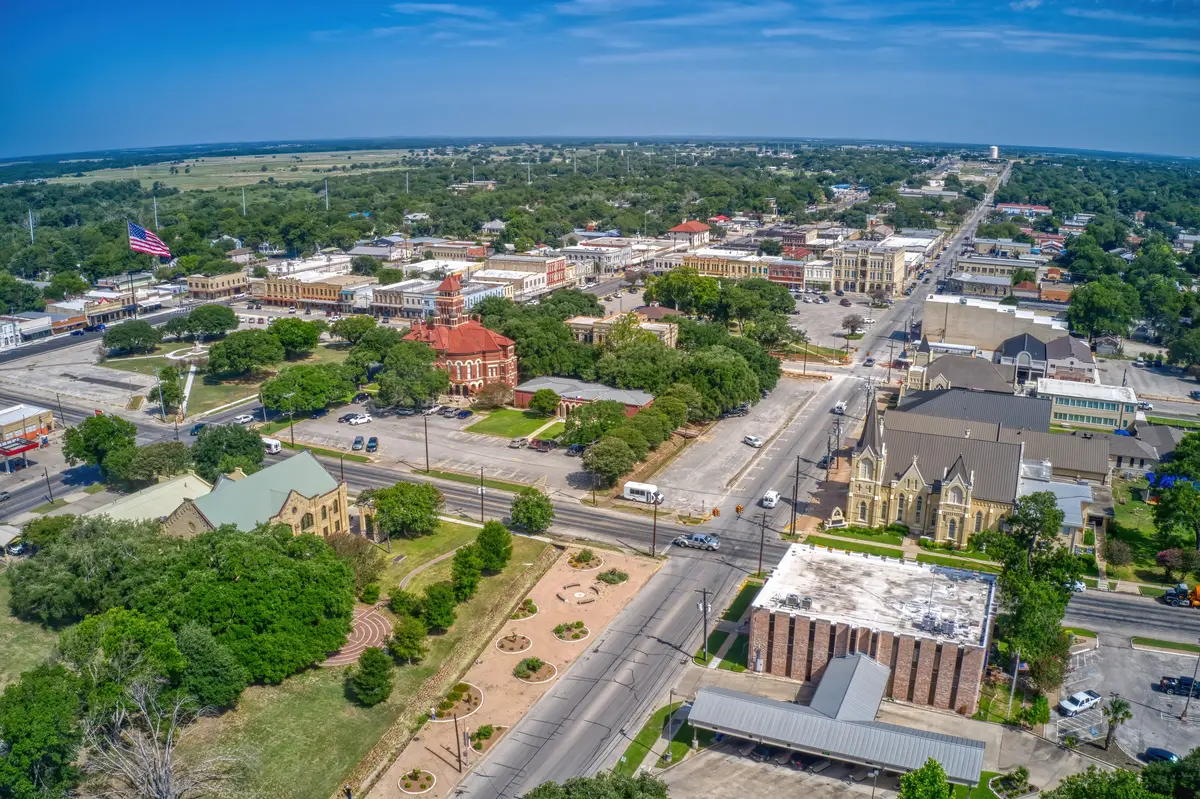
The Gonzales First-Time Buyer Reality
The typical home in Gonzales is priced at $249,933 (Zillow Home Value Index, July 2026). That figure puts entry-level homeownership within reach for buyers who could never crack a market like Austin or San Antonio — but it comes with a clear-eyed trade-off: you are buying into a small, rural-adjacent city where most services and major employers require a drive.
At that price point, a 3.5% FHA down payment is roughly $8,750, and a conventional 3% down puts you at around $7,500. Those are real numbers that a working household can save toward, which is exactly why Gonzales draws buyers who have been priced out of larger metros. It is also worth knowing that the median household income in Gonzales — $51,929 — falls somewhat short of what is typically needed to carry the city's median home price at current interest rates, so getting your budget stress-tested by a lender before you start touring is not optional here, it is essential.
The broader Texas market has shifted toward buyers in recent years, with statewide inventory climbing and sellers more willing to negotiate. In a market the size of Gonzales, that dynamic is amplified: a pre-approved buyer with clean financials can often negotiate meaningfully on price or seller concessions, particularly on homes that have sat a while. The inventory here is thinner than in San Antonio — you may see fewer listings in any given week — but the competition for any single home is also generally lower. Understanding that tension is the starting point for any first-time buyer in this market.
The Homebuying Process in Gonzales, Step by Step
Step 1 — Get Pre-Approved Before You Tour
This is the step first-time buyers most consistently skip, and it costs them the most. In a market with limited inventory, a home that fits your budget can appear and go under contract in days. Showing up to a showing without a pre-approval letter is the fastest way to lose a home you wanted — sellers in Gonzales are not obligated to wait while you start the lending process.
Pre-approval is not the same as pre-qualification. A pre-qualification is an estimate based on what you tell the lender. A pre-approval means the lender has pulled your credit, verified income, and issued a conditional commitment. Bring that letter to every showing.
Step 2 — Find a Local Agent Who Knows the Neighborhoods
Gonzales has distinct neighborhoods — Historic Downtown, Creekwood, Rivercrest, High Ridge Meadows, Whispering Oaks, and others — and the differences in flood zone exposure, road maintenance, and school boundaries matter more than a first-timer typically expects. An agent with active Gonzales experience is not a luxury here; they are the person who tells you which streets hold water after a heavy rain and which subdivisions carry older infrastructure that shows up in inspection reports.
Step 3 — Make an Offer with the Right Contingencies
In the current Texas market, with roughly 22% of homes having seen price reductions statewide, you generally have room to negotiate — but do not let that room talk you into waiving contingencies you actually need. An inspection contingency and a financing contingency are not negotiating chips; they are the backstops that protect you if the house has a problem or your loan terms shift before closing.
The one contingency first-timers in Gonzales most often mishandle is the option period. Texas uses an option period — typically a set number of days after an executed contract — during which you pay a relatively small fee for the unrestricted right to walk away. Use that window to complete your inspection. Do not treat it as a formality.
Step 4 — Inspection and Appraisal
The inspection tells you what the house actually is. The appraisal tells the lender what the house is worth. They are separate processes that often happen in the same week, and first-time buyers sometimes conflate them. If the appraisal comes in below the purchase price, you have a decision to make: renegotiate, make up the gap in cash, or walk. Know your plan before that scenario arises.
In older neighborhoods like Historic Downtown Gonzales, inspections frequently surface deferred maintenance on roofing, plumbing, and HVAC systems. Budget time and energy to read the inspection report carefully — and budget cash for what it finds, separate from your down payment and closing costs.
Step 5 — Closing
Texas closings are handled through a title company, not an attorney. Closing typically runs two to four weeks after an executed contract, though it can stretch with appraisal scheduling. One Texas-specific step that trips up first-time buyers: filing your homestead exemption. You must file it separately with the county appraisal district after closing. Once it is on file, your taxable appraised value generally cannot increase more than 10% per year — a meaningful long-term budget protection that does not kick in automatically.
The expanded school-district homestead exemption — now $140,000 of your home's taxable value shielded from school-district taxes after a November 2025 ballot measure — can save primary-residence owners roughly $350 to $500 annually. If you escrow taxes with your lender, that savings may not show up in your monthly payment until the following year, when the lender reanalyzes the escrow account. Ask your loan officer about the timing so you are not caught off guard by an adjustment.
How Much Home Can You Afford in Gonzales
The table below gives you a rough sense of what cash you need at the closing table at several realistic price points. Closing costs in Texas typically run 2% to 4% of the purchase price and include title insurance, lender fees, prepaid property taxes, and prepaid homeowners insurance. These are estimates — your lender will give you a Loan Estimate within three business days of application that itemizes the actual figures for your transaction.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–4%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — entry level | $180,000 | $6,300 (3.5%) | $3,600–$7,200 | ~$10,000–$13,500 |
| Conventional (3%) — entry level | $180,000 | $5,400 (3%) | $3,600–$7,200 | ~$9,000–$12,600 |
| FHA (3.5%) — near city median | $249,933 | $8,747 (3.5%) | $5,000–$10,000 | ~$13,750–$18,750 |
| Conventional (3%) — near city median | $249,933 | $7,498 (3%) | $5,000–$10,000 | ~$12,500–$17,500 |
| Conventional (5%) — mid-range | $275,000 | $13,750 (5%) | $5,500–$11,000 | ~$19,250–$24,750 |
| Conventional (10%) — upper range | $325,000 | $32,500 (10%) | $6,500–$13,000 | ~$39,000–$45,500 |
These figures cover the purchase itself — they do not include moving costs, immediate repairs, or reserves. Texas also has no mortgage recording tax, which keeps one line off the closing disclosure that buyers from some other states expect to see.
One number to keep visible throughout your budgeting: the effective property tax rate of 1.52%. At a $250,000 purchase price, that adds up to meaningful monthly costs that the mortgage calculator on this page can model at current rates. Property taxes and homeowners insurance together can add substantially to a base principal-and-interest payment, which is exactly why comparing a Texas mortgage payment to what you might have paid in a lower-tax state requires more than a simple rate comparison. Build both into your monthly budget from day one.
Looking to buy in Gonzales? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Gonzales quote.
Common First-Time Buyer Mistakes in Gonzales
Shopping Before You Have a Pre-Approval Letter
Gonzales has a limited number of homes on the market at any given time. Falling in love with a house before you know what a lender will actually approve you for is not just frustrating — it can cost you the home entirely. Start with the lender, then start the search.
Underbudgeting the Total Cash Needed
First-time buyers consistently fixate on the down payment number and forget that closing costs in Texas run 2% to 4% of the purchase price on top of it. At $249,933, that is an additional $5,000 to $10,000 in cash you need to show up with. Factor in a post-closing reserve for repairs and the picture becomes even clearer: the total cash-to-close is nearly always higher than the down payment alone suggests.
Waiving the Inspection to Win the Offer
In neighborhoods like Historic Downtown Gonzales, where older housing stock is common, a waived inspection is a significant financial risk. Roofing systems, foundation drainage, and aging HVAC equipment are all normal findings in older homes — and none of them are cheap. The inspection does not have to kill the deal; it gives you information to negotiate with. Waiving it outright removes that protection entirely.
Ignoring the Commute Reality
Gonzales is about 65 minutes to San Antonio. That is not a commute most people would describe as easy on a daily basis. First-time buyers who purchase here while employed in San Antonio sometimes find — around month six — that the drive wears on them more than they expected. If your job is in the city and remote work is not guaranteed, run an honest numbers comparison between commuting costs and the higher home prices closer in before you commit to the distance. The living in Gonzales page breaks down what daily life and the commute actually look like.
Missing the Homestead Exemption Filing Deadline
Texas does not file your homestead exemption for you. After closing, you must submit the application to the Gonzales County Appraisal District to receive the school-district exemption — now $140,000 of taxable value — and the 10% annual appraisal cap on your primary residence. Buyers who miss the filing window lose that protection for the first tax year. Ask your title company or agent on closing day exactly when and where to file, and do it within the first month of ownership.
Local Expert Takeaway: Gonzales is one of the few places in the San Antonio metro orbit where a first-time buyer with moderate savings can realistically put 3% to 5% down and close on a house without depleting everything they have. The trade-off is real: you're about 65 minutes to San Antonio, the school district holds a C rating from the Texas Education Agency, and your total monthly costs will be higher than the purchase price suggests once you account for a 1.52% effective property tax rate. File your homestead exemption immediately after closing — that single step caps your annual appraisal increase at 10% and shields $140,000 of taxable value from school-district taxes under the 2025 expansion. Get pre-approved before you tour, keep your inspection contingency, and use the Texas option period for what it's designed for: a real inspection, not a handshake.
Quick Takeaways & FAQs
✅ The typical Gonzales home at $249,933 (July 2026) puts FHA financing within reach for buyers who have saved $10,000 to $14,000 in total cash — a realistic threshold that larger nearby markets have made nearly impossible.
⚠️ The commute is the honest downside: about 65 minutes to San Antonio means Gonzales works best for remote workers, local employees, or buyers who have genuinely accepted what that drive means five days a week.
📍 File your Texas homestead exemption with the Gonzales County Appraisal District immediately after closing — it is not automatic, and missing the window costs you meaningful tax savings in your first year of ownership.
What is the typical home price for a first-time buyer in Gonzales, TX?
Is FHA or conventional financing better for buying in Gonzales?
How much cash do I actually need to buy a home in Gonzales?
What is the homestead exemption in Texas and how does it affect Gonzales buyers?
Is it a good time to buy a home in Gonzales as a first-timer?
Moving to Texas?
Tell us what you need help with and we'll connect you with local resources.
