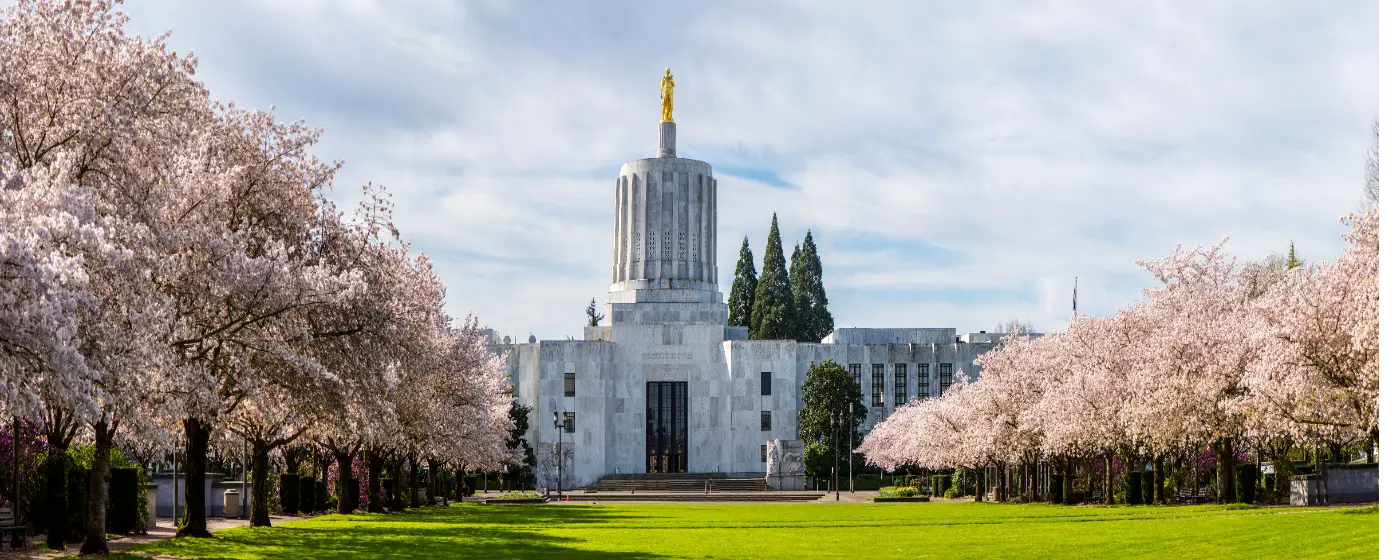
You've probably run the numbers and noticed that Salem looks like a realistic path into Oregon homeownership when Portland increasingly does not. That read is correct — but the gap between "more affordable than Portland" and "easy to buy here" is wider than a spreadsheet suggests. Salem's typical home price sat at $440,726 as of July 2026, and the median household income falls short of what's needed to comfortably carry that purchase by roughly $37,000. That gap is the central financial reality every first-timer here has to plan around, and this guide starts there rather than burying it.
Salem is Oregon's state capital and the 2nd-largest incorporated city in the state, with a population of 178,865 anchored by some of the most recession-resistant employers in the region. The State of Oregon, Salem-Keizer Public Schools, Salem Health, Marion County, and the City of Salem itself collectively form a job base that keeps housing demand steady even when the broader Oregon economy softens. That stability is good for the market's long-term health, but it also means demand for entry-level housing doesn't evaporate — prepared buyers have more room to negotiate than in recent years, but this is not a market where good homes sit untouched for months.
Cost of living runs meaningfully below Portland and noticeably below the national coasts, and the lifestyle trade-off is less dramatic than people expect. Minto-Brown Island Park, Bush's Pasture Park, and the Willamette River Greenway give the city a genuine outdoors texture. The Salem-Keizer School District holds a B- rating, according to Niche, serving 36,837 students enrolled in 2025-26 — a relevant factor for families buying with school boundaries in mind. For a full breakdown of taxes, rents, and cost comparisons, see the cost of living in Salem page.
Whether you're a state employee relocating to the capital, a Portland renter finally making the move south, or someone who just discovered Salem on a price-per-square-foot search, the sections below break down what a first-timer's budget actually buys here, how the buying process works locally, what the numbers look like at the closing table, and the specific mistakes that trip up buyers who didn't grow up in this market.
The Salem First-Time Buyer Reality
Salem is one of the more accessible entry points for first-time buyers in the Pacific Northwest — but accessible is relative. With a typical home price of $440,726 (Zillow Home Value Index, July 2026), the entry point sits well below Portland but above what the city's median household income can comfortably carry on its own. That means most first-timers here are stretching, and the honest plan accounts for that stretch upfront rather than discovering it at the lender's office.
What that price actually buys depends heavily on the neighborhood. Areas priced below the city median — including the Grant neighborhood near the Capitol Mall, with its tree-lined streets and older craftsman homes — give buyers the most square footage per dollar and are realistic targets on tighter budgets. Neighborhoods priced at or near the median, like Faye Wright and Morningside, offer more updated stock and are where most first-timer searches land. Areas priced above the median, like West Salem, push buyers into territory that requires a larger down payment or a dual income to be comfortable. See the full neighborhood breakdown on the best neighborhoods in Salem page.
One geographic detail that surprises first-timers: West Salem sits entirely in Polk County, separated from the rest of the city by the Willamette River and accessed by two main bridges. If your job is in downtown Salem or near the Oregon State Capitol, factor peak-hour bridge traffic into that decision — it is a real daily variable, not a minor inconvenience. Well-priced homes in desirable areas still attract attention quickly, while homes needing significant work or carrying above-market asking prices are giving buyers more room to negotiate on repairs and terms.
The Homebuying Process in Salem, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
This is where most Salem first-timers go wrong. The Willamette Valley market is not so frenzied that a seller will take your call-back the next morning after a walkthrough — but it is tight enough at entry-level prices that arriving without pre-approval means you cannot make an offer when a good home appears. Pre-approval tells you exactly what you're qualified for, which matters more here than in a slower market because the gap between what buyers want and what they can finance is often narrower than expected.
For conventional loans, most lenders require a minimum 620 credit score, but a score of 680 or above meaningfully improves your rate options. FHA loans accept scores as low as 580 with 3.5% down — but understand that FHA mortgage insurance stays on the loan for its full term unless you later refinance into a conventional product. Pull your credit report before you talk to a lender, not after.
Step 2: Shop with a Local Agent Who Knows Neighborhood Boundaries
Salem's school boundaries and neighborhood character shift in ways that aren't obvious from a map. The Grant neighborhood and South Central have older housing stock that requires a sharper inspection eye. Faye Wright's Woodmansee Park — a 30-acre park with walking trails, tennis courts, a disc golf course, and a soccer field — drives demand in that pocket. An agent who works Salem specifically will know which blocks are in which school feeder zones and which pockets of Southeast Mill Creek or South Salem are seeing the most first-timer activity.
Step 3: Make an Offer with the Right Contingencies
Oregon is an attorney-optional state — most transactions close through title companies and escrow, and buyers are generally represented by their agent, not an attorney. Your offer should include an inspection contingency and a financing contingency. In a market where well-priced homes move quickly, waiving either contingency to compete on a modest starter home is rarely worth the risk; sellers of well-maintained homes in this price range are not routinely demanding contingency waivers the way Portland sellers were in 2021.
Step 4: Inspection, Radon, and Appraisal
A general home inspection is a must. In the Willamette Valley, radon testing is also strongly recommended — radon levels in this region frequently exceed EPA guidelines, and it's an inexpensive add-on that buyers often skip and later regret. The appraisal comes after the inspection, ordered by your lender to confirm the home's value supports the loan amount.
Step 5: Closing
Oregon closing costs typically run 2%–5% of the purchase price, covering lender fees, appraisal, title insurance, and prepaid items like the first year of homeowners insurance and property tax reserves. Budget toward the higher end of that range as a first-timer — prepaid reserves in particular catch people off guard. Oregon's property tax system caps assessed value increases at 3% per year by law, but voters can approve additional levies that push the effective bill above that cap. Marion County properties within Salem saw an average property tax increase of about 8% for the 2025-26 tax year following voter-approved levies. The effective rate is approximately 0.79%, but confirm the current levies on the specific property — it varies by district.
How Much Home Can You Afford in Salem
The table below shows estimated cash needed at the closing table across realistic purchase price scenarios for Salem first-timers. Closing costs are estimated at 2%–3% for these scenarios — a reasonable planning range, though your actual figures depend on your lender, the property, and which prepaid items apply to your loan. The interactive mortgage calculator below the table will let you model monthly payments at current rates once you've identified your target price range.
| Scenario | Purchase Price | Loan Type | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|---|
| Entry-level, Grant or South Central | ~$350,000 | FHA (3.5%) | ~$12,250 | ~$7,000–$10,500 | ~$19,250–$22,750 |
| Entry-level, Grant or South Central | ~$350,000 | Conventional (3%) | ~$10,500 | ~$7,000–$10,500 | ~$17,500–$21,000 |
| At city median | ~$440,000 | FHA (3.5%) | ~$15,400 | ~$8,800–$13,200 | ~$24,200–$28,600 |
| At city median | ~$440,000 | Conventional (3%) | ~$13,200 | ~$8,800–$13,200 | ~$22,000–$26,400 |
| Mid-range, Faye Wright or Morningside | ~$490,000 | Conventional (5%) | ~$24,500 | ~$9,800–$14,700 | ~$34,300–$39,200 |
| Above median, West Salem | ~$530,000 | Conventional (10%) | ~$53,000 | ~$10,600–$15,900 | ~$63,600–$68,900 |
These figures are planning estimates, not lender quotes. Cash needed at table does not include moving costs, immediate repairs, or any post-closing reserves your lender may require — budget an additional buffer for each. A score of 680 or above on a conventional loan typically unlocks meaningfully better pricing than a score just above the 620 minimum.
Looking to buy in Salem? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Salem quote.
Common First-Time Buyer Mistakes in Salem
Touring Homes Before You Have Pre-Approval
Salem's entry-level bracket — the $350,000–$420,000 range where first-timers are most active — does not wait for buyers who are still sorting out financing. Agents who regularly work this market will not prioritize a buyer who can't make a same-day offer, and sellers of well-priced homes aren't going to hold for you. Get a pre-approval letter in hand before you set foot in a house you'd actually buy.
Waiving the Inspection Contingency on a Starter Home
Salem has meaningful older housing stock, particularly in the Grant neighborhood, South Central, and parts of Downtown Salem. Craftsman bungalows and mid-century ranches are appealing — and they can carry deferred maintenance, outdated electrical, or drainage issues that a thorough inspection surfaces before they become a costly post-closing surprise. Skipping or waiving that contingency to make your offer more appealing is the single riskiest move a first-timer can make in this price range. Add radon testing while you're at it — it costs very little relative to the risk in the Willamette Valley.
Ignoring the West Salem Bridge Reality
West Salem prices above the city median and draws buyers who want newer construction and Polk County's slightly different tax district. What some first-timers don't price in: West Salem is physically separated from the rest of the city by the Willamette River. Getting across during peak commute hours on the two main bridge crossings can add real time to a state government or downtown commute. If you work near the Oregon State Capitol, test that drive at 7:45 a.m. before you make an offer in West Salem, not after.
Underbudgeting the Cash You'll Need at Closing
The down payment gets all the attention, but prepaid items routinely catch first-timers short. At closing you'll pay the first year of homeowners insurance upfront, fund a tax reserve (escrow impound), and cover lender and title fees — none of which are folded into the loan. On a $440,000 purchase, that can push total cash at table to $24,000–$29,000 even at the minimum FHA down payment. Marion County property tax levies have been rising — the 2025-26 tax year brought about an 8% increase due to voter-approved levies — so your escrow reserve estimate may be higher than older online calculators suggest. Ask your lender for an itemized Loan Estimate early and compare it to the scenarios in the table above.
Local Expert Takeaway: Salem is a genuine first-timer opportunity in a state where those have become rare — but it rewards buyers who show up prepared. The $440,726 typical home price (July 2026) is real, the income gap is real, and the cash needed at the table is larger than most first-timers expect when they add prepaids to the down payment. Run the budget snapshot table against your savings before you start touring, get pre-approved first, and don't skip the inspection or the radon test in a Willamette Valley home. Buyers who do those three things arrive at closing without surprises.
Quick Takeaways & FAQs
✅ Salem's typical home price is meaningfully below Portland's, making it one of the few remaining realistic entry points for first-time buyers in western Oregon.
⚠️ The median household income falls short of what's needed to comfortably carry the typical home here by roughly $37,000 — budget and pre-approval need to happen before touring, not after.
📍 West Salem sits in Polk County across the Willamette River; first-timers targeting that area should test the bridge commute to downtown or state offices during peak hours before making an offer.
What credit score do I need to buy a home in Salem, Oregon?
How much cash do I need to buy a home in Salem, OR as a first-time buyer?
Is Salem, Oregon a good place to buy a first home?
How long does it take to buy a home in Salem, Oregon?
Should I get an FHA or conventional loan for a home in Salem?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
