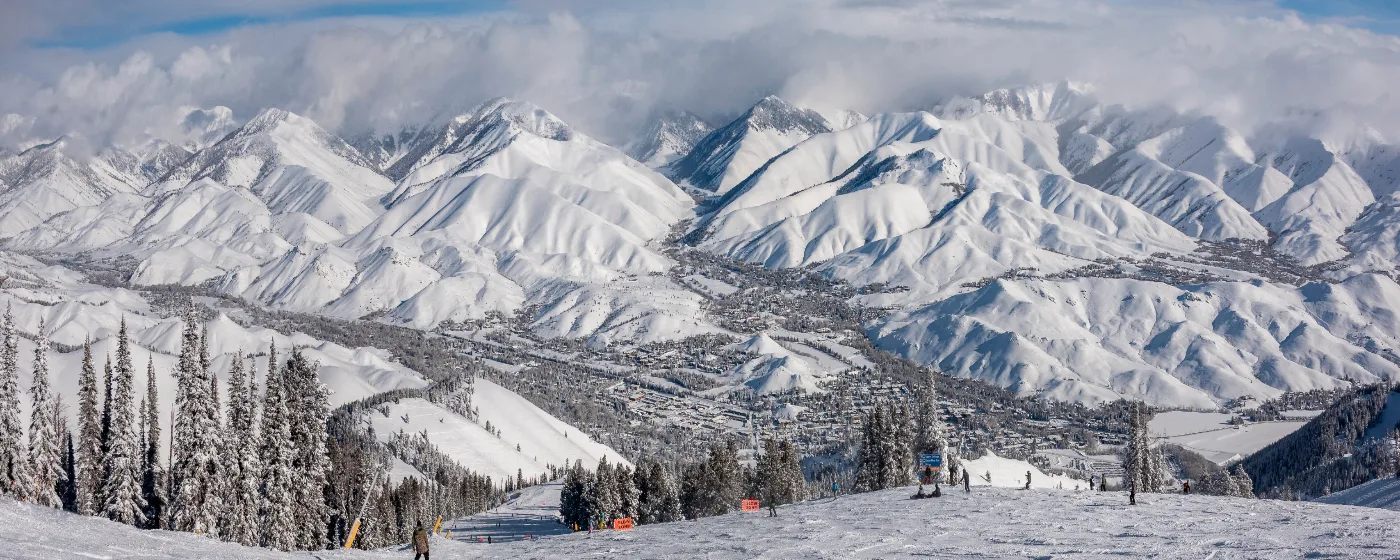
Maybe your employer brought you to the Wood River Valley, or you've spent enough ski seasons at Bald Mountain that renting finally stopped making sense. Either way, the first reality check for a first-time buyer in Sun Valley is the price. The Zillow Home Value Index (ZHVI) for Sun Valley stood at $1,162,529 in May 2026 — and that figure appreciated 13.1% over the prior year. This is not a market where a starter home means a modest two-bedroom. It is one of the most expensive zip codes in Idaho, shaped by the gravitational pull of Sun Valley Resort, constrained zoning, and a buyer pool that often includes cash-heavy second-home purchasers. Understanding that before you start touring is the only way to avoid wasting months of effort.
That said, the market in mid-2026 is meaningfully different from the frenzied seller's market of recent years. Homes were averaging 76 days on market in June 2026 — nearly three times longer than the year prior — and only four transactions closed that month across the entire city. Rising inventory and a market action index around 24 signal genuine negotiating room for buyers who show up prepared. Sun Valley Resort and Power Engineers anchor part of the local employment base, meaning some first-timers here are professionals with strong income but still stretching to cross the million-dollar threshold for the first time. For a full picture of what the cost of living looks like day-to-day, that page covers taxes, groceries, and utilities in depth.
The property tax story is one genuine structural advantage: at an effective rate of approximately 0.39% — among the lowest in Idaho — the annual carrying cost on a Sun Valley home is noticeably lower than comparable luxury markets in higher-tax states. Combined with statewide mortgage rates that held just over 6% through early 2026, the monthly math is at least more predictable than it was two years ago. What it is not is cheap. Entry-level here means something very different than it does in Hailey or Bellevue, and first-time buyers who anchor their expectations to those nearby markets often arrive in Sun Valley conversations underprepared. This guide walks through what your budget actually buys, how the local purchase process works, what the cash requirements look like across realistic scenarios, and the specific mistakes that cost first-timers the most in this market.
The Sun Valley First-Time Buyer Reality
The Zillow Home Value Index for Sun Valley reached $1,162,529 in May 2026 — and the gap between that figure and the active listing median tells you something important: the homes that actually sell here span a wide range, and a first-timer's best opportunity lies in the lower end of that range, not in the headline numbers. See the cost of living page for how purchase prices translate into monthly carrying costs.
Entry-level in Sun Valley means something specific. Older construction in some of the more accessible pockets of the city can reach the market in the $750,000–$900,000 range, though properties at that price point move faster than the city-wide 76-day average when they appear. New construction at any price point is constrained by zoning restrictions that limit what gets built — which is exactly why listings that do hit the market draw competitive attention from buyers who have been waiting.
The honest reality for most first-timers is that Sun Valley requires either a higher-than-typical income, a significant down payment accumulated over time, or both. The median household income in Sun Valley is $125,987, which supports a purchase in the $600,000–$750,000 range under conventional debt-to-income guidelines — below the entry point for most available inventory. That gap is the central challenge. Buyers who close it typically do so with larger down payments, family equity contributions, or by expanding their search to include Hailey and Bellevue for comparison, then deciding whether Sun Valley's access to Bald Mountain and the Resort campus is worth the premium.
The Homebuying Process in Sun Valley, Step by Step
Step 1: Get Pre-Approved — Before You Do Anything Else
In Sun Valley, pre-approval is not a formality — it is the price of admission to a serious conversation. Sellers and listing agents routinely decline to schedule showings or consider offers that arrive without a pre-approval letter from a reputable lender. A pre-approval means the lender has actually verified your credit score, income, W-2s, tax returns, and bank statements, and has issued a specific purchase-price ceiling. A pre-qualification — where you self-report numbers over a phone call — does not carry the same weight and will not open doors here.
The step most first-timers get wrong is conflating the two. Arrive with a pre-qualification letter in a market where the seller's agent is representing a $1.2 million property and you will likely be passed over for buyers who did the paperwork. Do the full pre-approval first, before you tour a single home.
Step 2: Complete a Homebuyer Education Course
The Idaho Housing and Finance Association (IHFA) offers online homebuyer education courses typically running 4–8 hours. These are mandatory for most state-backed loan programs, but first-timers benefit from them regardless of which loan type they pursue. The course covers the full purchase process in plain language and saves you from learning the basics at the negotiating table.
Step 3: Work With an Agent Who Knows This Micro-Market
Sun Valley is a small city — 1,761 residents — where the relevant agent network is tight and local knowledge matters enormously. An agent who primarily works Boise or Twin Falls will not know which listings are priced for a quick sale versus ones that have sat for 90 days because the seller is testing the market. Interview agents; ask them how many Sun Valley (not Wood River Valley — specifically Sun Valley city) transactions they closed in the past 12 months.
Step 4: Make Your Offer — Contingencies and All
With homes averaging 76 days on market in mid-2026, the days of waiving every contingency to win are largely behind the typical buyer. Include an inspection contingency and a financing contingency as baseline protections. The one place first-timers still make errors here: assuming that slower days-on-market means they have unlimited time. When a well-priced property lands at the lower end of available inventory, it still attracts multiple buyers quickly. Move with your pre-approval ready.
Step 5: Inspection, Appraisal, and Closing
Mountain-climate inspections in Sun Valley should include a thorough check of roof load capacity, HVAC systems (gas heating is standard and critical at this elevation), and any drainage or crawl-space issues common in older properties. Appraisals in a thin market — four sales in June 2026 — can be challenging because comparable sales are scarce. Budget 30–45 days from accepted offer to closing as a realistic timeline, though complex transactions in this market can run longer.
How Much Home Can You Afford in Sun Valley
The table below models cash requirements across realistic Sun Valley purchase scenarios using a 30-year fixed rate just over 6% (early-2026 statewide average). Closing costs are estimated at 2–3% of the purchase price and cover lender fees, title, escrow, and prepaid items — they vary by transaction. Use these as planning benchmarks, not guarantees; the interactive calculator below this section runs your specific numbers.
| Scenario | Purchase Price | Loan Type / Down Payment | Down Payment Amount | Est. Closing Costs (2–3%) | Est. Cash Needed at Table |
|---|---|---|---|---|---|
| FHA minimum — entry attempt | $750,000 | FHA / 3.5% | ~$26,250 | ~$15,000–$22,500 | ~$41,250–$48,750 |
| Conventional low-down — entry | $750,000 | Conventional / 3% | ~$22,500 | ~$15,000–$22,500 | ~$37,500–$45,000 |
| FHA — mid-entry | $900,000 | FHA / 3.5% | ~$31,500 | ~$18,000–$27,000 | ~$49,500–$58,500 |
| Conventional 5% — mid-entry | $900,000 | Conventional / 5% | ~$45,000 | ~$18,000–$27,000 | ~$63,000–$72,000 |
| Conventional 10% — ZHVI range | $1,162,529 | Conventional / 10% | ~$116,253 | ~$23,251–$34,876 | ~$139,504–$151,129 |
| Conventional 20% — ZHVI range | $1,162,529 | Conventional / 20% | ~$232,506 | ~$23,251–$34,876 | ~$255,757–$267,382 |
* ZHVI = Zillow Home Value Index. All figures are estimates for planning purposes only. Actual closing costs, rate, and cash requirements depend on your lender, loan program, and transaction specifics.
A few budget realities worth flagging before you run the calculator. Private mortgage insurance (PMI) applies to conventional loans with less than 20% down — it adds to your monthly payment and affects how much home your income can sustain. FHA loans carry their own mortgage insurance premium (MIP), which runs for the life of the loan if your down payment is under 10%. At Sun Valley price points, the PMI or MIP cost is not trivial, and first-timers should factor it into their monthly budget modeling. Idaho's effective property tax rate of approximately 0.39% is genuinely low by national standards, which helps offset the high purchase price somewhat over time.
Looking to buy in Sun Valley? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Sun Valley quote.
Common First-Time Buyer Mistakes in Sun Valley
Mistake 1: Shopping Before You Have a Pre-Approval Letter in Hand
This one costs buyers deals and time in equal measure. In a market where only a handful of homes trade each month, the window between a listing going live and an accepted offer can be days — not weeks. Buyers who start touring without pre-approval and then scramble to get paperwork together while a seller is fielding other interest almost always lose. Get the letter before you look at a single listing online, let alone in person.
Mistake 2: Waiving the Inspection Contingency on a Mountain-Climate Home
The slower market of mid-2026 means most first-time buyers do not need to waive inspection to be competitive. Those who still do — often because they watched the 2022–2023 frenzy and think that's still the norm — are taking on real risk. Older homes in Sun Valley can carry deferred maintenance issues that aren't visible at a showing: drainage problems, aging heating systems, roof wear from heavy snow loads. An inspection contingency is the single most important protection a first-timer can keep. Waiving it in a market that no longer requires you to is the mistake that keeps real-estate attorneys busy.
Mistake 3: Underbudgeting the Cash Required at Closing
First-timers consistently underestimate closing costs. They see the down payment figure and plan to that number — then discover at the closing disclosure stage that they need an additional $20,000–$35,000 for lender fees, title insurance, escrow, and prepaids. At Sun Valley price points, closing costs in the 2–3% range are a significant cash requirement on top of the down payment. Build that full number into your savings target from day one, not as a surprise two weeks before closing.
Mistake 4: Ignoring the Practical Geography of Where You're Buying
Sun Valley is a small city, but where within it you buy shapes your daily life more than the address suggests. Some areas sit close to the Sun Valley Village core and the main connection to Ketchum — about five minutes away — while others require more driving for everyday needs. First-timers who fall in love with a specific home without understanding how its location affects their winter driving patterns and proximity to services often have regrets by month six. Walk the neighborhood in winter conditions before you commit, not just during a summer showing.
Local Expert Takeaway: Sun Valley's first-time buyer window in mid-2026 is real — homes are sitting 76 days on average and sellers are negotiating — but only for buyers who arrive with a verified pre-approval letter, realistic cash reserves covering both down payment and closing costs, and an honest read on what entry-level actually means here. If your budget tops out around $750,000–$900,000, you are competing for a thin slice of older inventory in a market where that price range moves faster than the city-wide average. If you're weighing whether to stretch for Sun Valley or settle into Hailey or Bellevue first and build equity, that is a legitimate question — and one worth running through a local agent who closes deals in Sun Valley city specifically, not just the broader Wood River Valley.
Quick Takeaways & FAQs
✅ Sun Valley's effective property tax rate of approximately 0.39% is among Idaho's lowest, meaningfully reducing annual carrying costs on a high-value home.
⚠️ Entry-level inventory in Sun Valley starts around $750,000–$900,000 for older construction — the Zillow Home Value Index of $1,162,529 (May 2026) is the midpoint, not the starting line.
📍 Sellers here require a full pre-approval letter — not a pre-qualification — before they'll seriously engage with an offer; get that paperwork done before you tour a single property.
What is the minimum budget a first-time buyer needs to purchase in Sun Valley, Idaho?
Is Sun Valley a good market to buy in right now as a first-time buyer?
What loan types can first-time buyers use in Sun Valley?
How long does it take to close on a home in Sun Valley?
Should I waive the home inspection contingency to win a Sun Valley offer?
Moving to Idaho?
Tell us what you need help with and we'll connect you with local resources.
