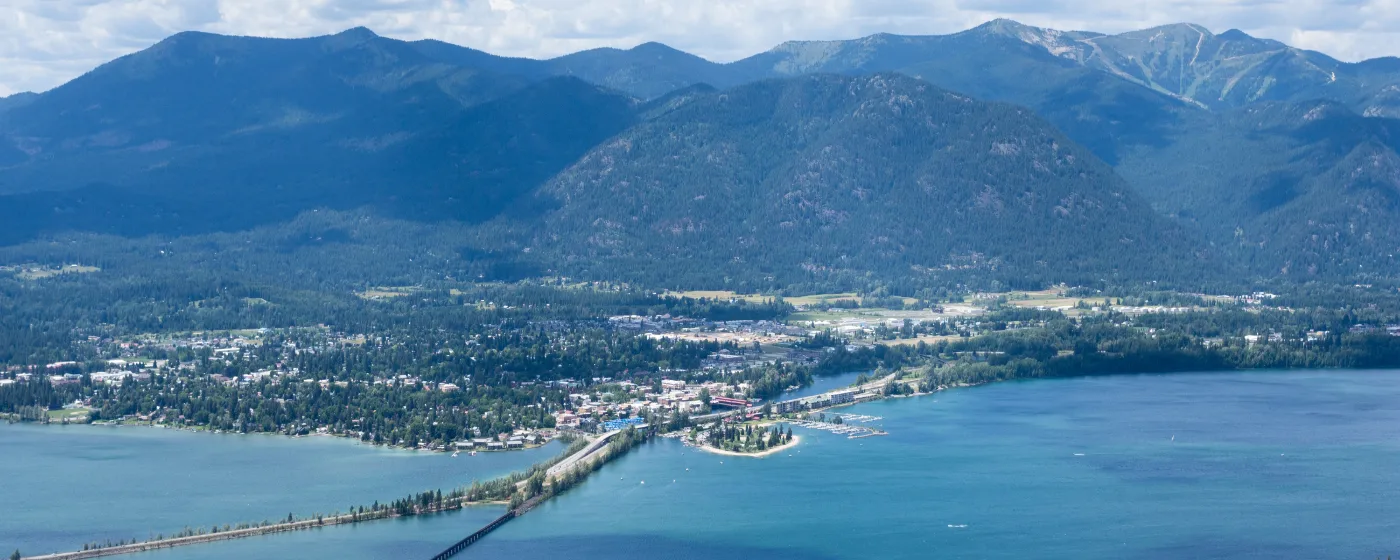
Sandpoint is the kind of place where people fall in love on a long weekend — the lake views from City Beach, a post-ski beer on Cedar Street, the way the Long Bridge lights up at dusk — and then spend the next six months trying to figure out how to actually afford to live here. The honest answer is that it takes planning, realistic expectations, and money at the table that surprises a lot of first-timers. With a Zillow Home Value Index of $588,781 (2026), Sandpoint is not entry-level Idaho. It sits in its own category: a resort-adjacent, lake-destination town where demand from buyers relocating from the Pacific Northwest and California has pushed prices well above what a median Bonner County household income can absorb without a meaningful down payment.
The good news is that the market has softened from its 2022 peak. As of May 2026, Sandpoint was carrying roughly 4.9 months of housing inventory — not quite a balanced market, but meaningfully more breathing room than buyers faced two years ago. Homes are averaging around 68 days on market and selling at approximately 98% of final list price, which means the era of waiving everything and offering $80,000 over ask has passed. That said, well-priced properties in move-in condition — especially anything under $550,000 — still move quickly. The window is open; it just isn't wide. For a deeper look at how prices here compare to your current cost of living, see the Sandpoint cost of living page.
The community itself anchors around Bonner General Health, Litehouse Foods, Schweitzer Mountain Resort, and a growing tech employer in Kochava. These employers keep a steady base of year-round residents in the market — not just seasonal buyers — which is part of why even a softened Sandpoint market doesn't collapse the way purely resort towns sometimes do. The people buying here want the lifestyle: the lake, the mountain, the Panida Theater on a Friday night, the Cedar Street Bridge Public Market on a Saturday morning. They are not speculating; they are relocating.
Whether you are moving from Spokane, leaving a lease in Ponderay, or making the jump from renting to owning for the first time anywhere, this guide covers what your budget actually buys in Sandpoint, how the buying process works locally, a plain-language budget table, and the specific mistakes that cost first-timers time and money in this market.
The Sandpoint First-Time Buyer Reality
Let's be direct: $588,781 is the Zillow Home Value Index for Sandpoint as of 2026, and that figure shapes everything. For a first-time buyer bringing 3–5% down, you are financing the better part of $570,000–$580,000, which is a significant number for a household earning the city's median income. Entry-level does exist here — older 2–3 bedroom homes in the 1,000–1,400 square foot range were listed in the $425,000–$525,000 range in early 2026 — but those properties don't sit long, and they rarely come without a list of deferred maintenance items that add to your real first-year cost.
What your budget actually buys depends heavily on where you look and what you're willing to compromise on. Properties closer to downtown, with walkable access to Sand Creek or the waterfront, trend toward and above the city median. Newer construction with view lots — the kind of homes marketed to Schweitzer-adjacent buyers — runs $575,000 to $800,000 and beyond. The honest framing for a first-timer: plan your search around the $425,000–$549,000 band and expect to move fast when something fits.
One thing working in your favor right now is that 4.9 months of inventory gives you more negotiating room than Sandpoint has seen in years. Sellers are pricing more carefully, and the days of waiving inspections to win are largely behind you — though not entirely gone on the sharpest-priced listings. Coming in pre-approved, financially ready, and realistic about condition is what separates buyers who close from buyers who spend six months watching listings go pending without them.
The Homebuying Process in Sandpoint, Step by Step
Step 1: Get Pre-Approved Before You Look at a Single House
In Sandpoint, sellers and their agents expect a pre-approval letter before they will seriously consider your offer. This is not a suggestion — it is the market standard for the Bonner County area, and listing agents will frequently ask your buyer's agent whether you are pre-approved before scheduling a showing on a hot property. Pre-approval requires a lender credit check plus documentation: recent pay stubs, W-2s, two years of tax returns, bank and asset statements, and a government-issued ID. Pull this together before you fall in love with a house on Zillow.
Step 2: Find a Buyer's Agent Who Knows Bonner County
Idaho permits dual agency — one agent representing both buyer and seller — but only with written consent from both parties. As a first-time buyer, you almost always benefit from your own representation. An agent who regularly works the local MLS will know which neighborhoods have septic issues, which streets flood near Sand Creek, and when a list price is realistic versus aspirational. That local knowledge is worth more than a commission rebate from an online platform.
Step 3: Shop With Your Pre-Approval Ceiling in Mind, Not Your Wishlist
The mistake most first-timers make in Sandpoint: they start touring $650,000 homes when their pre-approval is $520,000 because the photos looked too good to skip. After two or three of those tours, every home in their actual price range feels like a consolation prize. Shop within your number from day one, and let your agent flag anything genuinely underpriced outside it.
Step 4: Make an Offer — With Contingencies You Actually Intend to Use
With homes selling at roughly 98% of list price in this market, aggressive lowballing rarely lands. A well-structured offer at or near list, with a reasonable inspection contingency and a realistic closing timeline, is more competitive than a lower number with unusual terms. Do not waive your inspection contingency on a 1970s-era home in West Sandpoint to win a bidding situation — the inspection is how you discover whether that crawl space or roof is going to cost you $30,000 in year one.
Step 5: Inspection, Appraisal, and Closing
After an accepted offer, you will order a home inspection (typically 7–10 business days in Idaho) and your lender will order an appraisal if you are financing. In a market where prices have pulled back from their peak, appraisals have been less of a friction point than they were in 2021–2022 — but on lakefront-adjacent or view-lot properties, unusual comps can still create gaps. Idaho closings typically happen at a title company, not an attorney's office. Plan for a closing timeline of 30–45 days from accepted offer for a financed purchase.
How Much Home Can You Afford in Sandpoint
The table below gives you a plain-language snapshot of what different purchase prices require in cash at closing. Closing costs in Idaho typically run 2–3% of the loan amount for buyers, covering title insurance, lender fees, prepaid interest, and escrow setup. These are estimates — your lender's Loan Estimate will give you exact figures.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5% down) — entry-level | $430,000 | ~$15,050 (3.5%) | ~$9,000–$11,000 | ~$24,000–$26,000 |
| Conventional (3% down) — entry-level | $430,000 | ~$12,900 (3%) | ~$9,000–$11,000 | ~$22,000–$24,000 |
| FHA (3.5% down) — mid-range | $520,000 | ~$18,200 (3.5%) | ~$10,500–$13,000 | ~$29,000–$31,000 |
| Conventional (5% down) — mid-range | $520,000 | ~$26,000 (5%) | ~$10,500–$13,000 | ~$36,500–$39,000 |
| Conventional (10% down) — near median | $590,000 | ~$59,000 (10%) | ~$11,500–$14,000 | ~$70,500–$73,000 |
| Conventional (20% down) — avoid PMI | $590,000 | ~$118,000 (20%) | ~$11,500–$14,000 | ~$129,500–$132,000 |
Idaho's homeowner's exemption covers 50% of assessed value up to $125,000 for a primary residence, which can meaningfully reduce your taxable base — and with Sandpoint's effective property tax rate at approximately 0.43%, taxes here run well below the national average. The interactive calculator below this section will let you model monthly payments at any price point once you have your rate from a lender.
One critical note: closing costs are paid at the table, not rolled into your loan in most standard scenarios. First-timers who focus only on the down payment and forget closing costs often arrive at the finish line short. Budget for both from the beginning.
Looking to buy in Sandpoint? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Sandpoint quote.
Common First-Time Buyer Mistakes in Sandpoint
Mistake 1: Touring Homes Before You Have a Pre-Approval Letter
This one costs buyers real opportunities. A well-priced two-bedroom in the $450,000 range — the kind that shows up near Sand Creek or along the quieter streets off Boyer Avenue — can go pending in under three weeks in this market. If you need two more weeks to get pre-approved after falling in love with it, it will be gone. The Sandpoint market is not so slow that you can browse casually and then get financially ready later.
Mistake 2: Waiving the Inspection to Be Competitive
The pandemic-era practice of waiving inspection contingencies to win bidding wars has faded, but some buyers still do it when competition heats up on a specific listing. In a town where a meaningful portion of housing stock was built before 1990, and where moisture intrusion, aging septic systems, and deferred roof maintenance are genuine issues on older properties, waiving your inspection is a gamble that often costs far more than you saved on the purchase price. Keep the contingency. Negotiate on the repairs.
Mistake 3: Ignoring the Commute Reality
Sandpoint is 75 miles from Spokane — roughly 75 minutes in dry conditions on US-2 and US-95. In winter, that corridor through Newport and along the lake can add 20–30 minutes or close entirely in severe weather. Buyers who plan to commute to Spokane two or three days a week and dismiss the drive as "not that bad" during a summer house-hunt sometimes feel differently by February. If you are commuting regularly, a home closer to US-95 north of downtown shaves meaningful time off the departure each morning.
Mistake 4: Underestimating Total Cash Needed
The down payment is the number everyone focuses on. The closing costs — typically 2–3% of the loan amount in Idaho — are the number that blindsides people. On a $490,000 purchase with 5% down, you are financing roughly $465,500, which puts closing costs alone in the $9,300–$14,000 range. Add the down payment, any earnest money you put up (typically 1–2% of the purchase price), moving costs, and immediate repair or appliance needs, and the real cash-to-close figure is often $15,000–$20,000 more than buyers initially budget. Build that buffer before you start shopping, not after you are already in contract.
Local Expert Takeaway: Sandpoint's market has more breathing room than it did two years ago — 4.9 months of inventory and homes sitting an average of 68 days means you can negotiate, do your due diligence, and keep your contingencies. But entry-level inventory under $500,000 still moves quickly, and sellers expect a pre-approval letter before a serious conversation begins. Get your financing in order through a lender familiar with the Bonner County market, keep your inspection contingency intact on any older home near Sand Creek or in the West Sandpoint corridor, and budget for closing costs as a separate line item from your down payment. The buyers who close in Sandpoint are the ones who show up prepared — not the ones who made the best offer after the fact.
Quick Takeaways & FAQs
✅ Sandpoint's 4.9 months of housing inventory (May 2026) gives first-time buyers more negotiating leverage than the market has offered in several years.
⚠️ Entry-level homes in the $425,000–$525,000 range exist, but they move quickly and often come with deferred maintenance that adds real first-year costs — budget accordingly.
📍 Listings in Sandpoint are managed through the local MLS; sellers here expect a pre-approval letter before they will seriously entertain an offer, making that step non-negotiable.
What is the minimum credit score needed to buy a home in Sandpoint, Idaho?
How long does it take to close on a house in Sandpoint?
Do I need a buyer's agent to purchase a home in Sandpoint?
What qualifies as a first-time homebuyer in Idaho?
Are there bidding wars in Sandpoint right now?
Moving to Idaho?
Tell us what you need help with and we'll connect you with local resources.
