Maybe someone told you Othello was affordable and you did a quick search and thought — yes, that's real. Or maybe you've been renting in the Columbia Basin for a few years, watching your rent creep upward while home prices in Moses Lake started to feel out of reach. Either way, Othello is genuinely one of the more accessible first-time buyer markets left in Washington State, and the reasons are worth understanding before you make an offer. The Zillow Home Value Index for Othello sat at $339,351 as of June 2026 — see the full cost-of-living breakdown for context on what that means day-to-day.
The economy here is anchored in agriculture and food processing — Lamb Weston's frozen potato operation is among the largest private employers in town, and the surrounding Columbia Basin farms create a steady workforce that defines the community's makeup. That's important for a first-time buyer to understand: this is a working-class, production-economy town, not a bedroom suburb. The people moving in tend to be young families putting down roots near stable employment, or buyers who want a lower purchase price for the same square footage they'd find in a larger nearby city.
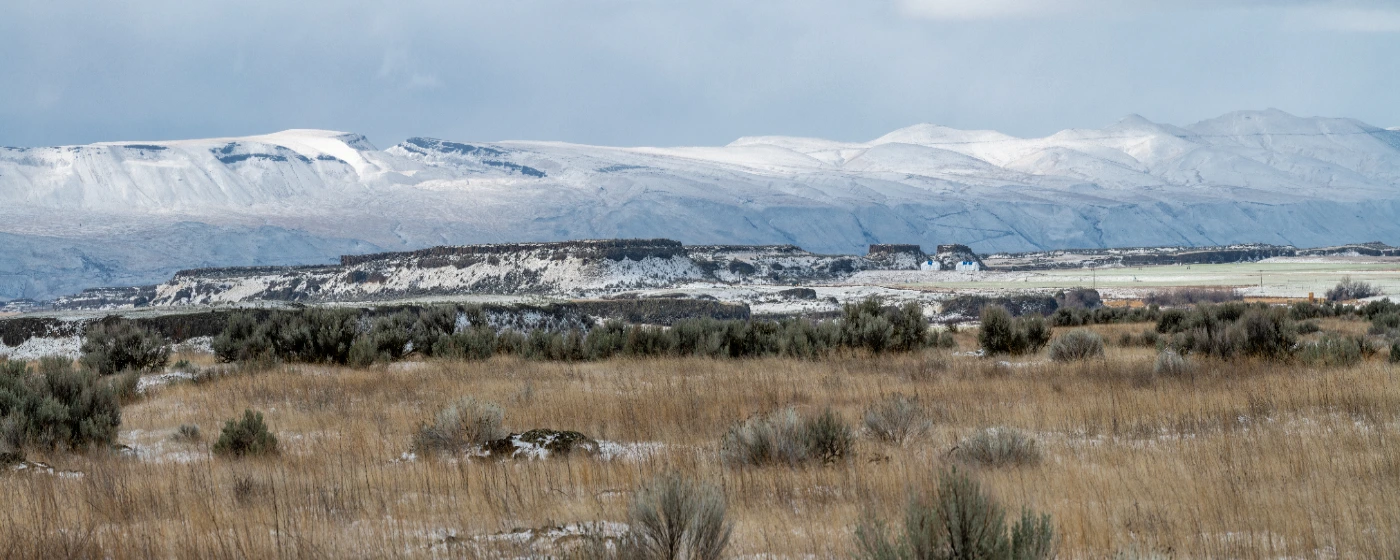
On the lifestyle side, Othello sits at the edge of the Columbia National Wildlife Refuge and the Drumheller Channels National Natural Landmark — not bad for a city of under 9,000 people. Pioneer Park and Lions Park handle daily outdoor needs without a long drive. The annual Sandhill Crane Festival brings birding enthusiasts from across the Pacific Northwest every spring and gives the town an identity that goes beyond the potato harvest. If you grab coffee before a weekend of house-hunting, Ironworks Cafe & Market on S Broadway Ave and Desert Rose Cafe on E Hemlock St are both confirmed open as of 2026 and give you a quick read on the town's everyday pace.
This guide covers everything a first-time buyer needs to navigate the Othello market: what your budget realistically gets you, the step-by-step local process, a budget snapshot table, and the specific mistakes that cost first-timers in this market time and money.
The Othello First-Time Buyer Reality
Othello's market moves slowly by Washington standards — homes spent a median of 113 days on the market in July 2026, unchanged from a year earlier. That pace is a gift for first-time buyers who need time to arrange financing, schedule inspections, and think clearly rather than bid emotionally.
The Zillow Home Value Index pegged the typical Othello home at $339,351 as of June 2026. Median list prices ran higher — around $389,000 in July 2026 — because sellers set asking prices above the smoothed index value. Expect to shop in the gap between those two numbers and negotiate toward the lower end, especially on homes that have been sitting for 60 or more days.
With roughly 81 active MLS listings as of August 2026 — a meaningful supply for a city this size — first-time buyers have real options across a range of price points and home ages. Entry-level inventory at the lower end of the market remains thin relative to overall supply and moves faster than the overall average, so buyers targeting the most affordable segment need to be financing-ready before they start touring.
The Homebuying Process in Othello, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
Pre-approval is the single step first-time buyers most often skip or delay in Othello — and the one that costs them most. Even in a slower market, the most affordably priced listings move quickly. Arriving at a showing without a pre-approval letter puts you behind any buyer who has one.
Pre-approval means a lender has pulled your credit, verified your income and assets, and issued a written commitment for a specific loan amount. A pre-qualification — where you self-report your finances — is not the same thing and won't carry weight in a negotiation. Get the real letter first.
Step 2: Define Your Search by Area and Price Band
Othello's neighborhoods feel different from each other in ways that matter for daily life. Older blocks near the downtown core offer walkable access to errands but may need more maintenance investment. Newer subdivisions offer modern finishes but sit farther from the commercial core. Decide which trade-off fits your life before you start touring, not after you've fallen for a house in the wrong area. The living in Othello guide covers neighborhood character in detail.
Step 3: Make an Offer with the Right Contingencies
In a slow market like Othello's, buyers have negotiating leverage — but that doesn't mean contingencies are formalities. An inspection contingency gives you the right to renegotiate or walk away after a professional inspection. An appraisal contingency protects you if the home appraises below the purchase price. Keep both.
The step first-time buyers most often get wrong at this stage is assuming that a slow market means they can skip contingencies to strengthen their offer. You rarely need to. Sellers in Othello have been sitting on inventory for months; a clean, fully contingent offer from a pre-approved buyer is usually competitive enough.
Step 4: Inspection and Appraisal
Washington requires a professional home inspection before closing — budget $350–$500 for a standard single-family home. Older homes in particular can carry deferred maintenance that shows up in the inspection report but not in the listing photos. Read every line of that report.
Your lender will order an appraisal independently. If the appraisal comes in below your purchase price and you have an appraisal contingency, you can renegotiate the price, make up the difference in cash, or walk away. In Othello's current market, appraisal gaps are less common than in hot metro markets — but they happen, especially on properties with ambitious list prices.
Step 5: Closing
Washington closes through escrow and title companies rather than attorneys. The process typically takes 30–45 days from accepted offer to keys. Your closing disclosure — issued at least three business days before closing — will show every cost line by line. Read it carefully against the loan estimate you received at pre-approval; if numbers shifted, ask your lender to explain each change before you sign.
How Much Home Can You Afford in Othello
The table below shows estimated cash required at closing across several purchase-price scenarios common in Othello's market. Closing costs are estimated at 2–3% of the purchase price, which is typical for Washington State transactions and includes lender fees, title insurance, escrow fees, and prepaid items. These are estimates — your actual figures will depend on your lender, loan type, and negotiated seller concessions.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA 3.5% — entry-level older home | $265,000 | $9,275 (3.5%) | $5,300–$7,950 | ~$14,575–$17,225 |
| Conventional 3% — entry-level older home | $265,000 | $7,950 (3%) | $5,300–$7,950 | ~$13,250–$15,900 |
| FHA 3.5% — typical Othello home (ZHVI) | $339,000 | $11,865 (3.5%) | $6,780–$10,170 | ~$18,645–$22,035 |
| Conventional 3% — typical Othello home | $339,000 | $10,170 (3%) | $6,780–$10,170 | ~$16,950–$20,340 |
| Conventional 5% — mid-market / newer build | $390,000 | $19,500 (5%) | $7,800–$11,700 | ~$27,300–$31,200 |
| Conventional 10% — newer subdivision | $420,000 | $42,000 (10%) | $8,400–$12,600 | ~$50,400–$54,600 |
* ZHVI = Zillow Home Value Index.
FHA loans carry upfront and ongoing mortgage insurance premiums that add to your monthly cost — factor that in when comparing FHA versus conventional at the same purchase price. Conventional loans with less than 20% down require private mortgage insurance, which drops off once you reach sufficient equity.
One benchmark worth knowing: the Washington State Housing Finance Commission administers statewide programs that can help reduce upfront costs for qualified buyers purchasing a primary residence — most require completion of a homebuyer education course. Talk to a lender familiar with Adams County transactions to confirm which programs apply to your income and purchase price.
Looking to buy in Othello? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Othello quote.
Common First-Time Buyer Mistakes in Othello
Waiving the Inspection Contingency to Look More Competitive
In a high-demand metro market, waiving inspection contingencies is sometimes a calculated risk. In Othello — where homes sit for a median of 113 days — it's almost never necessary. Older homes throughout the city can carry aging electrical panels, roof issues, and irrigation system problems that a qualified inspector will catch. Walk away from any advice to waive this protection here.
Shopping Seriously Before You Have a Pre-Approval Letter
Touring homes before you're pre-approved feels harmless until an affordably priced listing you love goes under contract to a buyer who had their paperwork ready. The entry-level segment of Othello's market is the one place where competition is real. Pre-approval is a two-to-five day process with most lenders — complete it before you tour a single property.
Moving to Othello Without Honestly Evaluating Your Lifestyle Fit
Othello attracts buyers partly because its prices are noticeably lower than larger cities in the region. That difference is real and manageable for many households — but everyday life here is genuinely different from a larger city, and it deserves honest consideration before you commit. Think through what you're giving up and what you're gaining in terms of pace, services, and community before signing anything.
Underestimating Cash Needed at Closing
The down payment is the number first-time buyers fixate on — but closing costs in Washington typically add another 2–3% of the purchase price on top of it. On a $339,000 home, that's an additional $6,780 to $10,170 that needs to be liquid on closing day, separate from your down payment. Some sellers will agree to cover a portion of closing costs as part of negotiation, which is worth asking for in Othello's buyer-friendly market — but never assume it's guaranteed. Build the full cash-needed figure into your savings target from day one.
Local Expert Takeaway: Othello is one of the more forgiving first-time buyer markets left in Washington — prices are accessible, inventory is real, and homes stay on the market long enough for buyers to do their homework. The catch is that entry-level inventory moves faster than everything else, so if you're targeting the most affordable end of the market, you need your pre-approval letter in hand before you walk into a showing. Grab a coffee at Ironworks Cafe & Market on S Broadway Ave before your first tour and take the market at the measured pace it allows — just don't let that measured pace make you sloppy on inspection contingencies or closing-cost budgeting.
Quick Takeaways & FAQs
✅ Othello's typical home price of $339,351 (Zillow Home Value Index, June 2026) makes it one of the most accessible owner-occupied markets in South Central Washington for first-time buyers.
⚠️ Homes sat on the market a median of 113 days in July 2026 — a pace that gives first-timers room to do due diligence, but entry-level listings still move noticeably faster than the overall average.
📍 Washington closes through escrow and title companies, not attorneys — and your closing disclosure must arrive at least three business days before signing, giving you a final window to compare costs against your original loan estimate.
What credit score do I need to buy a home in Othello, WA?
How long does it take to close on a home in Othello?
Is it cheaper to buy or rent in Othello right now?
What are closing costs in Washington State for a first-time buyer?
Do first-time buyers have any loan advantages in Adams County, WA?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
