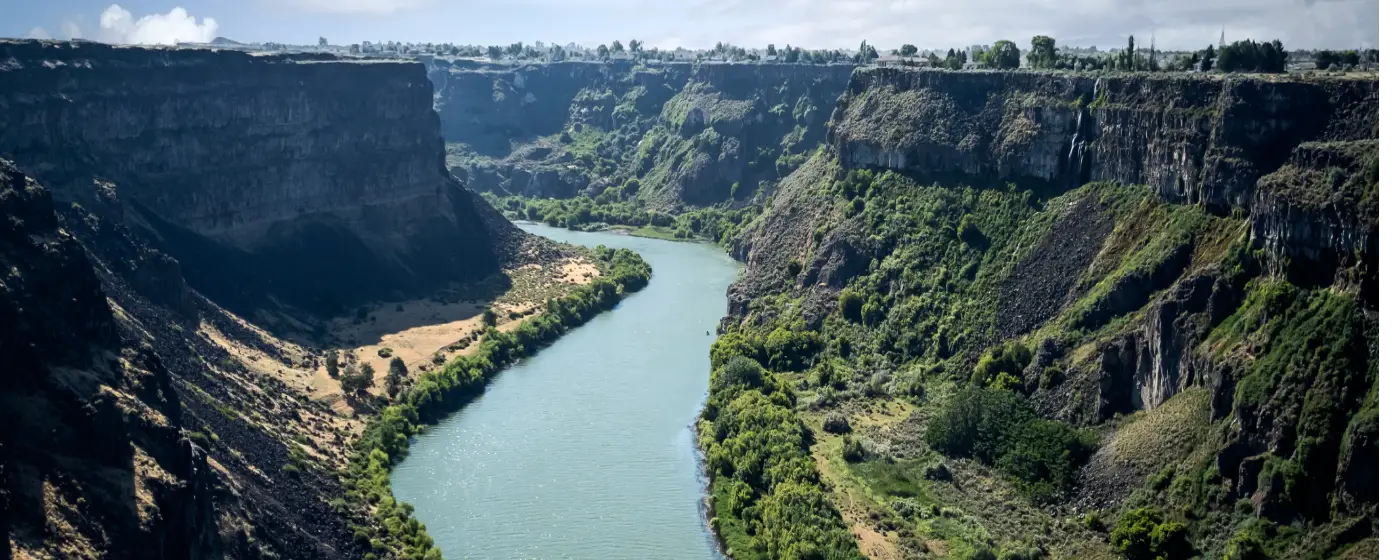
Ontario sits at the Idaho border in Eastern Oregon, where the Snake River marks the state line and I-84 connects the city to Boise in one direction and the rest of Oregon in the other. For first-time buyers priced out of the Treasure Valley, Ontario represents something genuinely unusual in the current market: a city where a three-bedroom house with a yard is still within reach of a working household income, without the commute penalties you'd expect for that kind of affordability. The catch is real though — the median household income here is below what it takes to qualify for the typical home at current rates, which means budgeting honestly from the start matters more here than it would in a stronger-income market.
The economic backbone of Ontario centers on Malheur County government, the Ontario School District, Saint Alphonsus Medical Center, the City of Ontario, and Treasure Valley Community College — a 90-acre campus that doubles as a cultural anchor through the Four Rivers Cultural Center. These institutions provide steady, if modest, employment, and they anchor the local workforce that makes up the bulk of buyers in this market. A meaningful share of households also draw income from Malheur County's deep agricultural economy — wheat, potatoes, hay, mint, cattle — and lenders here reflect that reality, with options ranging from regional credit unions to farm credit institutions that understand variable agricultural income.
At $312,219 (Zillow Home Value Index, July 2026), Ontario's typical home price is noticeably below comparable small cities across much of Oregon, and well below what a similar-sized house would cost across the border in Payette or in the broader Boise metro. The rent-versus-buy math is tighter than the sticker price suggests — Malheur County's federally published fair market rent for a three-bedroom unit runs over $1,300 per month — so buyers who can clear the down payment and qualify for a mortgage often find ownership genuinely cheaper month-to-month than renting. Ontario's property tax rate of approximately 0.85% is also modest by Pacific Northwest standards, keeping long-term carrying costs predictable. For a full cost-of-living picture beyond the purchase price, see the cost of living in Ontario breakdown.
Whether you're relocating from Boise, moving from elsewhere in Oregon, or buying your first home right here in Malheur County, this guide walks through what your budget actually buys in Ontario, the local homebuying process step by step, realistic cash-to-close scenarios, and the specific mistakes that trip up first-timers in this market.
The Ontario First-Time Buyer Reality
Ontario's typical home price of $312,219 (July 2026) puts true homeownership within reach for buyers who have done the savings work — but the entry point is not as forgiving as that number implies. The median household income in Ontario is $47,540, which falls short of what most lenders require to carry that mortgage comfortably at current rates. That gap is roughly $8,000 annually, meaning first-timers here often need a larger down payment, a co-borrower, or a purchase price below the city median to make the math work.
First-timers typically compete for smaller homes and older construction at the lower end of the market — homes priced well still sell efficiently, but move-in-ready homes at honest prices are not sitting long. Ontario is more balanced than it was during the pandemic years, with room to negotiate on listings that have sat, yet the entry-level segment draws serious buyers. Understanding where you fit in that range before you start touring is more important here than in a market with abundant inventory.
Ontario is eligible for USDA Rural Development financing throughout Malheur County, which allows qualified buyers to purchase with zero down. Eligibility is confirmed address by address on USDA's eligibility portal, so verify the specific property before making an offer — but in a city of 11,957 people sitting well under USDA's rural population ceiling, the program is broadly available here and worth understanding. For buyers with agricultural income, lenders like AgWest Farm Credit serve this market specifically. Rogue Credit Union, which absorbed the former Malheur Federal Credit Union, also maintains a local presence. The range of lending options is wider than you might expect for a city this size.
The Homebuying Process in Ontario, Step by Step
Step 1 — Get Pre-Approved Before You Tour Anything
In a small-inventory market like Ontario, the gap between a listing appearing and an offer being accepted can be days, not weeks. Buyers who start shopping without a pre-approval letter frequently lose homes they wanted to buyers who were ready. A pre-approval also shows you the real number — what a lender will actually commit to — which often differs from what an online calculator suggests when it does not account for your actual debt load, income documentation, or credit profile.
Step 2 — Choose the Right Loan Type for Your Situation
FHA loans (3.5% down with a 580+ credit score) and conventional loans (as low as 3% down with strong credit) are the two most common paths for first-timers here. Ontario's USDA eligibility adds a third, meaningful option: zero-down financing for buyers who meet income limits and purchase an eligible property. The loan type shapes your down payment, your monthly mortgage insurance obligation, and what the seller sees when they read your offer — so this decision belongs in the pre-approval conversation, not after you find a house.
Step 3 — Shop With a Clear Price Ceiling
Your pre-approval letter may say more than you should spend. In Ontario, where the affordability margin is thin relative to local incomes, buying at the top of your approval rather than a comfortable range below it leaves no buffer for a furnace replacement or a roof repair in year two. Set a ceiling you can sustain, not the ceiling the lender will allow.
Step 4 — Make an Offer That Reflects the Market
Ontario is not a bidding-war market the way Boise was in 2021 and 2022. Homes priced well still sell efficiently; homes priced above what the appraisal will support do not. First-timers sometimes over-offer out of anxiety, which creates its own problem: an appraisal that comes in below the purchase price and a gap the buyer suddenly has to cover in cash. Lean on comparable sales data your agent pulls, and don't let competition pressure push the offer above what the numbers justify.
Step 5 — Inspection and Appraisal: Don't Skip Either
The inspection contingency is the step most commonly waived in competitive markets — and the one most commonly regretted in Ontario's older housing stock. Homes in older parts of the city frequently date to mid-century construction, which means knob-and-wiring electrical systems, aging plumbing, and deferred maintenance that a seller disclosure won't fully surface. The appraisal is lender-ordered and not optional on a financed purchase, but the inspection is the one that protects you.
Step 6 — Closing
Oregon closing costs for buyers typically run between 2% and 3% of the purchase price, covering lender fees, title insurance, escrow, and prepaid items like homeowners insurance and property tax reserves. At Ontario's typical price point, that is a meaningful cash requirement on top of your down payment — see the budget table in the next section. Closing in Oregon is handled by a title or escrow company, and the process takes 30 to 45 days from an accepted offer under normal conditions.
How Much Home Can You Afford in Ontario
The table below shows estimated cash needed at closing for several realistic purchase scenarios in Ontario. Down payment percentages are approximate; closing costs are estimated at 2.5% of the purchase price. These are illustrative ranges — your actual figures depend on your lender, loan program, and negotiated terms. The interactive calculator below this section lets you adjust the numbers for your situation.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| USDA (0% down) | $230,000 | $0 | ~$5,750 | ~$5,750 |
| FHA (3.5% down) — entry level | $230,000 | ~$8,050 | ~$5,750 | ~$13,800 |
| FHA (3.5% down) — city median | $312,219 | ~$10,928 | ~$7,805 | ~$18,733 |
| Conventional (3% down) — entry level | $230,000 | ~$6,900 | ~$5,750 | ~$12,650 |
| Conventional (5% down) — city median | $312,219 | ~$15,611 | ~$7,805 | ~$23,416 |
| Conventional (10% down) — above median | $350,000 | ~$35,000 | ~$8,750 | ~$43,750 |
All figures are estimates for planning purposes only. A pre-approval conversation with a lender will give you the actual numbers for your income, credit, and chosen loan program.
The rent-versus-buy question is real in Ontario. Malheur County's federally published fair market rent for a three-bedroom unit runs over $1,300 per month — which means qualified buyers at the lower end of the purchase range may find that ownership, once past the upfront cash hurdle, costs less monthly than continuing to rent. The upfront cash is the real barrier, not the ongoing carrying cost, which is why building savings toward the scenarios in the middle of this table is where most Ontario first-timers should focus their planning energy.
Looking to buy in Ontario? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Ontario quote.
Common First-Time Buyer Mistakes in Ontario
Waiving the Inspection on Older Stock
Much of Ontario's housing inventory dates to mid-century construction — and that history means deferred maintenance. Buyers who waive the inspection contingency to strengthen an offer frequently discover after closing what an inspection would have surfaced before it. In a market where well-priced homes move, it can feel like you need to give something up to compete. The inspection contingency is almost never the right thing to sacrifice.
Shopping Before Pre-Approval
Ontario's inventory is limited for a city its size, and the homes priced at the entry level attract serious buyers. Walking into a showing without a pre-approval letter is not just a credibility problem with sellers — it means you genuinely do not yet know what you can buy. First-timers who fall in love with a home at $285,000 and then discover they qualify for $240,000 face a painful recalibration. Start at the lender, not the listing portal.
Ignoring the Commute Reality
Ontario's affordability relative to the Boise metro is genuine, and it draws buyers who plan to work in Idaho. The drive is about 55 minutes to Boise, ID — on a good day, in light traffic, on I-84. Before you budget around that commute five days a week, drive it in morning conditions, not on a weekend afternoon. Buyers who underestimate what a daily Idaho commute costs in time and fuel sometimes find themselves reconsidering the purchase within the first year.
Underestimating Cash to Close
The down payment is the number buyers focus on. Closing costs are the number that surprises them. At Ontario's typical price point, 2% to 3% in closing costs adds $6,000 to $9,000 on top of the down payment — cash that needs to be liquid and documented well before closing day. Some buyers arrive at the table having moved money between accounts in the weeks prior, which triggers lender documentation requests that can delay closing. Keep your down payment and closing cash in one stable account for at least 60 days before you apply.
Choosing a Home Without Checking School Boundaries
The Ontario School District 8C holds a C+ rating, according to Niche, and families with school-age children sometimes make assumptions about which school a given address feeds without verifying the actual boundary. In a small district serving 2,056 students enrolled in 2025-26, boundary lines are not always where you'd expect them based on geography. If school assignment matters to your household, check the specific address against the district boundary map before you make an offer — not after. The full school picture is on the Ontario schools page.
Local Expert Takeaway: Ontario is one of the few places in the Pacific Northwest where a first-time buyer with solid savings and a conventional income can still purchase a three-bedroom house without stretching into financial stress. The USDA zero-down option is available across all of Malheur County and is under-used here. The honest constraint is income: the median household income falls short of what current rates require to carry the typical home comfortably, so buyers who do their savings work early, get pre-approved before touring, and resist the temptation to buy at the ceiling of their approval tend to land well here. The entry point is real — the margin for error is just thin.
Quick Takeaways & FAQs
✅ Ontario's typical home price of $312,219 (July 2026) is among the most accessible in Oregon, with USDA zero-down financing available throughout Malheur County.
⚠️ The median household income in Ontario falls short of what's needed to comfortably carry the typical home at current rates — building savings above the minimum down payment is essential, not optional.
📍 Ontario sits about 55 minutes from Boise by I-84; buyers drawn by the affordability who plan to commute into Idaho should factor that drive into their total cost of ownership before making an offer.
Can I use a USDA loan to buy a home in Ontario, Oregon?
What is the minimum down payment to buy a home in Ontario, OR?
How long does it take to close on a home in Ontario, Oregon?
What are closing costs for a buyer in Ontario, Oregon?
Is it cheaper to rent or buy in Ontario, Oregon right now?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
