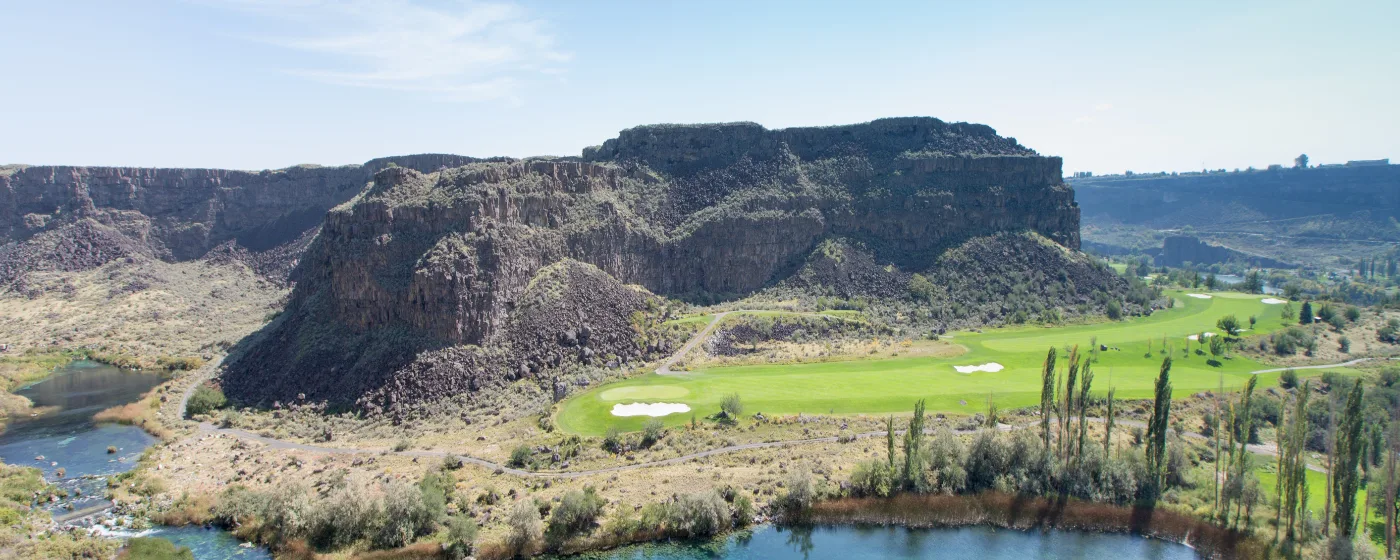
Maybe you've been priced out of Twin Falls and someone mentioned Jerome as a place where the numbers still make sense. Maybe you drove through on US-93 and wondered why you hadn't looked here sooner. Either way, Jerome surprises most first-time buyers the same way: it's a working agricultural city — dairy processing, plastics manufacturing, beef packing — with a genuine small-town grid, a median home price well below the state's flashier markets, and a cost of living that runs noticeably below the national average. What it is not is a bedroom community designed around you, and understanding that distinction shapes every decision you'll make here.
Jerome sits roughly 12 minutes west of Twin Falls on I-84, which means a buyer working in Twin Falls can commute in less time than many people spend finding parking in a larger city. The local economy is anchored by industrial and food-production employers — Novolex, Idaho Milk Products, Jerome Cheese Company, True West Beef — which gives the city a stability that doesn't depend on tech-sector hiring cycles. That same industrial base keeps wages moderate, which is why the median household income of $66,894 and a median sale price of $351,000 (Redfin, May 2026) actually fit together in a way that's increasingly rare across southern Idaho.
For a first-time buyer, the practical upside is real negotiating room. Jerome homes recently averaged about 53 days on market and sold for roughly 3% below list price — a pace that rewards buyers who come prepared rather than penalizing them for taking a week to think. Housing costs here run noticeably below the national average, which means your first mortgage payment is doing less damage to your monthly budget than it would in most comparable Idaho cities. The downside is inventory: Jerome is a small city, and the mix of move-in-ready homes in the under-$300,000 range can be thin on the ground at any given moment.
Whether you're just running the numbers or ready to make an offer, the sections below walk through what your budget actually buys in Jerome, how the buying process works locally, a concrete affordability snapshot, and the specific mistakes that trip up first-timers in this market.
The Jerome First-Time Buyer Reality
The median sale price in Jerome was $351,000 as of May 2026 — a number that puts genuine homeownership within reach of a household earning close to the local median income, particularly with a modest down payment. That figure represents the middle of the market, which means entry-level options exist below it, though they require hustle to find and move quickly on.
The lower end of the market tends toward older construction where cosmetic updates are usually needed and mechanical systems may be aging. The mid-range opens up to include newer builds and updated ranches, while homes above the median — particularly new construction on the south and east sides of town — push prices toward and above $400,000. For a full breakdown of what different price points get you in specific parts of Jerome, see the neighborhoods guide.
Competition is real but not brutal. Jerome's market is currently described as "somewhat competitive" — homes sell for about 3% below asking on average, which gives first-timers a window to negotiate that simply didn't exist during 2021–2022. The catch is that well-priced, move-in-ready homes in the $300,000–$350,000 range still move faster than the city-wide average suggests. If you see something that fits your budget and passes a quick walk-through, waiting a week to decide is often the difference between writing an offer and watching someone else close.
The Homebuying Process in Jerome, Step by Step
Step 1: Get Pre-Approved Before You Tour
This is the step most first-timers in Jerome skip, and it's the most expensive mistake on the list. Pre-approval is not the same as pre-qualification — a full pre-approval means a lender has pulled your credit, verified income, and issued a conditional commitment. Without it, sellers in Jerome's mid-range price bands will not take your offer seriously, and your agent can't effectively negotiate on your behalf.
Idaho lenders currently require a credit score of 740 or higher to access the best advertised rates. FHA loans are available with scores as low as 580 with 3.5% down; VA loans for eligible veterans typically require a lender minimum of 620 or above. Idaho's 30-year fixed rates ran between 6.75% and 6.92% in July–August 2026, depending on the lender and your credit profile — shop at least two or three local and regional lenders before committing.
Step 2: Define Your Search Before You Fall in Love
Jerome is small enough that knowing one or two specific areas narrows your search meaningfully before you ever schedule a showing. Decide on your non-negotiables: garage, lot size, commute direction, school boundary. Your agent can pull active listings filtered to those criteria; without filters, you'll spend weekends touring homes that don't work.
Step 3: Write a Clean Offer
In Jerome's current market, offers that come in 2–3% below list with a standard inspection and financing contingency are routinely accepted. You rarely need to waive contingencies to be competitive. A clean offer — pre-approval letter attached, earnest money in hand (typically 1–2% of purchase price), no unusual demands — moves faster than an aggressive price with strings attached.
Step 4: Inspection and Appraisal
Never skip the inspection in Jerome. Older homes in established residential pockets can carry aging HVAC, outdated electrical panels, or deferred maintenance that isn't visible on a showing. Hire an independent inspector — not one the listing agent suggests — and read the full report before removing your inspection contingency.
The appraisal is ordered by your lender after your offer is accepted and protects the lender, not you. If the home appraises below the purchase price, you can negotiate the price down, make up the gap in cash, or walk away. In Jerome's current market, appraisal gaps are less common than they were at the pandemic peak, but they still occur on new construction where list prices are set aggressively.
Step 5: Closing
Idaho is a title-company state — you'll close at a title company, not a courthouse or attorney's office. Closing typically takes 30–45 days from an accepted offer. Budget 2–3% of the purchase price for closing costs on top of your down payment; the exact total depends on your loan type, lender fees, and whether you negotiate seller concessions. Your lender is required to provide a final settlement statement at least three business days before closing — read it line by line and flag anything that changed from your original Loan Estimate.
How Much Home Can You Afford in Jerome
The table below shows approximate cash requirements at different purchase price points using common loan structures. These are estimates meant to illustrate the range — your actual costs will vary based on lender fees, title charges, and negotiated seller concessions. The interactive calculator below the table lets you run your specific scenario.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–3%) | Approx. Cash Needed at Table |
|---|---|---|---|---|
| FHA 3.5% — entry-level older home | $250,000 | $8,750 (3.5%) | $5,000–$7,500 | ~$13,750–$16,250 |
| Conventional 3% — entry-level updated | $280,000 | $8,400 (3%) | $5,600–$8,400 | ~$14,000–$16,800 |
| FHA 3.5% — near Jerome median | $320,000 | $11,200 (3.5%) | $6,400–$9,600 | ~$17,600–$20,800 |
| Conventional 5% — near Jerome median | $351,000 | $17,550 (5%) | $7,020–$10,530 | ~$24,570–$28,080 |
| Conventional 10% — upper market | $400,000 | $40,000 (10%) | $8,000–$12,000 | ~$48,000–$52,000 |
| Conventional 20% — new construction | $440,000 | $88,000 (20%) | $8,800–$13,200 | ~$96,800–$101,200 |
The 20% down scenario eliminates private mortgage insurance (PMI), which meaningfully reduces your monthly payment over the life of the loan — worth the math if you're sitting on savings. At the FHA entry points, mortgage insurance is built into the loan structure and adds to your monthly cost; factor that in when you run the calculator below.
One note on loan type: FHA loans carry both an upfront mortgage insurance premium (financed into the loan) and an annual premium split across monthly payments. Conventional loans above 80% loan-to-value carry PMI until you reach 20% equity, but unlike FHA's annual premium, conventional PMI can be canceled once your equity is established. For buyers with strong credit scores and enough savings to reach 5–10% down, running both FHA and conventional scenarios side by side with your lender is worth the extra 20 minutes.
Looking to buy in Jerome? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Jerome quote.
Common First-Time Buyer Mistakes in Jerome
Waiving the Inspection to "Win" the Offer
Jerome is not a market where you need to waive your inspection contingency. Homes here average 53 days on market — that's not a bidding-war environment. Buyers who waive inspections on older homes in established Jerome neighborhoods have discovered aging electrical panels and failing HVAC systems after closing, with no recourse. Keep your inspection contingency. Every time.
Shopping Without Pre-Approval
Touring homes before you have a lender's pre-approval letter in hand wastes everyone's time and occasionally costs buyers the house they wanted. Jerome's best-priced homes in the $300,000–$340,000 range move faster than the city-wide average. When one comes available, sellers expect an offer with a pre-approval attached within days, not a week while you scramble to find a lender.
Underestimating the Cash You Need at Closing
The down payment is only part of the check you write at closing. First-timers consistently underbudget closing costs, which run 2–3% of the purchase price on top of the down payment. On a $351,000 purchase, that's an additional $7,000–$10,500 you need to have liquid — not in a retirement account, not in a certificate of deposit that takes five business days to liquidate. Start your savings target with the full cash-needed figure from the table above, not just the down payment line.
Not Thinking Through Where Your Daily Life Actually Pulls
Most everyday services — larger grocery stores, medical specialists, big-box retail — are in Twin Falls, not Jerome. Buyers who choose a home purely on price without thinking about which part of Jerome puts them closest to their actual daily routine often find themselves making the Twin Falls run more than they expected. Think about where you work, where you'll shop, and which direction you'll drive most mornings before you decide which end of town to focus your search on.
Local Expert Takeaway: Jerome's $351,000 median sale price (May 2026) and roughly 53-day average days on market give a prepared first-time buyer genuine leverage — but "prepared" means pre-approved, inspection contingency intact, and with enough liquid cash to cover both your down payment and 2–3% in closing costs. Entry-level options exist below the median but move quickly when priced well; newer construction pushes above it. Do your lender shopping early, keep your contingencies, and don't confuse Jerome's current buyer-friendliness with a market where you can move slowly on a well-priced home.
Quick Takeaways & FAQs
✅ Jerome's median sale price of $351,000 (Redfin, May 2026) remains noticeably below what comparable Idaho markets are asking, giving first-timers real purchasing power without leaving the Magic Valley.
⚠️ Homes in Jerome currently average about 53 days on market and sell roughly 3% below list price — negotiating room that didn't exist during the 2021–2022 peak, but it disappears fast on well-priced, move-in-ready listings.
📍 Idaho is a title-company state, so your closing happens at a title office — and your lender must give you a final settlement statement at least three business days before that date, giving you time to catch any last-minute fee changes.
What credit score do I need to buy a home in Jerome, Idaho?
What are current mortgage rates in Idaho for first-time buyers?
How long does it take to buy a home in Jerome, Idaho?
Is it a buyer's or seller's market in Jerome right now?
What is the property tax rate for homeowners in Jerome, Idaho?
Moving to Idaho?
Tell us what you need help with and we'll connect you with local resources.
