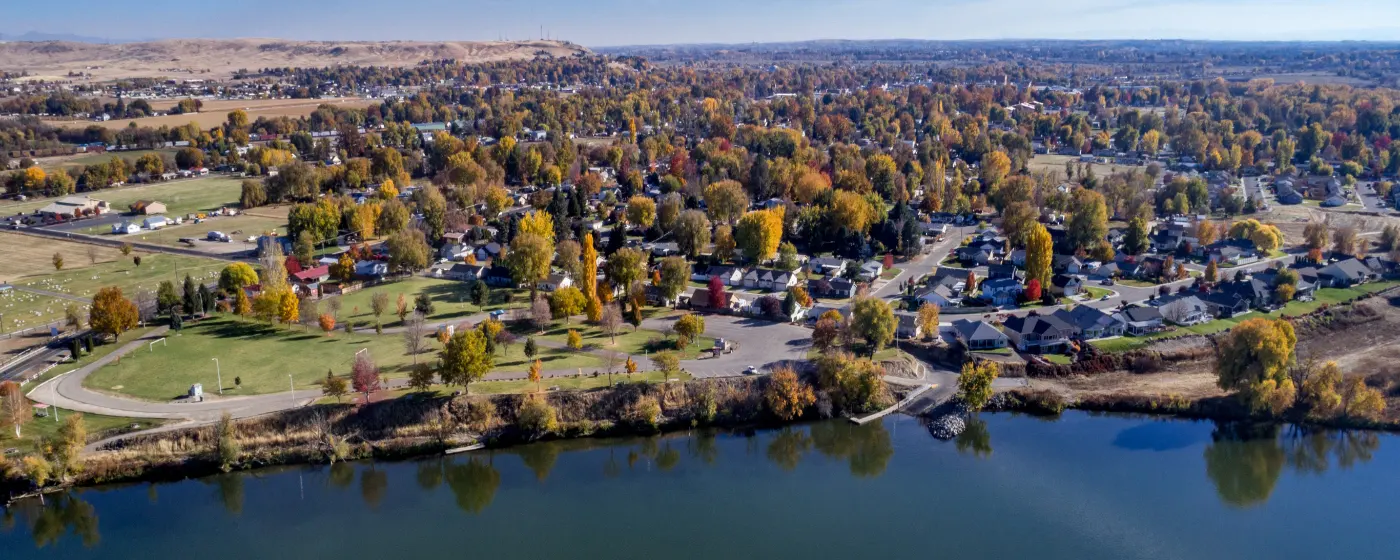
Maybe someone told you Payette was the affordable answer to a Treasure Valley market that had priced you out. Maybe your employer is in the region and you're looking west of Boise for something you can actually afford on one income. Either way, the first thing to understand is that Payette sits at an interesting moment: the Zillow Home Value Index places the typical home at $353,113 — meaningfully below what you'd pay in Meridian or Nampa — but the income picture here is tighter too, with a median household income of $55,208. That gap is the central math problem every first-time buyer in this market has to solve before they fall in love with a listing.
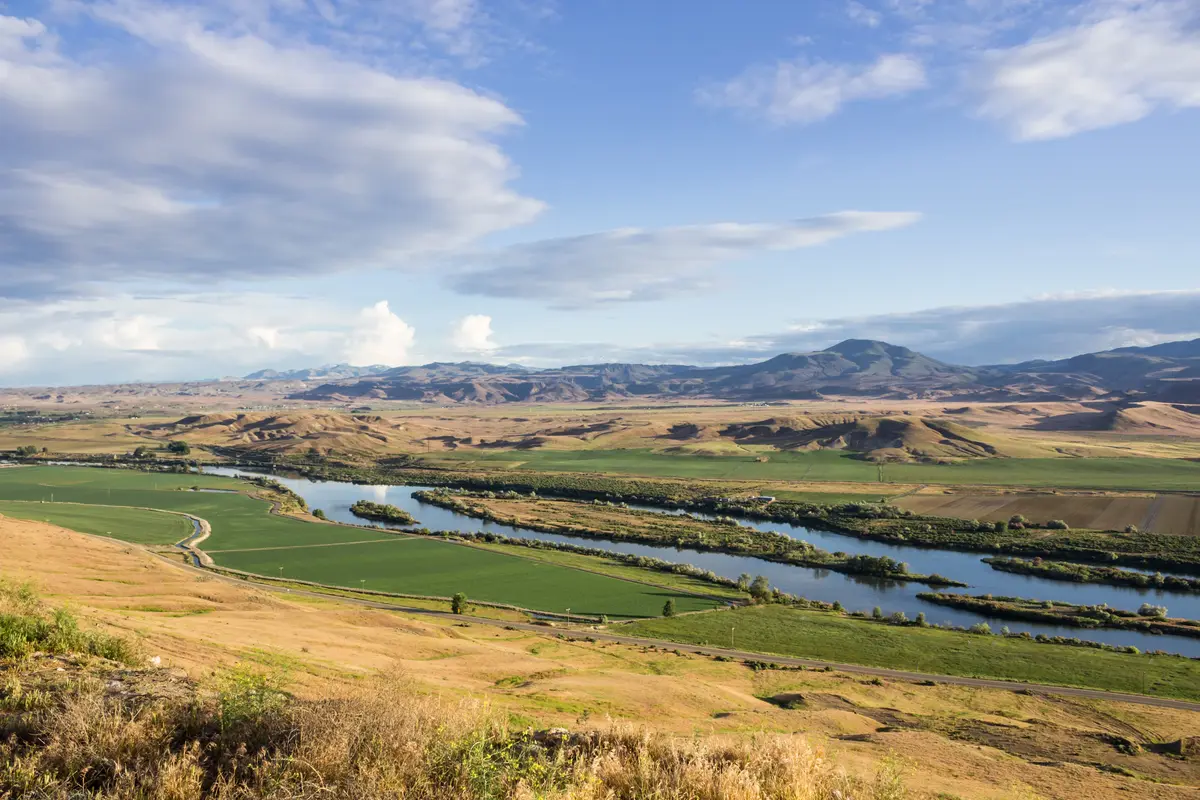
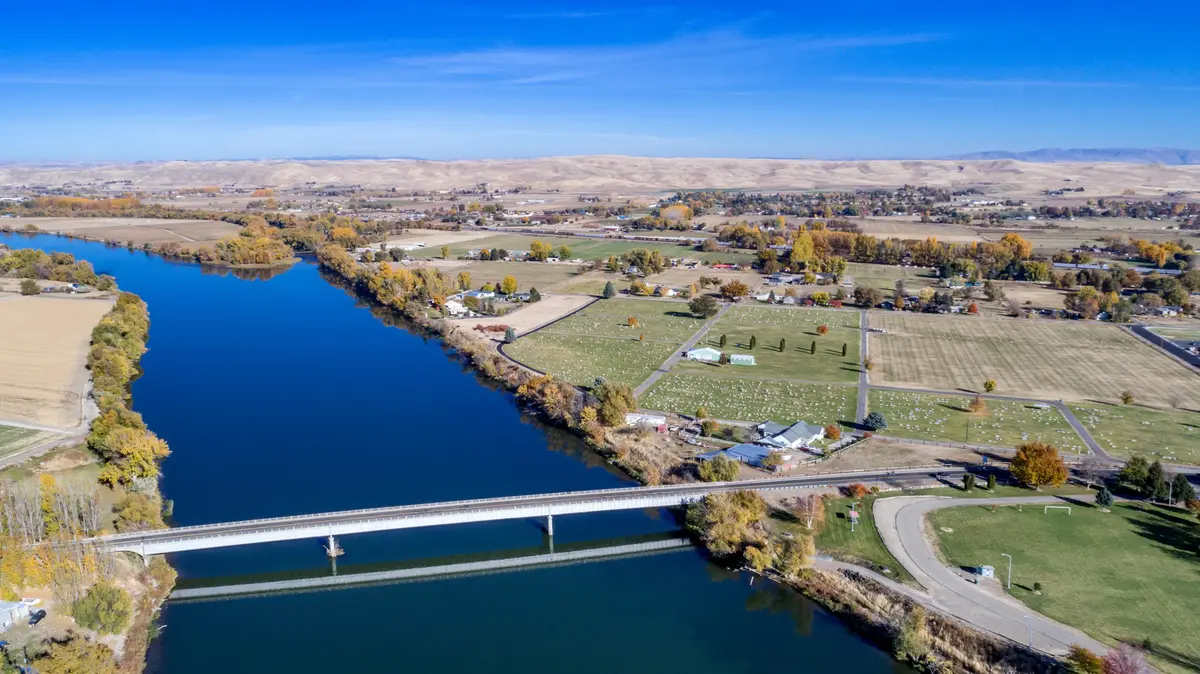
Payette sits along the Snake River at the western edge of Idaho, about 50 minutes from Boise via US-95 and I-84. The city of roughly 9,000 people runs on a mix of agricultural operations, food processing at Dickinson Frozen Foods, and manufacturing at Woodgrain Millwork — employers that lenders look at favorably because they reflect stable, long-term employment patterns. That stability matters when you're qualifying for a mortgage. The Treasure Valley's broader growth has pushed buyers further out, and Payette has absorbed some of that pressure: homes that sat for 79 days the prior year were moving in 15 days by May 2025, a shift that caught more than a few unready buyers off guard.
The affordability case for Payette is real, but it requires honest budgeting. Inventory has grown — 55 active listings in June 2025, up sharply from the month before — which gives buyers more breathing room than they had a year ago. But the market is still moving, and first-timers who shop without a pre-approval letter or underestimate closing costs tend to lose to buyers who did their homework first. Payette's effective property tax rate of approximately 0.35% is well below the national average, which helps on the monthly side once you're in. Getting there is the challenge this guide addresses.
The sections below walk through what your budget actually buys in Payette right now, the local homebuying process step by step, an honest affordability snapshot table, and the specific mistakes that trip up first-time buyers in this market.
The Payette First-Time Buyer Reality
The Zillow Home Value Index for Payette sits at $353,113 as of 2026 — and that figure deserves some unpacking before you set your search filters. It represents the typical home across all conditions and sizes. Entry-level inventory — older properties that need cosmetic work — tends to come in noticeably below that figure, which is where most first-time budgets actually land.
The honest tension: at the median household income of $55,208, qualifying for a loan at the full Zillow Home Value Index price requires careful debt management and a meaningful down payment. Most lenders want your total debt-to-income ratio — including the new mortgage — at or below 43% of gross monthly income. Current 30-year fixed rates for Payette-area buyers are running in the 6.5–7% range.
Competition has softened compared to 2023 and early 2024, but don't mistake a slower market for a buyer's free pass. Well-priced, move-in-ready homes still attract multiple offers. The properties that sit — averaging 75 days on market — are typically overpriced, have deferred maintenance, or both. Knowing the difference between a value opportunity and a money pit is one of the most important skills a first-time buyer in Payette can develop, and it starts with a thorough inspection. For a fuller picture of who this city suits and what daily life looks like here, see the living in Payette overview.
The Homebuying Process in Payette, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
Sellers in Payette strongly favor offers accompanied by a lender pre-approval letter. Submitting an offer without one doesn't just weaken your position — it often disqualifies you from consideration entirely when a competing offer arrives with documentation in hand. Pre-approval is not a formality you handle after finding the right house. It's the starting line.
Expect lenders to verify at least two years of stable employment history and a debt-to-income ratio at or below 43%. Gather your W-2s, recent pay stubs, two months of bank statements, and your last two federal tax returns before your first lender call. FHA loans are a common entry point in Payette's price range, with more flexible qualification criteria and low down payment options — worth discussing with your lender early.
Step 2: Define Your Search With a Local Agent
Payette's neighborhoods are small enough that an agent who works this market regularly will know which blocks carry unpermitted additions and which streets have aging infrastructure that affects insurability. That local knowledge matters more in a small market than in a large one where data is abundant.
Step 3: Make an Offer — With the Right Contingencies
In a softening market, you generally have room to include an inspection contingency. Do not waive it. Payette has older housing stock, and the inspection is the moment that separates an honest deal from an expensive surprise. An appraisal contingency protects you if the home doesn't appraise at the purchase price — particularly relevant if you're offering above list on a competitive property.
Step 4: Inspection and Appraisal
Your lender orders the appraisal; you hire the inspector. The two serve different purposes. The appraisal tells the lender what the home is worth as collateral. The inspection tells you what the home actually is. Budget $350–$500 for a standard inspection in this area. If the inspector flags the roof, HVAC, or foundation, that's negotiating leverage — or a reason to walk.
Step 5: Final Review and Closing Day
Once your lender issues a clear-to-close, you'll receive a final loan disclosure document at least three business days before closing. Read it line by line and compare it to your original Loan Estimate. Idaho closings typically run 30–45 days from accepted offer, though some lenders serving the Payette area can move faster when the file is clean. The step most first-timers get wrong here: not having the closing cash — down payment plus closing costs — wired or certified well in advance. Personal checks are not accepted at closing.
How Much Home Can You Afford in Payette
The table below shows estimated cash requirements at different purchase price points common to the Payette market. Closing costs are estimated at 2–5% of the loan amount; the actual figure depends on your lender, title company, and loan type. These are illustrative estimates — not lender quotes — and your situation will vary based on credit score, rate, and the specific property.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5% down) — entry-level | $260,000 | $9,100 (3.5%) | $6,300–$12,600 | ~$15,400–$21,700 |
| FHA (3.5% down) — mid-range | $315,000 | $11,025 (3.5%) | $7,600–$15,200 | ~$18,600–$26,225 |
| Conventional (3% down) — entry-level | $260,000 | $7,800 (3%) | $6,300–$12,600 | ~$14,100–$20,400 |
| Conventional (5% down) — mid-range | $315,000 | $15,750 (5%) | $7,400–$14,800 | ~$23,150–$30,550 |
| Conventional (10% down) — at ZHVI median | $353,113 | $35,311 (10%) | $7,900–$15,800 | ~$43,211–$51,111 |
| Conventional (20% down) — avoid PMI | $353,113 | $70,623 (20%) | $6,700–$13,400 | ~$77,323–$84,023 |
* ZHVI = Zillow Home Value Index.
The 20%-down row illustrates the real cost of avoiding private mortgage insurance at Payette's typical price point — it requires a cash reserve most first-time buyers are still building. The FHA entry-level row is where many local first-timers realistically start.
One number the table can't show: your ongoing ownership cost. Payette's effective property tax rate of approximately 0.35% is among the lower rates you'll find in comparable Idaho markets, which helps. Use the mortgage calculator below this section to model your specific principal-and-interest payment once you have a real purchase price and rate quote from a lender.
Looking to buy in Payette? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Payette quote.
Common First-Time Buyer Mistakes in Payette
Mistake 1: Touring Homes Before You Have a Pre-Approval Letter
This is the most common and most costly misstep in Payette's market. Buyers who fall in love with a house and then scramble to get pre-approved routinely lose it to a buyer who walked in the door ready. Pre-approval typically takes 3–5 business days; start before you start scrolling listings.
Mistake 2: Waiving the Inspection Contingency to Compete
Some buyers, spooked by the 2022–2023 frenzy, assume they still need to waive contingencies to win. In today's softened Payette market, that's rarely true — and waiving an inspection on older housing stock is a significant financial risk. Deferred maintenance on roofing and plumbing is common in the city's older inventory. Keep your inspection contingency.
Mistake 3: Underbudgeting the Cash Needed at Closing
First-timers consistently focus on the down payment and forget that closing costs — appraisal, title insurance, escrow, prepaid homeowners insurance, and prepaid interest — add another $6,000 to $15,000 on a typical Payette purchase. Showing up to closing light on funds doesn't pause the transaction; it kills it. Budget the full range from the table above, not the low end.
Mistake 4: Ignoring the Commute Math If You Work in Boise
Payette is approximately 50 minutes from Boise under normal conditions — but that's one way, on a good day. Buyers who purchase near the US-95 corridor shave a few minutes off relative to other parts of town. If your job requires daily Boise presence, factor in roughly two hours of daily drive time and the associated fuel cost before deciding the lower home price makes the math work. Some buyers who moved here for the price find after six months that the commute changes the whole equation.
Local Expert Takeaway: Payette rewards first-time buyers who do their paperwork before they do their browsing. Get your pre-approval letter in hand, have your closing cash — down payment plus estimated closing costs — sitting in a verified account, and don't skip the inspection on older inventory. The lower home prices here are real, and Payette's 0.35% effective property tax rate makes the monthly picture more manageable than the sticker price alone suggests. But the income-to-price gap means you may need to target well below the Zillow Home Value Index median to keep your debt-to-income ratio in a lender-friendly zone.
Quick Takeaways & FAQs
✅ Payette's Zillow Home Value Index of $353,113 sits noticeably below comparable Treasure Valley cities, giving first-time buyers a genuine entry-point advantage in Idaho's hottest region.
⚠️ The median household income of $55,208 creates a real affordability stretch at the full median price — most first-time buyers will need to target a lower price range to keep debt-to-income ratios lender-friendly.
📍 Sellers here expect a pre-approval letter with every offer — touring without one is the single fastest way to lose a house you want in Payette.
What credit score do I need to buy a home in Payette, Idaho?
How long does it take to close on a house in Payette?
Is Payette a buyer's market or a seller's market right now?
What are closing costs in Payette, Idaho?
Is it worth buying in Payette if I commute to Boise?
Moving to Idaho?
Tell us what you need help with and we'll connect you with local resources.
