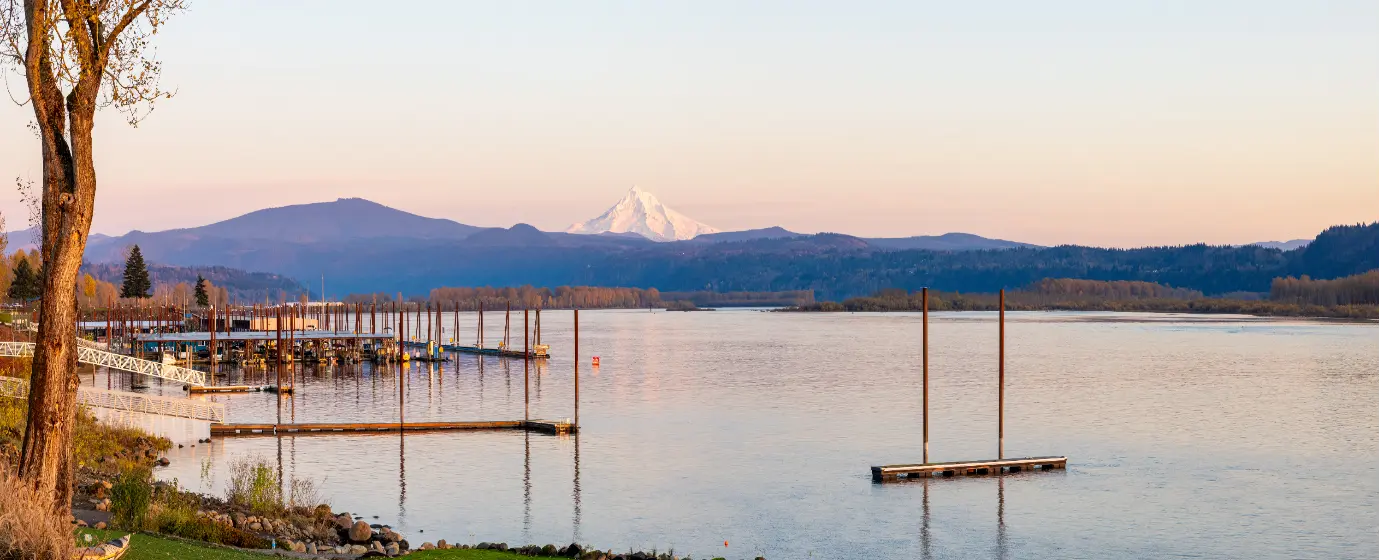
Maybe you've been priced out of Camas and someone pointed you east along SR-14. Maybe you did the math on Vancouver and Washougal kept coming up as the one place where a median household income still reaches a front door. Either way, you've landed on a city that sits in a genuinely useful middle ground: priced noticeably above Vancouver but well below Camas, tucked against the Columbia River with the Washougal River running along its edge, and close enough to Portland — roughly 30 minutes on a clear day — to make a cross-river commute real. The Zillow Home Value Index put the city median at $589,780 in June 2026, a figure that's moved only slightly downward over the past year. That relative stability is part of the draw, and part of the pressure.
Washougal is a working city, not a resort town playing at being a suburb. Pendleton Woolen Mills has operated here for generations and remains a tangible anchor of local identity. The city itself — along with the retail sector along Washougal's main commercial corridors — rounds out the local employment picture. The people buying here tend to be households who want genuine square footage, river-valley access, and lower costs than Camas next door, without giving up a reasonable commute. For a fuller picture of who Washougal suits, the community overview covers the full range of buyer types and lifestyles.
From a cost-of-living standpoint, Washington's lack of a state income tax reshapes the budget math for anyone relocating from Oregon or California. The effective property tax rate here runs approximately 0.84%, which is on the lower end for the Pacific Northwest. The full cost-of-living breakdown covers taxes, utilities, and day-to-day expenses in detail. What the numbers don't show is that Washougal is actively investing in its own infrastructure — a revitalized Town Center park opened downtown in spring 2026, fire and police station construction is underway, and a grade separation project at 32nd Street is designed to untangle one of the busiest rail crossings in the state.
Whether you're writing your first offer or just figuring out how much house your income can actually reach, the sections below break down the Washougal first-time buyer reality, walk through the purchase process step by step, model out realistic budget scenarios, and name the mistakes that cost local first-timers the most.
The Washougal First-Time Buyer Reality
With a city-wide Zillow Home Value Index of $589,780 as of June 2026, Washougal is not a starter-home market in the traditional sense. Entry-level inventory — think older ranch-style homes, smaller lots, or properties needing cosmetic work — starts closer to the low-to-mid $400s when it appears, but those listings move fast and compete hard. The honest entry point for a move-in-ready detached home with a yard currently runs in the $480,000–$550,000 range, and that bracket requires real cash at the table.
The inventory picture makes this harder. As of June 2026, Washougal had just 14 active listings and a seller's market reading of 3.8 months of supply. Homes were sitting a median of 34 days before going under contract, and sellers were collecting 98.4% of their asking price on average. That's not a bidding-war environment — buyers typically see about two offers competing on a given home — but it is a market where lowball offers go nowhere and hesitation costs you the house.
New construction offers a meaningful alternative. As of August 2026, 16 new-build homes were listed for sale in Washougal, giving first-timers a chance to sidestep the inspection anxiety of older resale inventory and sometimes lock in builder incentives. The catch is that new construction often sits in developing areas farther from the downtown core, and builder timelines add complexity if you're trying to coordinate the move with a lease end. A housing forecast estimates the city needs roughly 1,228 additional units over the next five years to keep pace with growth — which means demand pressure isn't going away soon, and waiting for prices to soften significantly is a real gamble.
The Homebuying Process in Washougal, Step by Step
Step 1: Get Pre-Approved Before You Look at a Single Listing
In a market with 14 active listings, showing up without a pre-approval letter is the fastest way to lose a home you actually wanted. Washougal sellers — and their agents — take pre-approval as a baseline, not a courtesy. Get it done before your first weekend of open houses, and make sure it's a full pre-approval (credit pulled, income documented) rather than a soft pre-qualification letter that any seller's agent will see through immediately.
Washington state's 30-year fixed mortgage rate was approximately 6.75% as of late August 2026, with 15-year fixed options at around 6.125%. Run your numbers at the current rate before you fall in love with a price point — the monthly payment on a $590,000 purchase looks very different at 6.75% than it did two years ago.
Step 2: Find a Local Agent Who Knows Clark County
Washougal is small enough that an agent who primarily works Vancouver or the Portland side of the river may not have the local relationships that matter when inventory is this tight. Ask specifically whether they've closed deals in Washougal in the past six months, not just Clark County broadly.
Step 3: Tour Properties and Write Offers Decisively
At 34 days on market, you typically have a window — but it's not a leisurely one. Build your must-have list before you start touring so you're not making your criteria up in real time during an open house. When the right home appears, be ready to write within 24–48 hours.
One thing first-timers consistently underestimate here: the offer package matters as much as the number. A clean offer — pre-approval attached, inspection period reasonable but not exaggerated, earnest money at or above 1% of purchase price — reads as credible to a Washougal seller even if it's not the highest dollar offer on the table.
Step 4: The Inspection and Appraisal Window
Washington state standard purchase agreements give buyers an inspection period, typically 10 business days, to review the property's condition and negotiate repairs or credits. Do not waive this for a Washougal resale — older homes near the river corridor or on hillside lots can carry drainage, foundation, or moisture issues that aren't visible on a walkthrough. The inspection contingency is your clearest exit ramp if something serious surfaces.
The appraisal happens on the lender's timeline, usually within the first two weeks after mutual acceptance. With sellers getting 98.4% of asking price, appraisal gaps are less common than in hotter markets, but they do happen on homes priced at the higher end of the local range. Know before you write whether you have cash to cover a gap or whether your offer needs an appraisal contingency to protect you.
Step 5: Closing
Washington state closings are handled through escrow companies, not attorneys — so you'll sign with an escrow officer, not at a law office. Title review, final walk-through, and signing typically happen within 30–45 days of mutual acceptance. Budget time to review the Closing Disclosure carefully; first-timers often skim it and then get surprised at the table by prepaid items (first year's homeowner's insurance, prepaid interest) that are real costs, not errors.
How Much Home Can You Afford in Washougal
Closing costs in Washington typically run 2%–3% of the purchase price, covering lender fees, title insurance, escrow fees, and prepaid items. Your total cash needed at closing is your down payment plus those costs — and that combined figure is where many first-time buyers find themselves short after months of saving only toward the down payment.
The table below models five realistic scenarios for Washougal buyers. Figures are estimates using approximate closing costs of 2.5% of the purchase price. Actual costs vary by lender, title company, and transaction specifics — use these as planning anchors, not final numbers. The interactive calculator below this section runs personalized payment estimates at current rates.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (~2.5%) | Est. Total Cash Needed |
|---|---|---|---|---|
| FHA Minimum (3.5%) — Entry Level | $440,000 | $15,400 (3.5%) | ~$11,000 | ~$26,400 |
| Conventional (3%) — Entry Level | $440,000 | $13,200 (3%) | ~$11,000 | ~$24,200 |
| FHA Minimum (3.5%) — Mid Range | $530,000 | $18,550 (3.5%) | ~$13,250 | ~$31,800 |
| Conventional (3%) — Mid Range | $530,000 | $15,900 (3%) | ~$13,250 | ~$29,150 |
| Conventional (5%) — Near Median | $590,000 | $29,500 (5%) | ~$14,750 | ~$44,250 |
| Conventional (10%) — Near Median | $590,000 | $59,000 (10%) | ~$14,750 | ~$73,750 |
A few things this table makes plain: getting to the table on a $530,000 home with a conventional loan still requires roughly $30,000 in liquid savings, even before you account for moving costs and any immediate repairs. FHA loans require mortgage insurance premiums that add to monthly carrying costs, while conventional loans with less than 20% down carry private mortgage insurance — both are real line items that the calculator below will factor into your payment estimate.
Washington has no state income tax, which meaningfully improves take-home pay compared to Oregon or California — a factor worth running through your budget if you're relocating across the river from the Portland side. The city's effective property tax rate of approximately 0.84% is relatively low for the Pacific Northwest; the full tax picture lives on the cost-of-living page.
Looking to buy in Washougal? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Washougal quote.
Common First-Time Buyer Mistakes in Washougal
Mistake 1: Shopping Before the Pre-Approval Is Complete
This is the most common and most costly mistake in any competitive market, and Washougal's thin inventory makes it especially punishing. With 14 active listings, the gap between "I should get pre-approved" and "that house I wanted went pending" can be as short as a weekend. Get the letter first. Tour second.
Mistake 2: Waiving the Inspection Contingency to Compete
Some buyers, frustrated after losing a home or two, start mimicking the tactics they hear about in Portland's hotter submarkets — including waiving inspections entirely. Don't do this in Washougal. The housing stock here includes hillside lots with drainage complexity, older construction near the river corridor, and homes where deferred maintenance isn't visible at a showing. The inspection contingency costs you nothing to keep and can save you tens of thousands. A tighter inspection timeline (7 business days instead of 10) is a smarter way to sharpen your offer without eliminating your protection.
Mistake 3: Ignoring the 32nd Street Rail Crossing
Buyers looking at homes on the eastern edge of Washougal — particularly anything that relies on 32nd Street for daily egress — should understand what they're buying into. The BNSF rail crossing at 32nd Street averages 32 trains and nearly 6,000 vehicles per day, making it one of the busiest at-grade crossings in Washington state. A grade separation project is in planning and utility-relocation phase with full construction expected in 2027. Until that project is complete, the crossing creates real commute variability. If your daily route depends on it, build extra time into your trial commute before you write an offer.
Mistake 4: Underestimating the Total Cash Required
Most first-timers budget for the down payment and stop there. The closing cost line — typically 2%–3% of purchase price in Washington — adds $11,000 to $18,000 to what you need liquid on closing day, on top of the down payment. Then add the first year of homeowner's insurance (paid upfront at closing), prepaid mortgage interest, and any immediate move-in expenses. On a $530,000 home, the total cash needed at the table can realistically exceed $30,000 even with a minimum down payment. Buyers who don't model this out in advance end up either scrambling for funds in the final two weeks or asking for seller concessions that weaken their offer. Build the full closing cost estimate into your savings target from day one.
One more thing that surprises people in their first six months here: Washougal's community is genuinely small-town in feel, which means your neighbors and the person behind you at the downtown coffee spot may all know each other before you do. That's a real asset once you're settled — but it does mean that skipping due-diligence steps (inspection, title review, survey if the lot lines are unclear) and then having a problem become public knowledge happens faster here than it would in a larger city. Do the homework before you close.
Local Expert Takeaway: Washougal rewards first-time buyers who show up prepared — pre-approved, clear on their cash position, and realistic about what $440,000–$590,000 actually buys in a market with 14 active listings. The 32nd Street rail crossing is the one local friction point worth building into your commute math before you write an offer on the east side of town. New construction gives you a meaningful alternative to resale if the inspection anxiety of older inventory feels like too much risk at this price point. Post-close, the downtown core is genuinely improving — the new Town Center park and a growing stretch of locally owned spots along E Street and Evergreen Way are real signs of a city investing in the kind of walkable social life that makes a neighborhood feel like home.
Quick Takeaways & FAQs
✅ Washougal sits noticeably below Camas on price while offering similar Columbia River Valley access, making it a practical first purchase for households priced out of the neighboring city.
⚠️ With only 14 active listings as of June 2026 and sellers receiving 98.4% of asking price, this is not a market where arriving without a pre-approval letter gives you any real chance at a competitive home.
📍 The 32nd Street BNSF rail crossing — averaging 32 trains daily — is a genuine commute variable for buyers on the eastern edge of the city until the grade separation project reaches full construction, expected in 2027.
What is the minimum down payment to buy a home in Washougal, WA?
How competitive is the Washougal housing market for first-time buyers?
Is it better to buy a new construction home or a resale in Washougal?
How long does it take to close on a home in Washougal, WA?
Should I worry about the 32nd Street rail crossing when buying in Washougal?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
