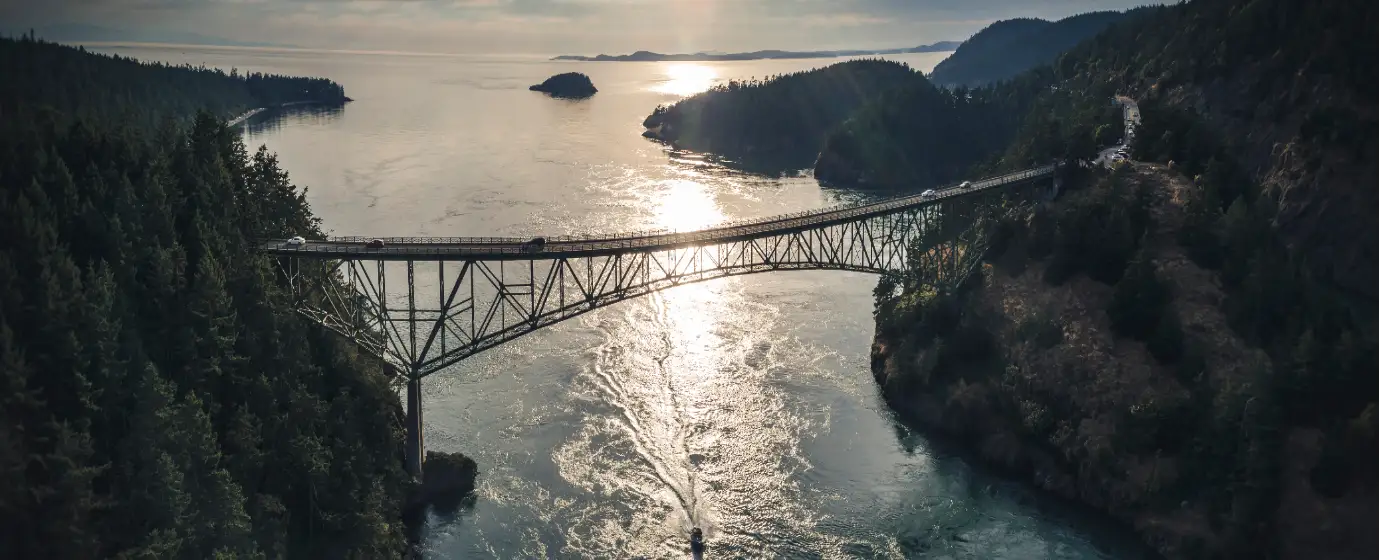
Maybe you've been renting in Oak Harbor for a year and finally feel ready to buy. Maybe you're moving here for a military assignment and the VA benefit makes ownership feel suddenly within reach. Either way, you're entering a market that behaves differently from most Washington cities its size — shaped less by tech-sector demand and more by the rhythms of Naval Air Station Whidbey Island, a military base that drives consistent, year-round housing pressure in a town of roughly 24,000 people. The Deception Pass Bridge is the only road on or off the north end of Whidbey Island, and that geographic reality defines everything: inventory is structurally limited, and demand spikes predictably every spring when Permanent Change of Station (PCS) orders arrive.
The typical home value in Oak Harbor sits at $485,449 (Zillow Home Value Index, June 2026) — well below Seattle or Everett, but not the entry-level market some newcomers expect when they see it on a map. The market scored 76 out of 100 on Redfin's competitiveness scale, and in early 2026 available inventory hovered around 1.74 months of supply — less than half of what's considered a balanced market. Homes typically go under contract in about 28 days. For a first-time buyer still getting familiar with the process, that pace is genuinely challenging. The good news: inventory on North Whidbey rose roughly 16% in early 2026 compared to the prior year, which means you have slightly more breathing room than buyers faced in 2022 or 2023. See the full cost-of-living breakdown for context on how Oak Harbor prices stack up against nearby markets.
On the financing side, Oak Harbor is one of the few small cities in Washington where VA loans — which require zero down payment and no private mortgage insurance — are genuinely the dominant financing tool, not just an option. Island County's FHA loan limit for 2026 is $671,600, which comfortably clears the typical home value and keeps FHA a realistic path even here. The housing stock ranges from condos at the lower end of the market up to $800,000-plus for waterfront builds, so the price spread is real and there are options across that range for buyers with a clear financing plan.
This guide covers what a first-timer's budget actually buys in Oak Harbor right now, the step-by-step purchase process with the specific missteps locals see most often, an honest affordability table for several realistic scenarios, and the four mistakes that cost first-time buyers the most in this market.
The Oak Harbor First-Time Buyer Reality
At $485,449 as the typical home value (Zillow Home Value Index, June 2026), Oak Harbor is not a cheap market — but it is a reachable one for buyers with stable income and a clear financing plan. The median closed sale price for single-family homes over the six months ending February 2026 was $538,250, which tells you that the homes actually transacting skew above the typical value. First-time buyers competing at the lower end of the market are often in the most crowded price band.
A buyer who is flexible on square footage, finish level, or location will find more options and face less competition than one locked into a specific neighborhood or style. The catch is that lower-priced listings move fast, often faster than the market-wide 28-day average, because investor buyers and VA buyers without a financing contingency are frequently in the same pool.
The PCS cycle is the one dynamic that genuinely surprises first-time buyers who moved here from a mainland city. Every spring, a fresh wave of military families arrives on Whidbey with housing allowances and, often, VA eligibility — compressing both inventory and timelines in a matter of weeks. If you are planning to buy in April, May, or June, expect the most competitive conditions of the year. Shopping in late summer or fall typically means less competition and more negotiating room, though inventory is lower too. Knowing that rhythm, and timing your pre-approval accordingly, is one of the most practical edges a first-time buyer here can have.
The Homebuying Process in Oak Harbor, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
In a market where homes go under contract in roughly 28 days, showing up at an open house without a pre-approval letter is a wasted trip. Oak Harbor sellers — especially those fielding multiple offers from military buyers with VA financing already lined up — will not take a non-pre-approved offer seriously. Multiple locally licensed lenders operate here, including branches of Guild Mortgage, Envoy Mortgage, and PrimeLending at 32650 SR 20, plus independent brokers on the island. Shopping at least two lenders is worth your time; rates and fee structures vary more than most first-timers expect.
Step 2: Define Your Loan Type Early
VA, FHA, and conventional each have different seller perceptions in this market. VA loans close reliably when the buyer is organized, but some sellers — particularly those who had a prior VA deal fall apart at appraisal — carry skepticism. FHA loans carry a similar reputation risk around appraisal requirements. If you are using FHA or VA financing, your agent's ability to frame the offer and communicate with the listing agent matters as much as the price itself. Island County's 2026 FHA loan limit of $671,600 keeps FHA workable at nearly every price point in Oak Harbor.
Step 3: Make Offers Quickly, But Not Carelessly
The first-time buyer mistake in a fast market is confusing urgency with recklessness. Moving quickly on an offer is smart. Waiving your inspection contingency on a 1960s rancher because you're afraid of losing it is not — and Oak Harbor has a meaningful supply of older homes where deferred maintenance is common. Write a clean, competitive offer, but keep the inspection.
Step 4: The Inspection and Appraisal Window
Washington State gives buyers a standard inspection period — typically five to ten business days in local contracts. Use all of it if the home warrants it. Appraisals in Oak Harbor have historically been a friction point when offers come in well above list price: if the appraisal comes in low and you have no appraisal gap coverage written into the offer, you're either renegotiating or bringing more cash to close. First-time buyers should discuss appraisal gap strategy with their agent before making any offer above asking.
Step 5: Closing
Washington is an escrow state — a title and escrow company handles the closing, not an attorney. Closings in Island County typically take 30 to 45 days from mutual acceptance. Your lender is required to issue a final closing disclosure at least three business days before signing, which is your first look at the itemized cash-to-close figure. Review it against your original Loan Estimate and flag any line items that changed unexpectedly before you sit down at the table.
How Much Home Can You Afford in Oak Harbor
Washington State closing costs typically run 2–3% of the purchase price, covering title insurance, escrow fees, lender origination charges, and prepaid items like homeowners insurance. The table below shows estimated cash requirements — down payment plus closing costs — at several realistic Oak Harbor price points. These are approximations; your lender's Loan Estimate will give you the precise figures for your scenario.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–3%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA 3.5% — entry condo | $320,000 | ~$11,200 (3.5%) | ~$6,400–$9,600 | ~$17,600–$20,800 |
| Conventional 3% — entry condo | $320,000 | ~$9,600 (3%) | ~$6,400–$9,600 | ~$16,000–$19,200 |
| FHA 3.5% — typical value | $485,449 | ~$17,000 (3.5%) | ~$9,700–$14,600 | ~$26,700–$31,600 |
| Conventional 3% — typical value | $485,449 | ~$14,600 (3%) | ~$9,700–$14,600 | ~$24,300–$29,200 |
| Conventional 5% — near median closed | $538,000 | ~$26,900 (5%) | ~$10,800–$16,100 | ~$37,700–$43,000 |
| Conventional 10% — near median closed | $538,000 | ~$53,800 (10%) | ~$10,800–$16,100 | ~$64,600–$69,900 |
The effective property tax rate in Oak Harbor is approximately 0.73% — on the lower end for Washington State, which helps monthly carrying costs. The interactive calculator below this section will let you model specific monthly payment scenarios using these purchase prices.
One number first-timers consistently underestimate: the cash reserve lenders want to see after closing. Most loan programs expect one to three months of housing payments remaining in your account at close. Budget for that buffer before you decide what purchase price is genuinely comfortable.
Looking to buy in Oak Harbor? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Oak Harbor quote.
Common First-Time Buyer Mistakes in Oak Harbor
Mistake 1: Shopping Before Pre-Approval
This one costs buyers deals, not just time. In Oak Harbor's fast market, the gap between a verbal pre-qualification and a full pre-approval letter — with income documentation reviewed and credit pulled — can mean losing a home you've already mentally moved into. Get the full pre-approval, not just a pre-qualification estimate, before you book a single showing.
Mistake 2: Waiving the Inspection on Older Homes
The temptation is real when you've lost two offers. But a significant portion of Oak Harbor's housing stock was built in the 1960s through 1980s — homes that can carry aging electrical panels, moisture issues from the marine climate, and deferred maintenance that isn't visible at a showing. Waiving the inspection on a 55-year-old home on Whidbey Island to compete with a cash offer is a risk that tends to look much worse after move-in. A better strategy: write a shorter inspection period (five business days instead of ten) to signal responsiveness without eliminating your protection entirely.
Mistake 3: Ignoring the Island Access Reality Before Committing
Buyers who fall in love with Oak Harbor's price point and then discover what a daily commute to Everett or Seattle actually involves — roughly 60 minutes each way on a good day, with no alternative if Deception Pass Bridge has an incident — sometimes regret the decision within a year. This is one of the most common reasons people move out. Before you close, drive the route at your actual commute time, not on a Saturday afternoon. If your employer is in Everett and you're not working remotely, that daily crossing needs to feel acceptable, not just tolerable in theory.
Mistake 4: Underestimating Total Cash at Close
First-time buyers frequently calculate down payment and forget about the rest. In Washington, closing costs are real and itemized — title insurance alone on a $485,000 purchase runs several hundred dollars, and when you add escrow fees, lender origination, prepaid homeowners insurance, and the first property tax installment, the gap between "down payment" and "cash I actually need" can be $10,000 or more. Ask your lender for a detailed Loan Estimate before you make an offer, so the final settlement statement doesn't surprise you three days before signing.
Local Expert Takeaway: Oak Harbor rewards first-time buyers who treat preparation as a competitive advantage. Get fully pre-approved before you tour, understand which loan type fits your situation (VA if you're eligible, FHA if you're not, conventional if your down payment can absorb it), and time your search to avoid the peak PCS window in April through June if competition matters more to you than selection. The market isn't as punishing as Seattle, but it's tight enough that buyers who show up with clean financing and realistic expectations will beat buyers who show up enthusiastic but unprepared. Talk to a local lender and drive the Deception Pass Bridge at your actual commute time before you make any offers — the crossing puts everything in perspective.
Quick Takeaways & FAQs
✅ Island County's 2026 FHA loan limit of $671,600 comfortably covers Oak Harbor's typical home value, keeping low-down-payment financing genuinely accessible for first-time buyers here.
⚠️ The PCS transfer cycle tied to NAS Whidbey Island compresses inventory every spring — April through June is the most competitive window of the year, and first-time buyers without a pre-approval letter will struggle to compete.
📍 Entry-level condos in Oak Harbor can list well below the typical home value, but the homes actually closing have been transacting closer to $538,000 — budget for that gap before you decide what's realistic.
What credit score do I need to buy a home in Oak Harbor?
How long does it take to close on a house in Oak Harbor?
Is it better to use a VA loan or an FHA loan to buy in Oak Harbor?
What are closing costs in Oak Harbor, and who pays them?
What's the biggest mistake first-time buyers make in Oak Harbor specifically?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
