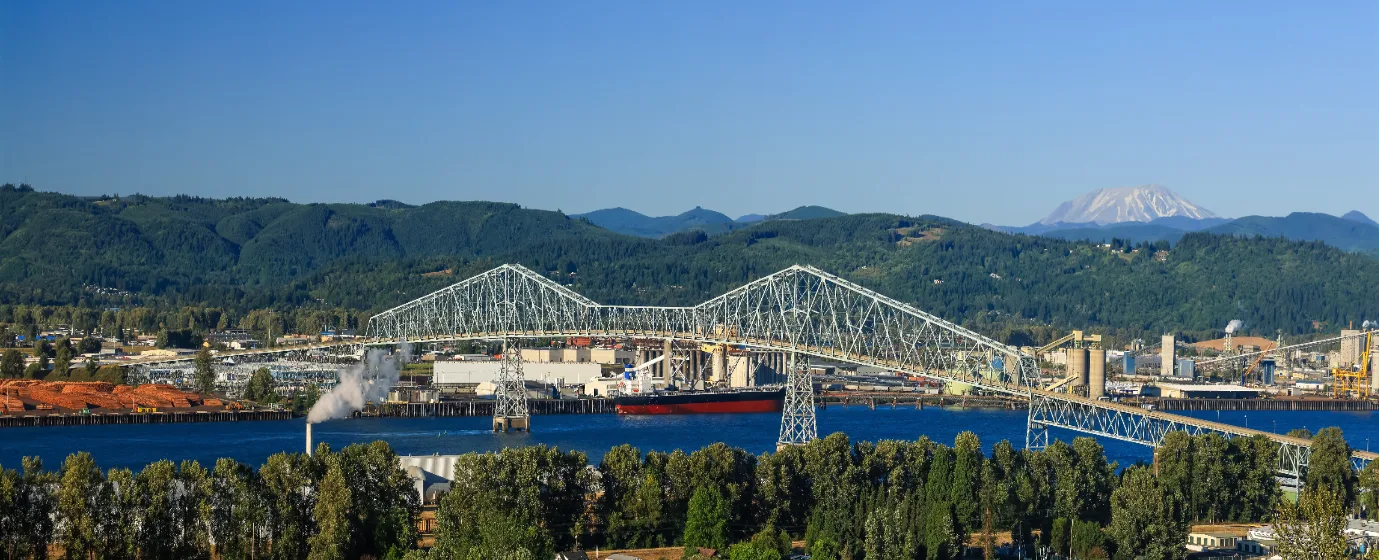
You've done the math and Longview looks promising — home prices noticeably below what Portland buyers face, no state income tax boosting your take-home pay, and a commute to the metro that's roughly 45 minutes on I-5. What the spreadsheet won't tell you is that Longview's market is genuinely competitive for a city this size. Redfin rated it 80 out of 100 — "very competitive" — as of mid-2026, with homes averaging around 15 days on market and roughly 100.1% of list price at closing. For a first-timer used to leisurely browsing Zillow on the weekend, that pace can sting.
The city's economy is anchored by a diverse mix of industrial and public-sector employers — including operations at the Port of Longview and major manufacturing facilities that have long shaped Cowlitz County's workforce — which means steady housing demand from workers who aren't going remote. That sustained local demand is part of why inventory stays thin: approximately 2.8 months of supply as of May 2026, firmly in seller's market territory. The Zillow Home Value Index for Longview sits at $374,268 (2026), and while that's a fraction of what Portland buyers pay, it's still roughly 6.1 times the city's median household income — higher than traditional affordability rules of thumb, which makes planning and pre-approval genuinely non-negotiable here.
The encouraging news: roughly 31% of listings have seen at least one price reduction, meaning not every home goes to a bidding war. Washington's lack of a personal income tax also improves real purchasing power for buyers relocating from California, Oregon, or other income-tax states. And the effective property tax rate here — approximately 0.87% — is well below the Washington state average, keeping long-term ownership costs manageable once you're in. See the full cost-of-living breakdown for how Longview compares on day-to-day expenses.
Whether you're considering your first purchase in Cowlitz County or trying to figure out how to compete in a market that moves faster than you expected, the sections below walk through what a first-timer's budget actually buys here, the step-by-step process, a budget snapshot table, and the specific mistakes local buyers most often regret.
The Longview First-Time Buyer Reality
The Zillow Home Value Index for Longview stands at $374,268 (2026) — but that median masks a wide range. Entry-level inventory, typically older construction in West Longview or Columbia Valley Gardens, starts in the low-to-mid $300,000s. Move closer to the Highlands or Beacon Hill and you're looking at the upper $300,000s to mid-$400,000s for updated ranches and split-levels. Below $300,000 exists, but those homes move the fastest and often need the most work.
The competitive pressure is real and specific. Zillow's data shows homes going to pending in around 8 days — not 8 business days. That means a home you tour on Saturday may already have multiple offers by Sunday afternoon. Roughly 30–32% of closed sales in the Longview metro area end above asking price. First-timers who haven't internalized that timeline often lose two or three homes before adjusting their approach.
The flip side: more than 31% of listings have had at least one price drop. That figure tells you this is not a uniformly frenzied market. Overpriced homes, homes in less desirable condition, or listings that hit in slower months genuinely do sit — and motivated sellers do negotiate. Your job as a first-timer is to be ready to move fast on the good ones and patient enough to wait out the overpriced ones. Pre-approval, a realistic budget, and a clear sense of your non-negotiables are what separate buyers who close in 60 days from buyers who are still searching at month six.
The Homebuying Process in Longview, Step by Step
Step 1: Get Pre-Approved Before You Look at a Single Home
Pre-approval is the step first-timers most often treat as a formality — something to handle after finding a home they love. In Longview, that sequencing will cost you. With homes going to pending in roughly 8 days, a seller won't wait 48–72 hours for you to scramble for a pre-approval letter. Many listing agents won't even schedule a showing for an unqualified buyer in a multi-offer environment.
Pre-approval means a lender has pulled your credit, reviewed your income documentation (W-2s, tax returns, pay stubs), and issued a conditional commitment. Pre-qualification — the quick online estimate — is not the same thing and carries almost no weight with sellers here. Get pre-approved with a lender who knows the Cowlitz County market before you set foot in an open house.
Step 2: Find a Local Buyer's Agent
A buyer's agent who works Longview and Kelso regularly will know which neighborhoods carry attendance-boundary complications, which streets near the industrial corridor affect long-term resale, and — critically — how to write an offer that competes without reckless concessions. Their fee is generally paid by the seller under traditional structure, though that arrangement has been evolving; confirm it upfront.
Step 3: Shop Within Your Approved Range
Tour homes at or slightly below your ceiling, not above it. Falling for a home $30,000 over your limit and then scrambling for a solution is one of the most common first-timer patterns in any market, and Longview's pace doesn't give you time to recover gracefully. Build a short list of must-haves vs. nice-to-haves before touring.
Step 4: Write a Competitive Offer
In a market where roughly 100.1% of list price is the average close, lowball offers on well-priced homes rarely land. Your agent will pull recent comparable sales — not list prices, but actual closed prices — to anchor your offer. Escalation clauses, strong earnest money (typically 1–2% of purchase price in this market), and a pre-approval letter from a recognized lender all matter. A short inspection period rather than no inspection at all is often a smarter competitive concession than waiving it entirely.
Step 5: Inspection, Appraisal, and Final Walk-Through
Washington state does not require a licensed home inspector by statute, but skipping inspection on a first purchase is almost always the wrong call. Many of Longview's housing stock dates from the 1950s–1970s; older plumbing, electrical panels, and roofing are common inspection findings. Budget $400–$600 for a general inspection; add a sewer scope (another $100–$200) on any pre-1980 home — lateral line issues on older Longview streets are a known cost item.
The appraisal is ordered by your lender and confirms the home's value supports the loan. The step first-timers underestimate here is the gap between the appraisal coming in and the clear-to-close: lender underwriting can take 2–3 weeks even after the appraisal is in hand. Plan your closing timeline accordingly and don't schedule a moving truck until you have a clear-to-close in writing.
Step 6: Closing
Washington uses escrow companies — not attorneys — to close real estate transactions. Your escrow officer manages the title search, coordinates payoffs and funding, and records the deed. Closing typically takes 30–45 days from accepted offer. You'll wire your down payment and closing costs to escrow 24–48 hours before signing; confirm wire instructions directly with your escrow officer by phone to avoid wire fraud schemes, which target real estate transactions specifically.
How Much Home Can You Afford in Longview
The table below gives a plain-language budget snapshot across realistic Longview entry points. Closing costs are estimated at 2–3% of the purchase price (lender fees, escrow, title, prepaid insurance and taxes); your actual figures will vary by lender and loan type. These are estimates for planning purposes only — the mortgage calculator below this section will generate payment scenarios specific to your inputs.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — entry-level fixer | $300,000 | $10,500 (3.5%) | $7,500–$9,000 | ~$18,000–$19,500 |
| Conventional (3%) — entry-level move-in ready | $320,000 | $9,600 (3%) | $8,000–$9,600 | ~$17,600–$19,200 |
| FHA (3.5%) — near city median | $374,000 | $13,090 (3.5%) | $9,350–$11,220 | ~$22,440–$24,310 |
| Conventional (5%) — mid-range updated home | $374,000 | $18,700 (5%) | $9,350–$11,220 | ~$28,050–$29,920 |
| Conventional (10%) — Highlands / Beacon Hill range | $420,000 | $42,000 (10%) | $10,500–$12,600 | ~$52,500–$54,600 |
| Conventional (20%) — avoid PMI, city median | $374,000 | $74,800 (20%) | $9,350–$11,220 | ~$84,150–$86,020 |
Private mortgage insurance (PMI) applies to conventional loans below 20% down, and FHA loans carry mortgage insurance premiums for the life of the loan (or until refinanced) — both add to your monthly payment, which the calculator handles.
One often-overlooked budget line: cash reserves. Many lenders want to see 2–3 months of housing payments in savings after your down payment and closing costs clear. First-timers who drain every dollar to get to the table sometimes get a last-minute underwriting condition they can't satisfy. Build that buffer into your savings target from the start.
Looking to buy in Longview? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Longview quote.
Common First-Time Buyer Mistakes in Longview
Mistake 1: Shopping Before Pre-Approval
This is the single most common first-timer error in Longview, and it's painful in a market where homes go to pending in about 8 days. Falling in love with a home on a Friday and then spending the weekend finding a lender means you're writing your pre-approval request while the sellers are already reviewing competing offers. Get the letter first, then start touring.
Mistake 2: Waiving Inspection to Win an Offer
In a competitive multiple-offer situation, some first-timers waive the inspection contingency entirely to make their offer look cleaner. In Longview, where a meaningful portion of the housing stock predates 1980, this is a significant gamble. Electrical panels, cast-iron drain lines, and older roofing are frequent findings on homes in Columbia Valley Gardens and parts of West Longview. A short inspection period (7–10 days rather than the standard 14) is a reasonable competitive concession; eliminating it outright on a 1960s bungalow is not. The inspection is the one moment you have full information before you're legally committed.
Mistake 3: Underbudgeting the Cash Needed to Close
Most first-timers fixate on the down payment and forget that closing costs add another 2–3% of the purchase price on top of it. On a $374,000 home, that's roughly $7,500–$11,000 in lender fees, escrow charges, title insurance, and prepaid taxes and insurance — before the down payment. Then add the lender's reserve requirement. Buyers who don't model this early often find themselves at the finish line short on cash, scrambling to negotiate seller-paid closing cost credits that aren't always available in a competitive offer situation.
Mistake 4: Skipping Location Due Diligence Before Making an Offer
Longview's residential grid can be deceptive — streets that look similar on a map can differ significantly in character depending on proximity to the industrial corridor along the Columbia River waterfront. Buyers who commute to Portland on I-5 frequently underestimate what that drive feels like in January rain or during a Friday afternoon freight delay near Kalama. Driving the route during actual commute hours before you commit to a neighborhood is the kind of due diligence no one does and nearly everyone wishes they had.
What Surprises People After Six Months
First-timers who close in Longview and then discover they're actually spending evenings in Kelso for errands — because Ocean Beach Highway and the 3rd Avenue corridor are where most daily retail is clustered — sometimes feel like the map didn't match their expectations. The city's grid is logical but spread out; proximity to Lake Sacajawea Park doesn't automatically mean walkable access to grocery stores or coffee. Grabbing a morning drink at Bulls & Brews Espresso on Ocean Beach Hwy or an evening out at Ashtown Brewing Co. on 11th Ave is easy enough — but plan for car dependency in day-to-day life, and factor that into which neighborhood actually fits your routine.
Local Expert Takeaway: Longview's entry-level price point is real, but the market moves fast enough that first-timers who aren't pre-approved and working with a local agent frequently lose homes before they even make an offer. The sweet spot for most first-time buyers here is in the low-to-mid $300,000s — older stock in West Longview or Columbia Valley Gardens that needs some updating but gives you a foothold. Budget honestly for closing costs on top of your down payment, don't waive inspection on pre-1980 homes, and verify your I-5 commute in real conditions before signing anything. Washington's no-income-tax advantage is genuine and meaningfully improves your monthly budget — just make sure you're modeling the full cash-to-close figure before you fall for a listing.
Quick Takeaways & FAQs
✅ Longview's Zillow Home Value Index of $374,268 (2026) sits noticeably below Portland-area prices, making it one of the more accessible entry points in Southwest Washington for first-time buyers.
⚠️ Homes in Longview average around 8 days to pending — first-timers who aren't pre-approved before they start touring routinely lose their top picks before the weekend is over.
📍 Washington state has no personal income tax, which improves real take-home pay for buyers relocating from Oregon or California — a meaningful boost to your actual mortgage affordability.
What credit score do I need to buy a home in Longview, WA?
How long does it take to buy a home in Longview from offer to closing?
How much cash do I actually need to buy a $374,000 home in Longview?
Is Longview, WA a buyer's or seller's market right now?
Do I need a home inspection in Washington state, and is it worth it in a competitive market?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
