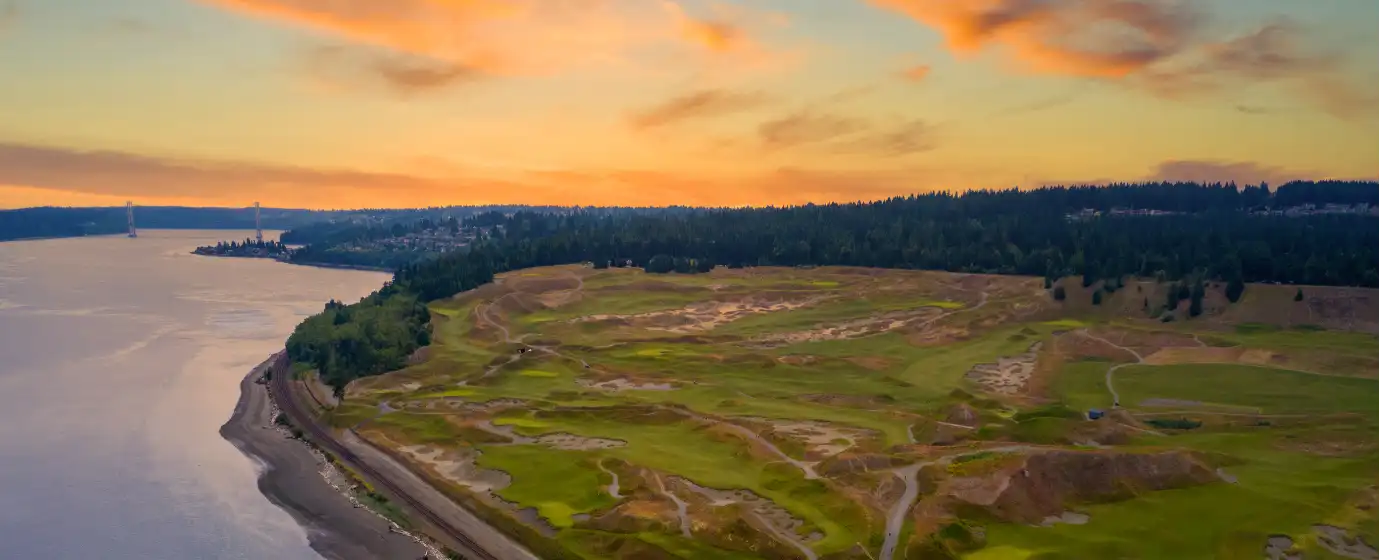
Maybe your company is relocating you near Joint Base Lewis-McChord, or you've been watching Tacoma prices climb and someone mentioned Lakewood as the more affordable alternative just to the southwest. Either way, you've landed in a market with a split personality: prices that still feel reachable compared to most of western Washington, combined with a pace of sale — homes going to pending in roughly 10 days as of June 2026 — that catches first-timers off guard every single time. The city of 62,937 sits just off I-5 in Pierce County, with American Lake to the west and Tacoma about 15 minutes up the road, and its entry-level inventory moves fast enough that preparation isn't optional.
Lakewood's buyer pool is unlike almost any other South Puget Sound city. Because Joint Base Lewis-McChord anchors the local economy, a significant share of buyers here are active-duty military, veterans, or civilian defense workers — many of them financing with VA loans. That matters to you as a first-timer, because it shapes the competition. VA buyers can often move quickly and with strong offers. The owner-occupancy rate sits at approximately 44.8%, well below the national average, which means a large share of the housing stock has historically been rental — and that translates to genuine opportunity for buyers ready to act decisively. The full community profile covers the city's character in more depth.
The Zillow Home Value Index (ZHVI) for Lakewood was $526,659 as of June 2026, essentially flat year-over-year — a relative stability that's increasingly rare in western Washington. For a detailed breakdown of how that stacks up against the broader cost of living here, see the cost-of-living page. Condos and townhomes open the market at roughly $318,000 on the low end, while single-family homes in the city average closer to $514,500 — giving first-timers real options at different price points if they know where to look and arrive financially ready.
This guide walks you through what your budget actually buys in Lakewood right now, the step-by-step buying process with the local wrinkles that trip up first-timers, a concrete budget table to stress-test your numbers, and the most common — and costly — mistakes buyers make in this specific market.
The Lakewood First-Time Buyer Reality
The headline number is $526,659 — the Zillow Home Value Index for Lakewood as of June 2026. That figure masks a meaningful spread. Condos and smaller townhomes start around $318,000, which is genuinely accessible for buyers with solid credit and a modest down payment. Single-family homes cluster closer to the mid-$500s, and anything turnkey in established neighborhoods tends to generate multiple offers within the first weekend.
What first-timers often don't realize: Lakewood's affordability relative to Tacoma attracts buyers from across Pierce County and beyond, compressing the time you have to decide. Homes that need updating — older ranches and split-levels throughout the city — linger a little longer and represent the clearest entry point for buyers willing to do some work. Waiting for a perfect move-in-ready home in this price range, without a pre-approval letter already in hand, is the single fastest way to lose a deal here.
The military connection shapes the market in a concrete way. VA loans — available to eligible active-duty service members, veterans, and surviving spouses at 0% down — are widely used in Lakewood, and local lenders and listing agents understand them. If you qualify for a VA loan, that's not a footnote; it's a genuine competitive and financial advantage in this city specifically. For buyers who don't, FHA (3.5% down) and conventional programs at 3% down are the realistic entry paths at current price points.
The Homebuying Process in Lakewood, Step by Step
Step 1 — Get Pre-Approved Before You Tour Anything
This isn't boilerplate advice in Lakewood — it's a hard market requirement. With homes going to pending in roughly 10 days, you will not have time to start the pre-approval process after you find a home you like. Get the full pre-approval letter (not a pre-qualification estimate) from a lender before your first showing. Sellers and agents in this market treat an offer without one as non-serious.
Your debt-to-income ratio (DTI) is the number lenders focus on most. As a general guideline, your total monthly debt obligations — including the new mortgage payment — should stay at or below 50% of your gross monthly income. Running this math yourself before you apply prevents surprises during underwriting.
Step 2 — Shop With a Realistic Price Ceiling, Not a Hope Number
Know your actual approved amount and then shop 5–10% below it. That buffer gives you room to compete with an offer slightly over asking without blowing your budget — a tactic that matters in Lakewood's faster-moving pockets. Work with an agent who knows the difference between investor-heavy inventory in some parts of the city and the more owner-occupant-friendly streets in others.
Step 3 — Make a Clean, Prepared Offer
In a market where multiple offers are common on weekend-listed properties, your offer needs to be complete on day one: pre-approval letter, earnest money ready to wire, and terms that don't introduce unnecessary friction. Washington is an attorney-optional closing state — your real estate agent and escrow officer handle the bulk of the transaction — but understanding the standard residential purchase agreement terms before you're in a multiple-offer situation prevents panic decisions.
Step 4 — Inspection and Appraisal — Don't Skip Either
The inspection is where first-timers most commonly make a costly error in competitive markets: waiving it entirely to "win" the offer. In Lakewood's older housing stock — plenty of mid-century construction, some with deferred maintenance — an uninspected home can carry $15,000–$40,000 in undisclosed issues. A better approach is an inspection contingency with a tight turnaround (5–7 days), not a waived one.
The appraisal is lender-ordered and non-negotiable if you're financing. If the home appraises below your offer price, you'll need to cover the gap in cash, renegotiate, or walk away. Build this scenario into your planning before you offer, not after.
Step 5 — Closing
Washington closings typically take 30–45 days from accepted offer to keys in hand. Budget your closing costs separately from your down payment — plan on roughly 2%–5% of the purchase price in lender fees, title, escrow, and prepaid items. On a $500,000 purchase, that's $10,000–$25,000 in addition to your down payment, arriving at the table by wire transfer. First-timers who miscalculate this are the ones calling family for a last-minute loan the week before closing.
How Much Home Can You Afford in Lakewood
The table below stress-tests a range of price points against common loan types and estimated cash requirements. All figures are approximate estimates — actual closing costs vary by lender, loan type, and transaction specifics. Use this as a planning starting point, then run your real numbers with a lender.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2%–5%) | Est. Total Cash Needed |
|---|---|---|---|---|
| Condo / entry-level (Conventional 3%) | $320,000 | $9,600 (3%) | $6,400–$16,000 | ~$16,000–$25,600 |
| Condo / entry-level (FHA 3.5%) | $320,000 | $11,200 (3.5%) | $6,400–$16,000 | ~$17,600–$27,200 |
| Fixer single-family (Conventional 3%) | $430,000 | $12,900 (3%) | $8,600–$21,500 | ~$21,500–$34,400 |
| Near-median single-family (Conventional 3%) | $526,659 | $15,800 (3%) | $10,533–$26,333 | ~$26,333–$42,133 |
| Near-median single-family (FHA 3.5%) | $526,659 | $18,433 (3.5%) | $10,533–$26,333 | ~$28,966–$44,766 |
| VA loan — eligible buyers (0% down) | $526,659 | $0 | $10,533–$26,333 (VA limits some fees) | ~$10,533–$26,333 |
* Down payment percentages shown are the minimum for each loan type. Closing cost estimates use the 2%–5% range; VA loans cap or eliminate certain lender fees, so costs toward the lower end of that range are more typical for VA borrowers. The interactive mortgage calculator below estimates monthly payments based on your inputs.
One local reality worth building into your plan: Lakewood's effective property tax rate is approximately 0.94%, which the calculator factors into your payment estimate. On a mid-$500s purchase, that's a meaningful line item in your monthly budget — make sure your lender's pre-approval reflects it.
Looking to buy in Lakewood? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Lakewood quote.
Common First-Time Buyer Mistakes in Lakewood
Touring Before You Have a Pre-Approval Letter
It feels harmless to "just look" before you're fully approved. In Lakewood, it's a trap. A home you fall in love with on a Saturday afternoon can be under contract by Monday morning. Agents in this market are reluctant to show serious inventory to buyers who can't back an offer immediately, and sellers won't wait for you to start your paperwork. Get the letter first — always.
Waiving the Inspection to Win a Bidding War
The pressure to waive contingencies is real in competitive offers, but Lakewood's housing stock makes this riskier than average. The city has substantial mid-century construction — 1950s and 1960s ranches and split-levels that may carry aging electrical panels, original plumbing, or moisture issues common in western Washington's wet climate. A tight inspection window protects you; eliminating it entirely puts you one sewer scope away from a five-figure surprise after closing.
Underestimating How Much Cash You Need at the Table
First-timers routinely focus on the down payment and mentally set aside the closing costs for later. On a $500,000 purchase with a 3% down payment, you've saved $15,000 — and then the closing disclosure arrives showing another $12,000–$22,000 in escrow fees, lender charges, title insurance, and prepaid homeowner's insurance and property taxes. That total cash requirement catches people off guard every cycle. Budget for both from day one, not two weeks before closing.
Skipping Address-Level Research Before Making an Offer
Buyers with children need to verify the specific school assignment for any address before making an offer — boundaries within the local district vary meaningfully by street, and assumptions based on a neighborhood's general reputation can be wrong. Similarly, buyers targeting certain pockets near I-5 interchanges discover the noise and traffic volume is part of the daily experience. Drive the route at rush hour and stand in the backyard before you decide.
Local Expert Takeaway: Lakewood rewards first-time buyers who arrive prepared and penalizes those who don't. With homes going to pending in about 10 days and a buyer pool that includes experienced VA borrowers near Joint Base Lewis-McChord, showing up without a pre-approval letter is the single costliest mistake you can make here. The entry-level opportunity is real — condos around $318,000 and fixer single-families in the low-$400s exist — but they don't wait. Get your financing locked, build your full cash stack (down payment plus closing costs), and know which neighborhoods fit your lifestyle before you start touring. The buyers who move deliberately and quickly are the ones who close.
Quick Takeaways & FAQs
✅ Lakewood's $526,659 median home price (Zillow ZHVI, June 2026) sits noticeably below comparable South Puget Sound cities, giving first-timers a genuine shot at entry-level ownership without stretching to their absolute ceiling.
⚠️ Homes go to pending in roughly 10 days, meaning a pre-approval letter isn't a suggestion — it's a prerequisite before your first showing.
📍 VA loans are unusually common in Lakewood because of the city's proximity to Joint Base Lewis-McChord; if you or your spouse qualify, local lenders and listing agents know how to move VA offers quickly, which is a real competitive edge in this market.
What credit score do I need to buy a home in Lakewood, WA?
How long does it take to close on a home in Lakewood?
Is it better to buy a condo or a single-family home in Lakewood as a first-time buyer?
Do I need a real estate agent to buy a home in Lakewood?
Are VA loans common in Lakewood, and do sellers accept them?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
