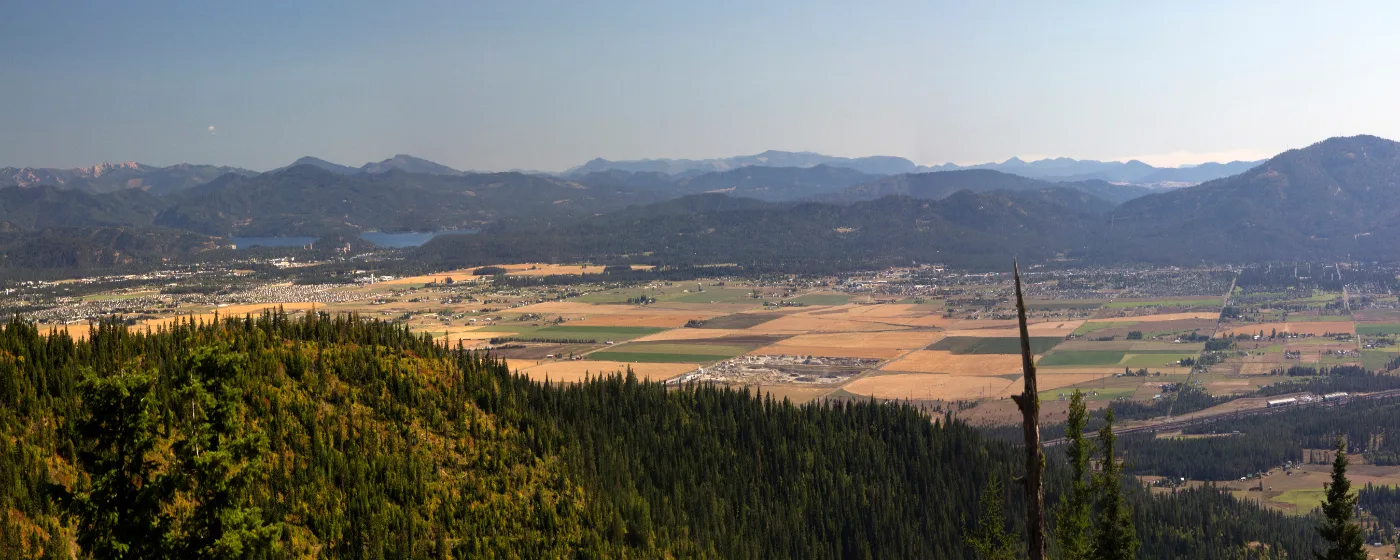
Maybe you've been priced out of Coeur d'Alene and someone pointed you fifteen minutes west on Highway 53. Maybe you drove through Rathdrum's downtown on Main Street and noticed the lots are bigger, the pace is slower, and the price tags looked different. They are different — but not as different as newcomers hope. The Zillow Home Value Index put Rathdrum at $544,024 in April 2026, a figure that climbed 2.5% in the preceding year and shows no sign of retreating. This is a working-class North Idaho town that has absorbed a significant amount of migration pressure from its pricier neighbors, and that pressure has lifted the floor on what a first-time buyer needs to bring to the table.
Rathdrum sits in Kootenai County along the Rathdrum Prairie, a broad flat corridor that stretches between the mountains to the north and the Spokane River drainage to the south. The town's employment base — Heritage Health in healthcare, Dyno Nobel in engineering, and retail anchors like Super 1 Foods — keeps household income grounded around $86,563. Many buyers here commute into Coeur d'Alene, Post Falls, or even Spokane, treating Rathdrum as the affordable landing pad in a corridor where every mile west costs a bit less. Roughly 77% of occupied housing units are owner-occupied, which means inventory turns over slowly and competition, when it arrives, arrives fast.
For a first-time buyer, the practical math is this: you are not walking into a discount market, but you are walking into one that is meaningfully more accessible than Coeur d'Alene to the east — see the full cost-of-living breakdown for how that shakes out across taxes, utilities, and day-to-day expenses. The effective property tax rate in Kootenai County runs approximately 0.60% of assessed value, one of the lowest in the West, which softens the monthly carrying cost once you're in. New construction accounts for a substantial slice of available inventory — nearly a third of May 2025 sales were new builds — so your options aren't limited to older resale stock, though new construction comes with its own pricing and timeline dynamics.
Whether you're comparing Rathdrum to Post Falls, weighing a condo in Hayden against a lot in the Rathdrum Prairie, or simply trying to figure out whether your pre-approval gets you anything real here, the sections below walk through exactly what a first-time buyer needs to know: what your budget actually buys, how the purchase process works in this specific market, how to build a realistic cash budget, and the mistakes that cost first-timers the most.
The Rathdrum First-Time Buyer Reality
The Zillow Home Value Index for Rathdrum stood at $544,024 in April 2026 — and that figure is the starting point for every honest first-time buyer conversation here, not an aspirational ceiling. Redfin's April 2026 median sale price came in at $519,732 with homes sitting roughly 34 days before going under contract, which gives buyers a bit more breathing room than the frantic pace of 2021–2022. Still, Zillow's market data shows homes going to pending in around 15 days, and sellers in May 2025 were accepting an average of 99% of list price. Practically speaking, list price is close to the floor, not the opening bid.
Resale inventory spans a wide range of eras and conditions — from older downtown stock that can offer lower entry points to newer construction on the Prairie that commands a premium. The gap between the most accessible resale homes and the city median is meaningful, but it's a gap you'll explore with your agent neighborhood by neighborhood rather than something that can be summarized cleanly from the outside. What the numbers confirm: this is a mid-priced North Idaho market, not an entry-level one.
New construction is not a workaround for price — builders in May 2025 averaged $303 per square foot, compared to $315 per square foot for existing city-lot resales. The gap is real but narrow, and new builds typically require you to wait months for completion and to navigate builder contracts without the same inspection flexibility you'd have on resale. First-time buyers who assume new construction means cheaper are regularly surprised at the final contract number. Understanding that early saves a lot of wasted tours.
The Homebuying Process in Rathdrum, Step by Step
Step 1: Get Pre-Approved Before You Look at a Single Listing
In a market where homes routinely accept 99% of list price and can go pending in two weeks, showing up without a lender letter is a liability. Sellers and listing agents in Rathdrum take pre-approval seriously — a pre-qualification letter (the softer, less verified version) won't carry the same weight. Work with a lender who can issue a fully underwritten pre-approval, ideally one familiar with Kootenai County properties, before you set foot in an open house.
Step 2: Define Your Loan Type Early
FHA loans — which require as little as 3.5% down with a 580 credit score — are common among first-time buyers in Rathdrum, but they come with mortgage insurance premiums and appraisal requirements that some sellers factor into their decision when reviewing competing offers. Conventional loans at 3% down require a stronger credit profile but carry no upfront mortgage insurance premium and can look cleaner to a seller in a multi-offer situation. VA loans (zero down for qualifying veterans and active-duty service members) and USDA Rural Development loans (zero down for eligible rural properties) are worth investigating with your lender if you qualify — both can be highly competitive loan products. Know your loan type before you start shopping so your agent can position your offer appropriately.
Step 3: Shop With Range Discipline
Set your search ceiling $25,000–$30,000 below your maximum pre-approval, not at it. In Rathdrum, list prices and sale prices are close together, which means you'll have limited room to negotiate down but real risk of losing a home you love if you've pre-approved yourself to the absolute edge. Your agent should be pulling active listings across multiple areas simultaneously so you can compare apples to apples before you fall in love with a specific address.
Step 4: Make a Clean Offer — Then Inspect Thoroughly
The most common mistake first-time buyers make in this market is conflating "don't waive contingencies" with "add contingencies loosely." Your inspection contingency is non-negotiable — keep it. Your appraisal contingency protects you if the home values below your offer price — keep it. What you can do to strengthen an offer without waiving protection is tighten your timelines: a 7-day inspection period and a 30-day close are competitive without leaving you exposed. Idaho is an escrow-closing state, meaning a title and escrow company (not an attorney) handles the closing process, and closings in Kootenai County typically run 30–45 days from accepted offer to keys.
Step 5: Budget for What Happens Between Offer and Close
The inspection itself costs $350–$550 for a standard single-family home in the Rathdrum area, paid out of pocket before closing — not rolled into the loan. If the inspector flags the roof, the HVAC, or the electrical panel, you'll want cash available to either renegotiate or walk. First-timers who spend every dollar on the down payment often find themselves unable to respond to inspection findings. Plan for the inspection, the appraisal fee (typically $500–$700), and a cushion for repair negotiation before you write the offer.
How Much Home Can You Afford in Rathdrum
The table below shows approximate cash requirements at several realistic Rathdrum price points. Closing costs are estimated at 2–3% of the purchase price, which is typical for Kootenai County buyers using conventional or FHA financing — your lender's Loan Estimate will show the exact figure for your transaction. These are estimates only; actual figures vary by lender, loan type, and negotiated seller concessions.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5% down) — entry resale | $420,000 | ~$14,700 (3.5%) | ~$8,400–$12,600 | ~$23,100–$27,300 |
| Conventional (3% down) — entry resale | $420,000 | ~$12,600 (3%) | ~$8,400–$12,600 | ~$21,000–$25,200 |
| FHA (3.5% down) — city median | $519,000 | ~$18,165 (3.5%) | ~$10,380–$15,570 | ~$28,545–$33,735 |
| Conventional (3% down) — city median | $519,000 | ~$15,570 (3%) | ~$10,380–$15,570 | ~$25,950–$31,140 |
| Conventional (10% down) — mid-range | $544,000 | ~$54,400 (10%) | ~$10,880–$16,320 | ~$65,280–$70,720 |
| Conventional (20% down) — avoid PMI | $544,000 | ~$108,800 (20%) | ~$10,880–$16,320 | ~$119,680–$125,120 |
The 20%-down row isn't aspirational — it's what buyers with strong equity from a prior sale or significant savings bring. For most first-time buyers in Rathdrum, the realistic landing zone is one of the 3–3.5% down scenarios, which means the cash-needed number is in the $21,000–$34,000 range before reserves.
Lenders typically want to see 2–3 months of mortgage payments in reserve after closing — money that stays in your account, not spent on moving costs or furniture. Build that into your savings target well before you start touring homes. Idaho offers a state tax-advantaged First-Time Homebuyer Savings account through participating credit unions, which can help you grow that reserve with a tax benefit on contributions — worth asking your lender or credit union about as a savings tool.
Looking to buy in Rathdrum? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Rathdrum quote.
Common First-Time Buyer Mistakes in Rathdrum
Waiving the Inspection to Win — Then Regretting It
Rathdrum's resale inventory includes homes built in the 1970s and 1980s, particularly near downtown and some older sections of the city. Aging mechanical systems — furnaces past their service life, original electrical panels, crawl space moisture issues from the prairie water table — are real risks that show up in inspections here. Buyers who waive the inspection to compete have ended up absorbing $15,000–$40,000 in deferred maintenance they didn't price into their offer. The inspection contingency exists specifically for markets like this one. Keep it.
Shopping Before Pre-Approval and Losing the Home That Fit
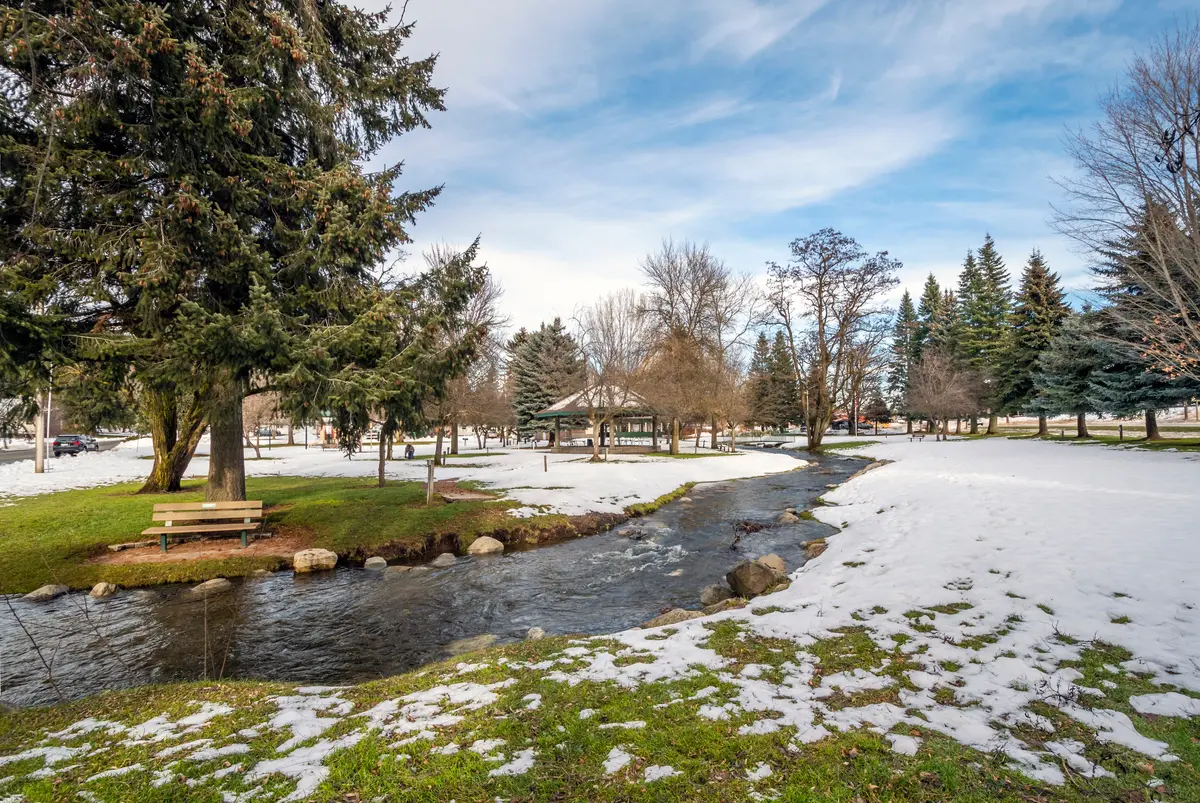
Rathdrum's inventory is thin enough that a well-priced home near Rathdrum City Park or in one of the newer Prairie subdivisions can go pending before the weekend is over. First-time buyers who spend two weeks "just looking" while they gather documents for their lender frequently watch the same homes they toured go under contract before their pre-approval arrives. Start the lender conversation the same week you start your search — not after you've found the house.
Skipping the Address-Level Due Diligence
Details that matter to your household — utility providers, HOA covenants in newer Prairie subdivisions, well versus municipal water — vary by address in ways that aren't obvious from a listing page. If any of these factors are important to your daily life or budget, confirm them directly before you write an offer. It takes one phone call and can save a significant amount of disappointment after closing.
Underestimating the True Cash Requirement
The down payment number is the one buyers focus on, but it's rarely the number that kills a deal — the total cash stack is. Down payment plus closing costs plus inspection fee plus appraisal fee plus moving costs plus post-closing reserves can easily run $10,000–$15,000 higher than a buyer calculated from the down payment alone. One common pattern: a buyer pre-approves at $500,000, scrapes together 3.5% down ($17,500), then discovers they have $3,000 left after closing costs — not enough to satisfy a lender's reserve requirement. Work backward from total cash available, not from down payment percentage, when you set your search price ceiling.
Local Expert Takeaway: Rathdrum rewards buyers who show up prepared, not buyers who show up optimistic. Get fully pre-approved — not just pre-qualified — before you tour a single home on Main Street or out on the Prairie. The cash requirement at a $519,000–$544,000 price point is real: plan for $25,000–$35,000 in total cash at minimum for a low-down-payment scenario, plus reserves your lender will verify. Homes here sell close to list price and can go pending inside two weeks, so losing a home to a more prepared buyer isn't a fluke — it's the pattern. The buyers who land here successfully are the ones who treated the financial homework as step one, not something to figure out after they fell in love with a house.
Quick Takeaways & FAQs
✅ Rathdrum's approximately 0.60% effective property tax rate is among the lowest in the West, meaningfully reducing monthly carrying costs compared to many out-of-state markets first-time buyers are moving from.
⚠️ With a Zillow Home Value Index of $544,024 (April 2026) and homes selling at roughly 99% of list price, Rathdrum is a mid-priced North Idaho market — not a discount one — and buyers who arrive expecting room to negotiate below list are regularly surprised.
📍 Nearly a third of Rathdrum's May 2025 sales were new construction, so first-time buyers have builder inventory as a real option — but new builds average $303/sq ft and come with their own contract terms, timelines, and limited inspection flexibility that differ significantly from resale purchases.
What credit score do I need to buy a home in Rathdrum, Idaho?
How long does it take to close on a home in Rathdrum?
Is Rathdrum a buyer's market or a seller's market right now?
Can I use a USDA loan to buy in Rathdrum?
What are closing costs typically in Kootenai County?
Moving to Idaho?
Tell us what you need help with and we'll connect you with local resources.
