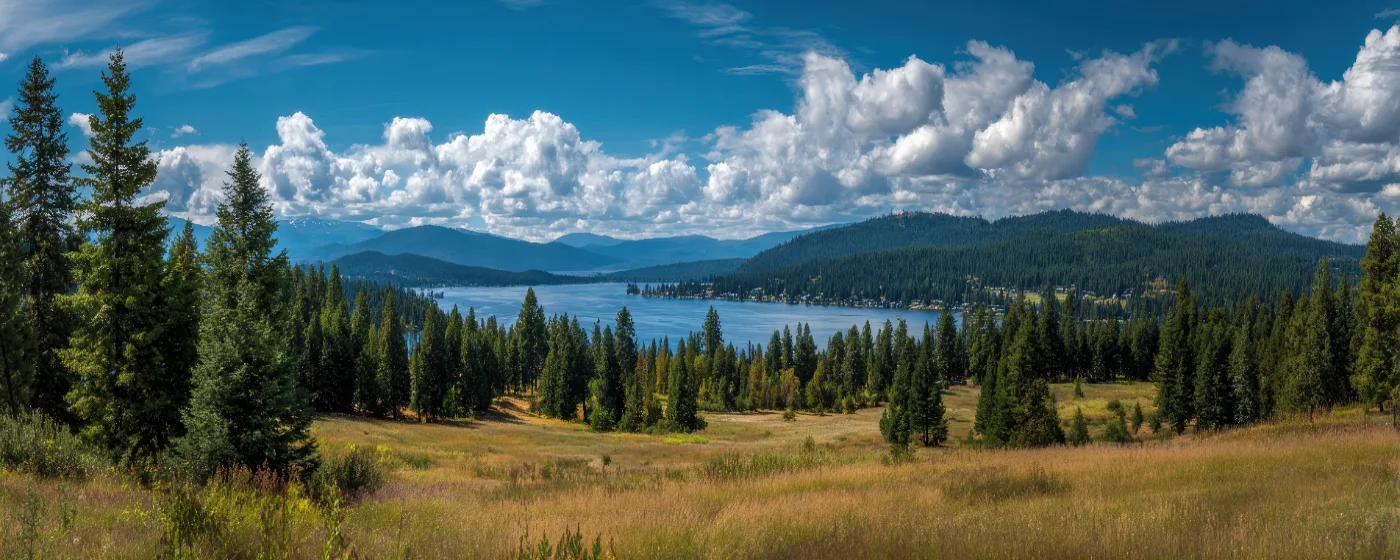
Maybe you've been watching McCall from a distance — weekends at Payette Lake, a ski run at Brundage Mountain — and decided you want to stop renting and start owning here. The surprise waiting for most first-timers is how far this market sits from a typical Idaho entry-level purchase. McCall is a resort town of roughly 4,300 permanent residents, and its pricing reflects the second-home and vacation-rental demand that competes with every primary-residence buyer who walks through the door. Highway 55 is your only route in from Boise, and that two-hour drive north from the valley shapes everything — who buys here, what they pay, and how quickly they need to move when the right property surfaces.
The economic backbone of McCall is built around Brundage Mountain Resort, Shore Lodge, and the City of McCall itself. These employers anchor a year-round residential population that coexists with a significant part-time ownership class. That dynamic keeps prices elevated even in slower seasons and means the competition for genuinely affordable entry-level homes is real and consistent. The cost of living page covers the full income and tax picture, but the short version is that the median household income here sits well below what most lenders would want to see for a purchase at current market prices — meaning many first-time buyers are coming in with outside income, remote work earnings, or family support.
Inventory has grown from the pandemic-era lows — Valley County listings were up roughly 30% year-over-year as of early 2026 — which gives buyers more to look at than they had a few years ago. But more inventory has not translated into drastically lower prices. The Zillow Home Value Index for McCall stood at $732,201 in 2026, and median list prices in the market have been running considerably higher than that benchmark, in the $825,000–$950,000 range. For a first-time buyer, those numbers require honest budgeting before you fall in love with a lake-view listing you cannot yet reach.
Whether you're a remote worker drawn by the mountain lifestyle or a local employee ready to stop renting, the sections below walk through what your budget actually buys in McCall, how the buying process works here step by step, a plain-language budget table, and the specific mistakes that cost first-timers the most in this market.
The McCall First-Time Buyer Reality
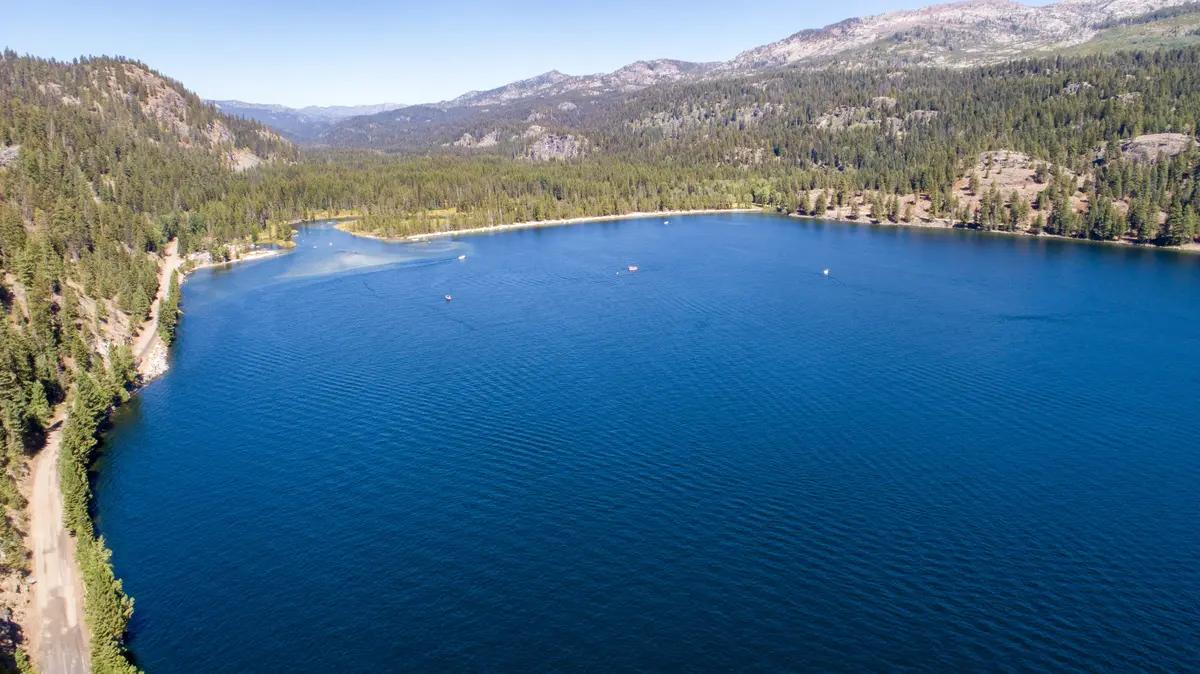
The Zillow Home Value Index for McCall came in at $732,201 in 2026 — and that figure is itself a blended average that includes condos, older cabins, and smaller lots on the fringes of town. The median list price on active inventory has been running noticeably higher, in the $825,000–$950,000 range, which is where you'll spend most of your browsing time on Zillow or Redfin. For a first-time buyer, that spread matters: the homes nearest your budget tend to need work, sit farther from the lake, or come with trade-offs that a second-home buyer shrugs off and a primary-residence buyer feels every day.
Properties at the lower end of the McCall market — older manufactured homes, smaller cabins on the outskirts of town, or dated condos — do surface occasionally, but they move fast. Average homes in this market go pending in roughly 63 days, but the well-priced ones in accessible price ranges can go pending in as few as 8 days. If your budget sits below $600,000, you need to be pre-approved, decisive, and realistic about condition before you start touring.
The seasonal rhythm of the market adds another layer of complexity. Inventory surges in late spring and summer — McCall saw a 42% jump in active listings from May to June 2025 alone — which is when most first-timers start shopping. The catch is that everyone else is shopping then too, including cash-heavy second-home buyers who do not need financing contingencies. Winter shopping, while colder and slower, sometimes surfaces motivated sellers and less competition. The market's resort character doesn't disappear in January, but the urgency does ease.
The Homebuying Process in McCall, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
In most Idaho markets, showing up to a few open houses before getting pre-approved is mildly inefficient. In McCall, it's a real liability. Sellers here — many of whom have owned vacation property and understand what a serious buyer looks like — will not entertain an offer that isn't backed by a lender's pre-approval letter. Pre-approval is a conditional commitment based on verified income, assets, credit, and debts. It is meaningfully stronger than a pre-qualification, and local listing agents will ask for it the moment you express interest.
Step 2: Find a Local Buyer's Agent
McCall's market is small enough that agent relationships and local knowledge carry real weight. An agent who knows which streets in Ponderosa Heights flood in spring, which East Shore lots have easement complications, or which Aspen Village units have HOA battles in progress can save you from an expensive surprise. Interview two or three agents before committing, and ask specifically about their experience with primary-residence buyers — not just second-home or investment transactions.
Step 3: Shop With Your Pre-Approval Range, Not Above It
It's easy to drift upward when browsing. A lake-view property in Spring Mountain Ranch or a newer build near Legacy Park will tempt you past your ceiling. Shop a buffer below your maximum so you have room to negotiate, cover closing costs, and handle the inevitable deferred maintenance that older McCall homes carry.
Step 4: Make an Offer — and Understand the Contingencies
Average homes sell for about 1% below list price, which means aggressive lowballing rarely works and can cost you goodwill with the seller. Your offer should include an inspection contingency (non-negotiable for a first-timer — more on this below) and a financing contingency. In a slower market moment, sellers are more willing to accept these. In a hot window, you may face pressure to shorten timelines. Do not waive your financing contingency to compete unless your lender has fully underwritten the file and you understand the exact risk.
Step 5: Inspection, Appraisal, and Closing
Idaho does not have a state real estate transfer tax, which is a genuine saving compared to many states. Your closing costs will still run approximately 2%–5% of the purchase price, covering lender origination fees, a home appraisal (typically $700–$800 for a standard single-family home in this area), a home inspection ($230–$550), title insurance, and prepaid property taxes and insurance. Budget toward the higher end of that range for a first purchase, since lender fees and title costs on a resort-market transaction can climb. Closing in Idaho typically takes 30–45 days from accepted offer.
How Much Home Can You Afford in McCall
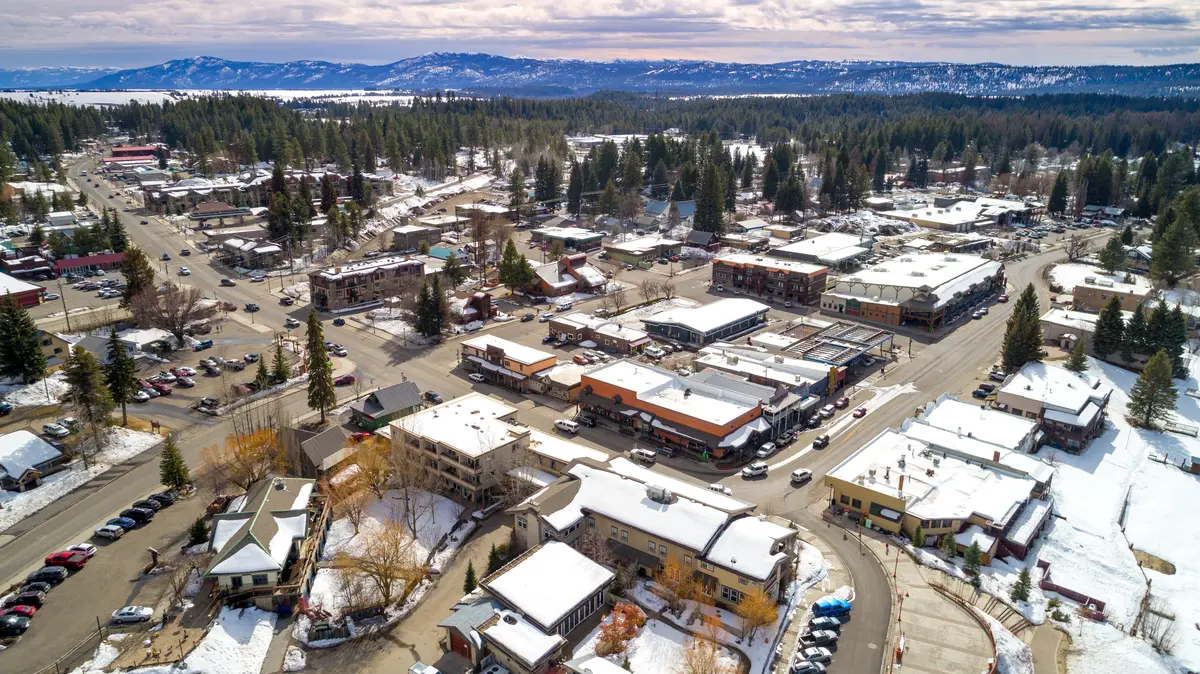
The table below shows estimated cash needed at closing for several realistic McCall purchase scenarios. Closing costs are estimated at 2%–3% of the purchase price for illustration — your actual costs will vary based on lender, loan type, and negotiated seller concessions. These are estimates only; the calculator below will give you a payment scenario based on your own inputs.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–3%) | Total Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5% down) — entry cabin / condo | $450,000 | $15,750 (3.5%) | $9,000–$13,500 | ~$24,750–$29,250 |
| Conventional (3% down) — entry cabin / condo | $450,000 | $13,500 (3%) | $9,000–$13,500 | ~$22,500–$27,000 |
| FHA (3.5% down) — mid-range townhome / older SFR | $600,000 | $21,000 (3.5%) | $12,000–$18,000 | ~$33,000–$39,000 |
| Conventional (5% down) — mid-range SFR | $700,000 | $35,000 (5%) | $14,000–$21,000 | ~$49,000–$56,000 |
| Conventional (10% down) — near-median SFR | $750,000 | $75,000 (10%) | $15,000–$22,500 | ~$90,000–$97,500 |
| Conventional (20% down) — above-median / lake-adjacent | $900,000 | $180,000 (20%) | $18,000–$27,000 | ~$198,000–$207,000 |
All figures are estimates for illustration purposes only. Actual closing costs, loan fees, and cash requirements will vary. Idaho's effective property tax rate is approximately 0.39% — among the lowest in the country — which helps keep ongoing ownership costs manageable once you're in.
One structural advantage for first-timers in Idaho: qualifying buyers may be eligible for a Mortgage Credit Certificate (MCC) through the Idaho Housing and Finance Association, which provides a federal income tax credit of up to 35% of annual mortgage interest paid, capped at $2,000 per year for the life of the loan. This doesn't reduce your purchase price or down payment, but it meaningfully lowers your annual tax bill and improves the long-term affordability math. Ask your lender whether you qualify before closing.
Looking to buy in McCall? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a McCall quote.
Common First-Time Buyer Mistakes in McCall
Waiving the Inspection Contingency
McCall's housing stock includes a meaningful number of older cabins, vacation-era construction, and properties that have been rented hard or left vacant through multiple high-snowpack winters. Roof damage, septic issues, and foundation settling are real findings in this market — not hypotheticals. First-timers sometimes feel pressure to waive the inspection contingency to compete, especially in the summer surge. Don't. A $500 inspection that surfaces a $40,000 structural problem is the best money you'll spend in this process. If a seller refuses any inspection contingency on a property this age, that refusal is itself information.
Shopping Before You're Pre-Approved
McCall's inventory moves slower than Boise's on average, but the well-priced properties move fast — sometimes within 8 days of listing. Buyers who fall in love with a home on a Saturday and spend the following week scrambling to get pre-approved consistently lose to the buyer who walked in ready. Pre-approval in Idaho is based on verified documents — W-2s, tax returns, bank statements, pay stubs — not a five-minute online form. Give your lender a week before you seriously start touring, and refresh the letter if it's more than 90 days old.
Underestimating Total Cash at Closing
The down payment gets all the attention, but closing costs in Idaho run 2%–5% of the purchase price and are almost entirely a separate line item. On a $700,000 purchase, that's roughly $14,000–$35,000 on top of your down payment — and first-timers frequently budget only for the down payment number. Factor in the appraisal ($700–$800), home inspection, title insurance, lender origination fees, and prepaid property taxes and insurance. Running short on closing cash at the table is one of the most avoidable reasons deals fall apart.
Ignoring the Boise Commute Reality
Highway 55 between McCall and Boise is two hours on a good day — longer in winter conditions, and occasionally closed due to rockslides or ice near the Cascade stretch. Buyers who plan to commute to the Treasure Valley even two or three days a week often underestimate how that drive compounds over a year. If your job requires regular valley presence, be honest with yourself about whether McCall is a practical primary residence or a dream that makes more sense once you're fully remote. Many buyers who've made that commute regularly for a year end up selling and moving closer to Boise.
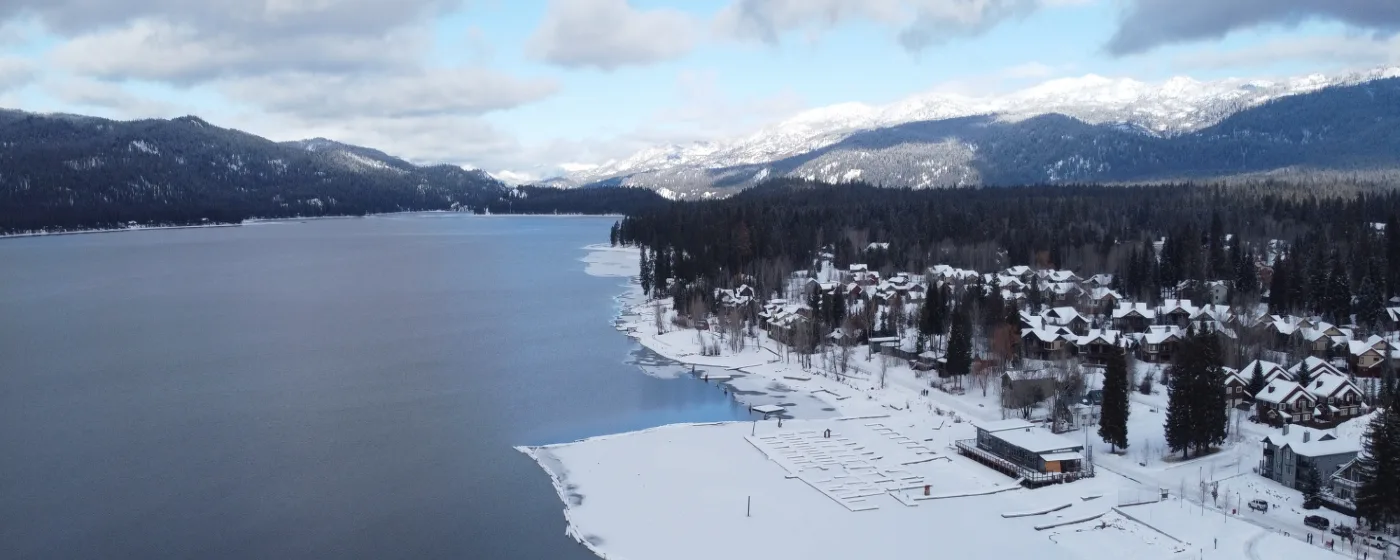
Local Expert Takeaway: McCall rewards first-time buyers who do their homework before they fall in love with a listing. Get your pre-approval letter in hand, know that entry-level inventory surfaces infrequently and moves fast, and budget your total cash at closing at 3%–5% of purchase price on top of your down payment. The seasonal surge from Memorial Day through Labor Day brings more inventory but also more competition — shopping in late fall or early winter, when second-home buyers step back, can give a primary-residence buyer a real edge. Idaho's low property tax rate and the absence of a state transfer tax are genuine structural advantages once you're in; the challenge is simply getting there with enough cash and preparation to compete.
Quick Takeaways & FAQs
✅ Idaho has no state real estate transfer tax, saving McCall buyers thousands of dollars at closing compared to many other states.
⚠️ The Zillow Home Value Index for McCall sits at $732,201 (2026), but active median list prices have been running noticeably higher — first-timers need to budget honestly for the gap between benchmark values and what's actually on the market.
📍 Summer inventory in McCall surges by 40% or more from spring lows, but so does competition from second-home and investment buyers — winter shopping is often overlooked and occasionally more productive for primary-residence buyers.
What is the minimum down payment to buy a home in McCall, Idaho?
How competitive is the McCall real estate market for first-time buyers?
What are typical closing costs when buying a home in McCall?
Is it possible to buy a home in McCall on a modest income?
What time of year is best to buy a home in McCall as a first-timer?
Moving to Idaho?
Tell us what you need help with and we'll connect you with local resources.
