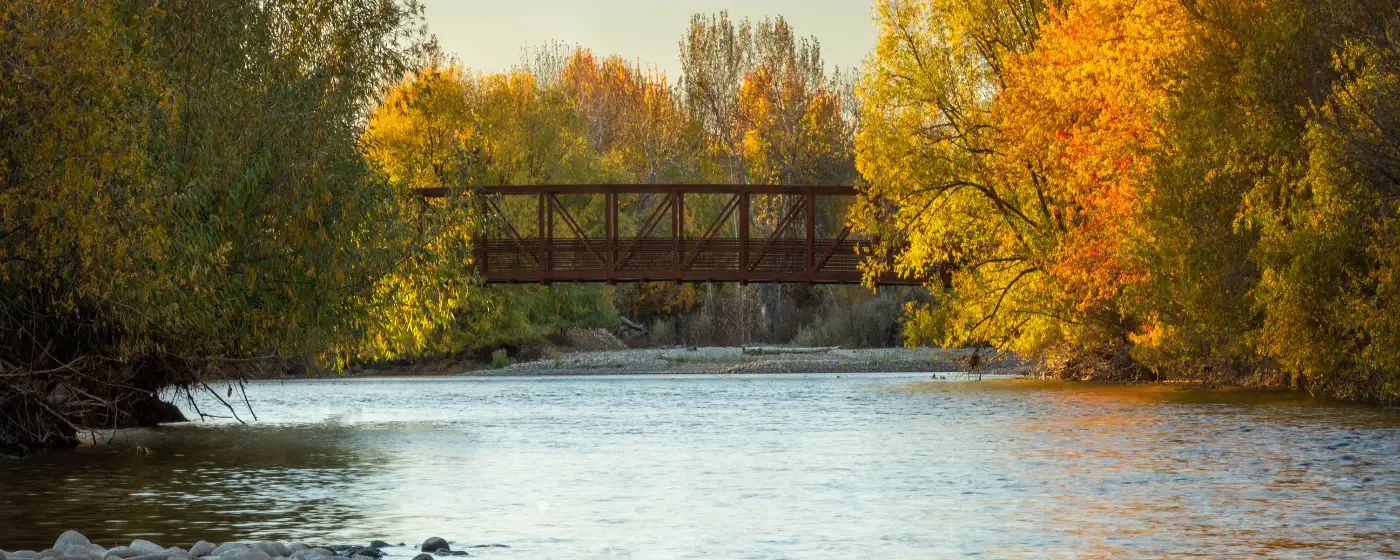
Maybe you've been priced out of Eagle or Meridian and someone mentioned Garden City as the smarter move. Maybe you drove down Chinden Boulevard, spotted the tasting rooms and art studios, and wondered why nobody talks about this place more. Garden City sits in just 4.27 square miles, nearly surrounded by Boise on all sides, yet it operates as its own municipality with its own tax base, its own creative identity, and — critically — its own home prices. Downtown Boise is roughly five minutes away. That proximity is not a rounding error; it shapes everything about what you get here compared to what you'd pay anywhere else in the Treasure Valley.
The city's economic backbone is hospitality, events, and the arts. Expo Idaho anchors the western edge. The Surel Mitchell Live-Work-Create District has pulled working artists and galleries into Garden City since the 2010s. The food-and-beverage scene has grown noticeably in recent years, with Telaya Wine Co. and other anchors drawing residents and visitors alike. That momentum matters to buyers: it signals that the neighborhood is still rising, not plateauing. Families with school-age children benefit from access to a well-regarded public school system serving the area without some of the price premiums attached to surrounding cities.
Garden City's Zillow Home Value Index stood at $474,544 as of April 2026, down slightly year-over-year. For a first-time buyer coming from a major West Coast market, that number looks approachable. Measured against a median household income of $70,124, it still requires careful planning — the math is real, and this guide won't soften it. Idaho's effective property tax rate is low, and Garden City's approximately 0.52% effective rate is one of the genuine financial advantages of buying here versus comparable cities. For a full cost-of-living picture, see the cost of living in Garden City page.
Whether you're seriously ready to make an offer or just mapping out whether Garden City fits your life, the sections below walk through what your budget actually buys here, how the buying process works step by step in this specific market, a budget snapshot table, and the four mistakes that trip up first-timers most often in Garden City.
The Garden City First-Time Buyer Reality
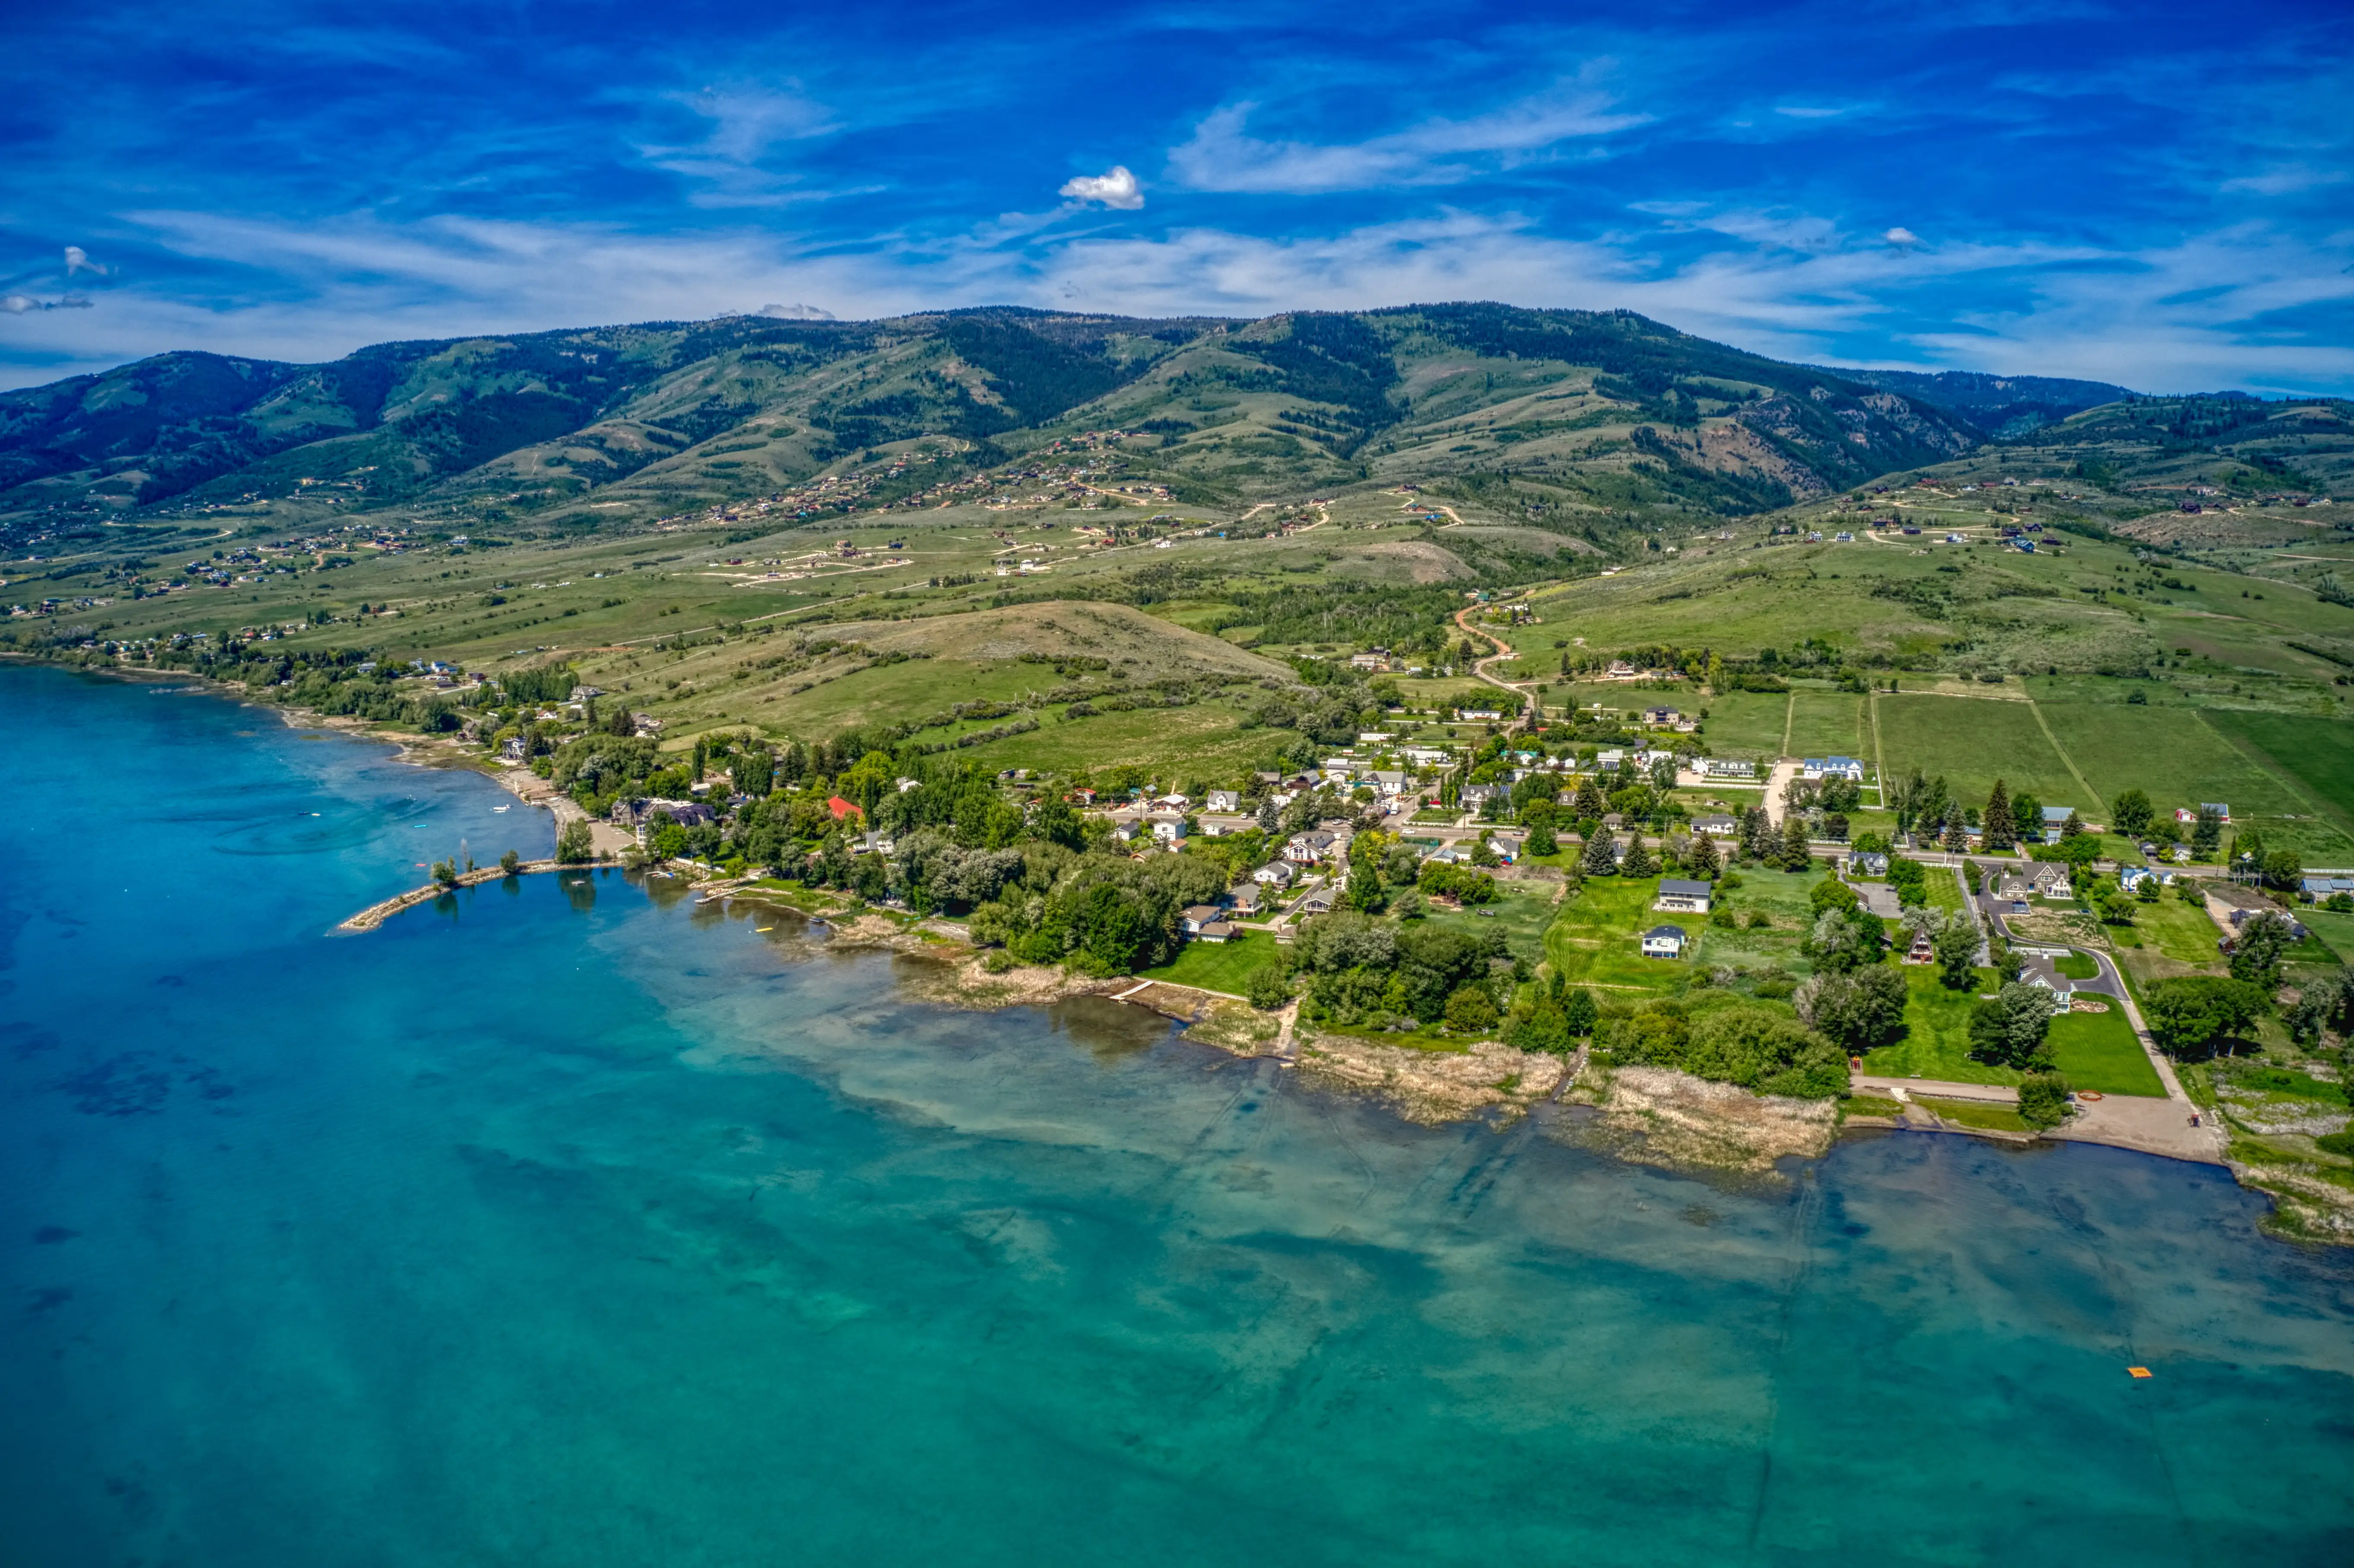
At a Zillow Home Value Index of $474,544 (April 2026), Garden City sits meaningfully below much of the Treasure Valley's more-marketed suburbs. That figure is not a floor — it's the midpoint. Entry-level inventory here tends to be older condos, smaller bungalows near the Garden City Core, and townhomes along the Chinden Corridor, often priced in the low-to-mid $300s when they appear. They move fast and they need work. If your budget tops out around $350,000, be honest with yourself: you're competing for a narrow slice of the market, and condition trade-offs are real.
The market is competitive without being frenzied. Local transaction data shows a sale-to-list ratio near 99% and a median of roughly 38 days on market — sellers are getting close to what they ask, but homes aren't disappearing in 48 hours the way they were at peak. That means a well-prepared buyer with a strong pre-approval letter can still negotiate, but a buyer who shows up without financing in order will lose to someone who did the work.
The honest case for Garden City as a first purchase: you get Boise access, Greenbelt access, a genuinely walkable stretch along the river, and a neighborhood that is still appreciating its identity rather than having already priced it in. The honest caution: inventory is thin, the housing stock skews older and smaller, and the gap between the city's median income and its home prices means you'll need to go into this with your numbers tightly organized.
The Homebuying Process in Garden City, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
Idaho sellers — and Garden City sellers in particular — expect a pre-approval letter attached to any serious offer. Pre-approval requires a lender to verify your credit, income, assets, and existing debts. It is not the same as a pre-qualification estimate, and agents here will tell you which one you have the moment you send it over.
Idaho lenders typically look for a credit score of 620 or higher for conventional loan pre-approval. Pre-approval letters stay active for 60 to 90 days, so time your application so the letter is current when you're actively touring. The most common first-timer mistake in this market: falling in love with a house on a Saturday afternoon and scrambling for financing on Monday. By then, another buyer with a letter already dated has the advantage.
Step 2: Define Your Search Area Within Garden City
Garden City is small — 4.27 square miles — but the character shifts noticeably between the river-adjacent River District, the artist-heavy Surel Mitchell area, the busier Chinden Corridor, and the quieter Garden City Core. Knowing which pocket matches your lifestyle before you start scheduling showings saves weeks of confusion.
Step 3: Make an Offer That Reflects the Market
With a sale-to-list ratio near 99%, coming in well below asking is rarely a winning strategy on a well-priced home. Your agent will pull recent comparable sales — ask specifically for Garden City sales data rather than broader Boise metro figures, because the submarkets don't always move together. Your offer will include earnest money (typically 1% of the purchase price in this market), the loan type, and your contingencies.
Step 4: Inspection and Appraisal
Never waive the inspection contingency on an older Garden City home. Much of the housing stock near the Core and the River District dates to the mid-twentieth century. Plumbing, electrical, and foundation surprises are real. The inspection contingency gives you the right to negotiate repairs or walk away — protecting it is non-negotiable for a first-time buyer who hasn't budgeted for a major surprise.
The appraisal is ordered by your lender and confirms the home's value supports the loan amount. If the home appraises below purchase price, you'll need to renegotiate, cover the gap in cash, or exit under the appraisal contingency. Protect that contingency too.
Step 5: Closing
Idaho closings typically take 30 to 45 days from accepted offer to funded transaction. You'll sign a stack of documents, wire your closing costs and down payment, and receive keys. Bring a cashier's check or arrange a wire transfer — personal checks are not accepted at closing. Budget your closing cash carefully before you ever make an offer; the section below breaks down what that number looks like at several realistic price points.
How Much Home Can You Afford in Garden City
The table below shows approximate cash needed at closing across several realistic Garden City price points and two common loan structures. Closing costs are estimated at 2–3% of the purchase price, which is a standard Idaho range covering lender fees, title insurance, escrow, and prepaid items. These are estimates — your lender will provide a Loan Estimate within three business days of application that shows your actual figures.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–3%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — entry condo / bungalow | $310,000 | $10,850 (3.5%) | $6,200–$9,300 | ~$17,000–$20,150 |
| Conventional (3%) — entry condo / bungalow | $310,000 | $9,300 (3%) | $6,200–$9,300 | ~$15,500–$18,600 |
| FHA (3.5%) — near city median | $475,000 | $16,625 (3.5%) | $9,500–$14,250 | ~$26,125–$30,875 |
| Conventional (3%) — near city median | $475,000 | $14,250 (3%) | $9,500–$14,250 | ~$23,750–$28,500 |
| Conventional (5%) — mid-range townhome | $525,000 | $26,250 (5%) | $10,500–$15,750 | ~$36,750–$42,000 |
| Conventional (10%) — move-up / renovated | $600,000 | $60,000 (10%) | $12,000–$18,000 | ~$72,000–$78,000 |
FHA loans allow a lower down payment and are accessible to buyers with credit scores as low as 580, though most Idaho lenders prefer 620 or above. Conventional loans at 3% or 5% down require private mortgage insurance until you reach 20% equity — factor that into your monthly budget conversation with your lender.
One financial advantage Garden City buyers genuinely benefit from: Idaho's effective property tax rate of approximately 0.52% is well below the national average, which keeps carrying costs lower than in many comparable markets. The interactive mortgage calculator below this section lets you model specific monthly payments once you have a purchase price and rate in mind.
Looking to buy in Garden City? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Garden City quote.
Common First-Time Buyer Mistakes in Garden City
Mistake 1: Touring Before You Have a Pre-Approval Letter
In a market where the sale-to-list ratio hovers near 99%, showing up to a Saturday open house without financing in order is worse than a wasted afternoon — it sets an emotional anchor on a home you can't actually compete for. Get the letter first. Then tour.
Mistake 2: Waiving the Inspection on an Older Home
Pressure to waive contingencies is real in competitive offer situations, but Garden City's housing stock skews older. A mid-century bungalow in the Garden City Core or a River District property near the Greenbelt can carry deferred maintenance that costs far more than any concession you'd gain by winning the deal clean. Protecting your inspection contingency is the one thing experienced buyers wish they'd told themselves on their first purchase.
Mistake 3: Using Broader Metro Figures to Evaluate Garden City Prices
Garden City is its own municipality and its own submarket. Boise's prices, days-on-market figures, and absorption rates don't map cleanly onto Garden City's inventory. Ask your agent to pull sales data specific to Garden City — even if it means a shorter comparable set. A first-timer who anchors their expectations on broader Boise metro averages will either overpay or make offers that miss the mark entirely.
Mistake 4: Underbudgeting the Cash Needed to Close
First-time buyers frequently fixate on the down payment and forget that closing costs add another 2–3% on top of it. On a $475,000 purchase, that's an additional $9,500 to $14,250 that needs to be liquid and ready to wire before you get keys. Coming up short at the closing table — or discovering the shortfall two weeks before closing — is one of the most avoidable ways a deal falls apart. Build the full cash-needed number into your planning from the very first conversation with a lender, not after you've made an offer.
Local Expert Takeaway: Garden City rewards buyers who do the preparation work early. Get pre-approved at a local Idaho lender before you set foot in the Surel Mitchell District or walk a listing near the Greenbelt — sellers here expect it, and the market moves faster than first-timers expect. Protect your inspection contingency on any older home near the River District or Garden City Core, budget the full closing-cash number (down payment plus 2–3% in costs), and ask your agent for sales data specific to Garden City rather than leaning on broader Boise metro figures. The city's approximately 0.52% effective property tax rate and five-minute Boise commute are genuine financial advantages worth locking in — but only if you arrive at the table prepared.
Quick Takeaways & FAQs
✅ Garden City's Zillow Home Value Index of $474,544 (April 2026) sits meaningfully below many Treasure Valley suburbs, with an effective property tax rate of approximately 0.52% that keeps annual carrying costs low.
⚠️ Inventory is thin and skews older — entry-level homes in the low-to-mid $300s exist but move quickly and often need work, so buyers without a pre-approval letter and realistic condition expectations tend to lose out.
📍 Downtown Boise is about five minutes away, but Garden City is its own municipality with its own market dynamics — always ask for sales data specific to Garden City, not broader Boise metro averages.
What credit score do I need to buy a home in Garden City, Idaho?
How much cash do I actually need to buy a home in Garden City?
Is the Garden City housing market competitive for first-time buyers?
Should I get an FHA or conventional loan as a first-time buyer in Garden City?
How long does it take to close on a home in Garden City?
Moving to Idaho?
Tell us what you need help with and we'll connect you with local resources.
