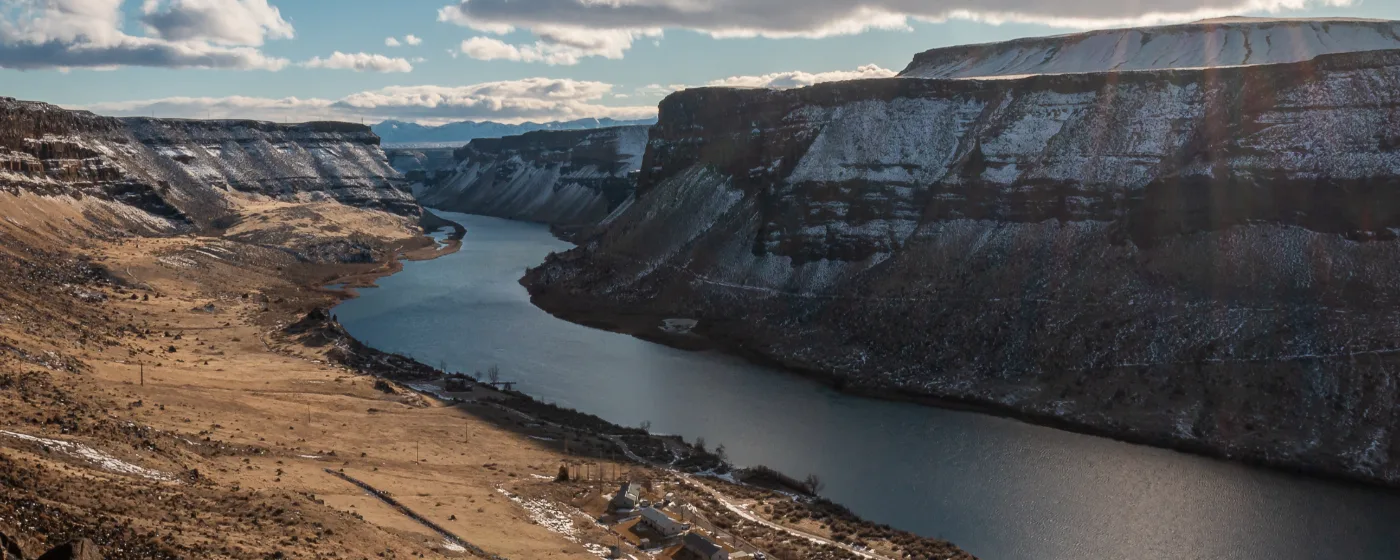
Maybe you've been priced out of Meridian or Boise and someone mentioned Kuna. Maybe your company relocated you to the Treasure Valley and you pulled up a map and thought, "Wait, how far is that?" The answer is roughly 25 minutes to downtown Boise on a normal morning — and that distance is what makes Kuna one of the more honest entry points left in Ada County for a first-time buyer. You get a real house on a real lot at prices that don't require a decade of saving, but the compromise is a longer commute than you'd have from the Boise foothills and a town that is still actively building itself out.
Kuna's growth story is written in the subdivisions spreading south of Kuna Road and along Lake Hazel — Valor, Paloma Ridge, Crimson Point, and others still in active framing. That growth means inventory is real, but it also means the town feels more unfinished than polished in spots. For a first-time buyer, that's not necessarily a bad thing: you're buying into a trajectory, not a plateau. The cost of living in Kuna is meaningfully lower than what you'd pay in Meridian for a comparable footprint, which is the core reason buyers keep choosing it over closer-in options.
The Zillow Home Value Index for Kuna sat at $462,954 as of April 2026, essentially flat year-over-year — a meaningful shift from the frenzied appreciation of 2021–2022. Homes were still going under contract in approximately 17 days on average at that point, which tells you competition hasn't evaporated, but the February 2026 data showed an average days-on-market figure of 106 days for closed sales that month, meaning patient buyers willing to negotiate have more room than they did two years ago. Idaho also has no state real-estate transfer tax, which keeps your closing costs a bit lower than buyers moving from Oregon or Washington typically expect.
Whether you're a first-timer trying to figure out if Kuna fits your budget, or you've already toured a few homes and want to understand the process more clearly, the sections below walk through what your money realistically buys here, how the purchase process works in this market, how to build your budget before you fall in love with a listing, and the specific mistakes that cost Kuna first-timers time and money.
The Kuna First-Time Buyer Reality
The Zillow Home Value Index for Kuna was $462,954 in April 2026 — use that as your anchor number. It covers both resale homes and the new-construction product filling in subdivisions along Kuna Road and Lake Hazel. For a first-timer, that figure is both the opportunity and the ceiling: you can get into Kuna without the budget you'd need in Meridian, but you're not going to find a move-in-ready three-bedroom for $300,000 anymore.
Entry-level in this market means something specific. Older resale homes — smaller lots, original finishes, no builder warranty — tend to come in below the city median, sometimes meaningfully so. New construction in active subdivisions like Patagonia or Silver Trail typically starts at or above the median, often with builder incentives that effectively substitute for a lower sticker price. Touring both resale and new-build options is not optional for a well-informed first-time buyer; the numbers look different on paper but the total cost of ownership can converge quickly.
Competition is real but not paralyzing. Homes going to pending in roughly 17 days tells you that well-priced listings do not sit — but the same February 2026 data showed 106 average days on market for that month's closed sales, which reflects a mix of fast-moving inventory and homes that needed price cuts before they sold. If a listing has been on market for 60-plus days, you have negotiating room. If it just hit the MLS with professional photos and an open house this weekend, expect other offers.
The Homebuying Process in Kuna, Step by Step
Get Pre-Approved Before You Tour Anything
This is the step most first-timers skip, and it's the one that costs them. In a market where good homes go under contract in two to three weeks, writing a competitive offer without a pre-approval letter attached is nearly impossible. A Kuna seller with two offers will almost always choose the one with lender documentation over the one that says "pre-approval coming soon."
Pre-approval takes two to four weeks if your documents — W-2s, tax returns, pay stubs, bank statements — are organized. FHA loans require a minimum 580 FICO score for the 3.5% down option; conventional financing typically starts at 620 FICO. Get the letter in hand before you schedule your first showing.
Shopping: Resale and New Construction
Active new construction in Kuna means you have two distinct tracks. With resale, you're negotiating with a seller directly — price, closing costs, possession date, repairs. With new construction, you're negotiating with a builder's sales rep, which feels different: builders rarely move on base price but frequently offer rate buydowns or closing-cost credits. Both tracks are worth your time. A buyer who only looks at one misses the full picture.
Plan four to eight weeks for the search-and-offer phase. That timeline assumes you're looking consistently, not casually checking listings once a week.
Making an Offer
Your offer will include a purchase price, earnest money (typically 1% of the purchase price in this market, held in escrow), and several contingencies. The inspection contingency and the financing contingency are the two most important for a first-timer. Do not waive them under pressure — more on that in the next section.
Seller concessions are a legitimate tool here. Under conventional financing, a seller can contribute up to 3% of the purchase price toward your closing costs; under FHA, that figure rises to 6%. On a $450,000 purchase, 3% is $13,500 toward your closing tab — a meaningful number worth negotiating for rather than ignoring.
Inspection, Appraisal, and Closing
Once your offer is accepted, you'll schedule a general home inspection within days — not weeks. Kuna has a mix of older construction and newer builds; inspection issues vary accordingly. Newer subdivisions often pass cleanly, but don't assume. Older homes near downtown Kuna sometimes surface deferred maintenance that wasn't obvious during the showing.
Your lender orders the appraisal; you don't choose the appraiser. If the home appraises below your purchase price, you'll need to negotiate with the seller, cover the gap in cash, or walk away using your financing contingency. From contract to keys typically runs 30 to 45 days. Total timeline from starting pre-approval to closing: plan on three to six months.
How Much Home Can You Afford in Kuna
The table below shows five scenarios a first-time buyer in Kuna might realistically face. Closing cost estimates use Idaho's typical 2%–2.5% range. "Cash needed at table" is down payment plus estimated closing costs — it does not include prepaid items like homeowner's insurance or escrow reserves, which your loan estimate will itemize separately. The interactive calculator below will let you model your specific monthly payment.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2%–2.5%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA 3.5% — entry resale | $380,000 | $13,300 (3.5%) | $7,600–$9,500 | ~$20,900–$22,800 |
| FHA 3.5% — city median | $462,954 | $16,203 (3.5%) | $9,259–$11,574 | ~$25,462–$27,777 |
| Conventional 3% — entry resale | $380,000 | $11,400 (3%) | $7,600–$9,500 | ~$19,000–$20,900 |
| Conventional 3% — city median | $462,954 | $13,889 (3%) | $9,259–$11,574 | ~$23,148–$25,463 |
| Conventional 5% — new construction | $480,000 | $24,000 (5%) | $9,600–$12,000 | ~$33,600–$36,000 |
| Conventional 10% — stronger equity start | $462,954 | $46,295 (10%) | $9,259–$11,574 | ~$55,554–$57,869 |
Idaho has no state real-estate transfer tax, which keeps these closing cost estimates a bit leaner than buyers from California or Oregon expect. On the property tax side, Kuna's effective rate is approximately 0.76% — a line item worth building into your total housing budget before you commit to a purchase price.
One more lever worth knowing: sellers can contribute toward your closing costs as part of the negotiation. If you're stretching to cover the cash-at-table figure, asking for a seller concession — rather than lowering the purchase price — is often the more efficient move.
Looking to buy in Kuna? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Kuna quote.
Common First-Time Buyer Mistakes in Kuna
Touring Before Pre-Approval
This one is worth repeating because it still trips up a significant share of first-timers in this market. Falling in love with a home in Paloma Ridge or Indian Creek Ranch and then spending two weeks scrambling for lender documentation is a reliable way to lose that home to a buyer who had their paperwork ready. Get the letter first. Then tour.
Waiving the Inspection Contingency
At the peak of the 2021–2022 market, buyers waived inspection contingencies routinely to win bidding wars. That practice hasn't fully died. In Kuna, where new subdivisions coexist with older stock near downtown, waiving the inspection to be competitive is a gamble with real downside. A buyer who skips the inspection on an older resale home and later discovers foundation settling or an aging HVAC system owns that repair cost entirely. Keep the contingency. If a seller won't accept an offer with a standard inspection clause, that tells you something about the seller's confidence in the home.
Underestimating Cash Needed at Closing
Many first-timers budget for the down payment and forget that closing costs are a separate line item. In Idaho, expect 2% to 2.5% of the purchase price due at closing on top of your down payment. On a $462,000 purchase, that's roughly $9,000 to $11,500 in closing costs alone. Add prepaid homeowner's insurance and initial escrow reserves, and the cash-at-table figure can surprise buyers who planned only for the down payment number.
Ignoring the Commute Before You Sign
Kuna sits about 25 minutes from downtown Boise under normal conditions. That's manageable. But "normal conditions" doesn't account for construction on State Highway 45, the merge onto I-84, or the reality that the drive compounds daily. Buyers who tour homes on a Saturday afternoon and never drive the actual commute route at 7:30 a.m. on a Tuesday sometimes find month three of homeownership more exhausting than they expected. Do the commute test before you go under contract — not after.
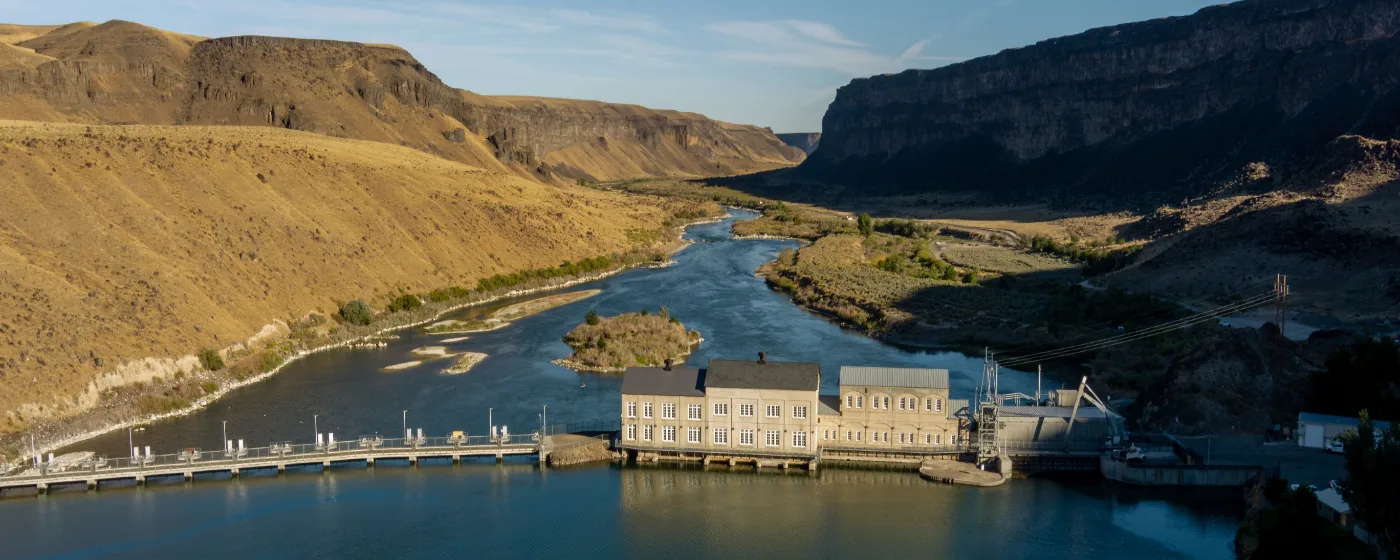
Local Expert Takeaway: Kuna is genuinely one of the more accessible entry points left in Ada County, but 'accessible' still means having $20,000 to $36,000 in liquid cash depending on your loan type and purchase price — and having that pre-approval letter in hand before you walk through your first door on Kuna Road. The market has slowed enough that patient buyers can negotiate, but well-priced homes in active subdivisions like Valor and Patagonia still move in days, not months. Get your financing documented first, budget honestly for closing costs on top of your down payment, and do the actual Boise commute run at rush hour before you fall in love with a listing.
Quick Takeaways & FAQs
✅ Kuna's Zillow Home Value Index of $462,954 (April 2026) is meaningfully lower than comparable homes in Meridian, making it one of the last realistic Ada County entry points for first-time buyers.
⚠️ Cash needed at closing in Kuna typically runs $20,000–$36,000+ depending on loan type and purchase price — buyers who budget only for the down payment are regularly caught short.
📍 Homes in Kuna were going to pending in approximately 17 days as of April 2026, meaning pre-approval documentation is not optional — it's the difference between writing an offer and watching someone else get the house.
What credit score do I need to buy a home in Kuna, Idaho?
How much do I need saved to buy a home in Kuna?
How long does it take to buy a home in Kuna from start to finish?
Is Kuna a buyer's or seller's market right now?
Should I buy new construction or resale in Kuna?
Moving to Idaho?
Tell us what you need help with and we'll connect you with local resources.
