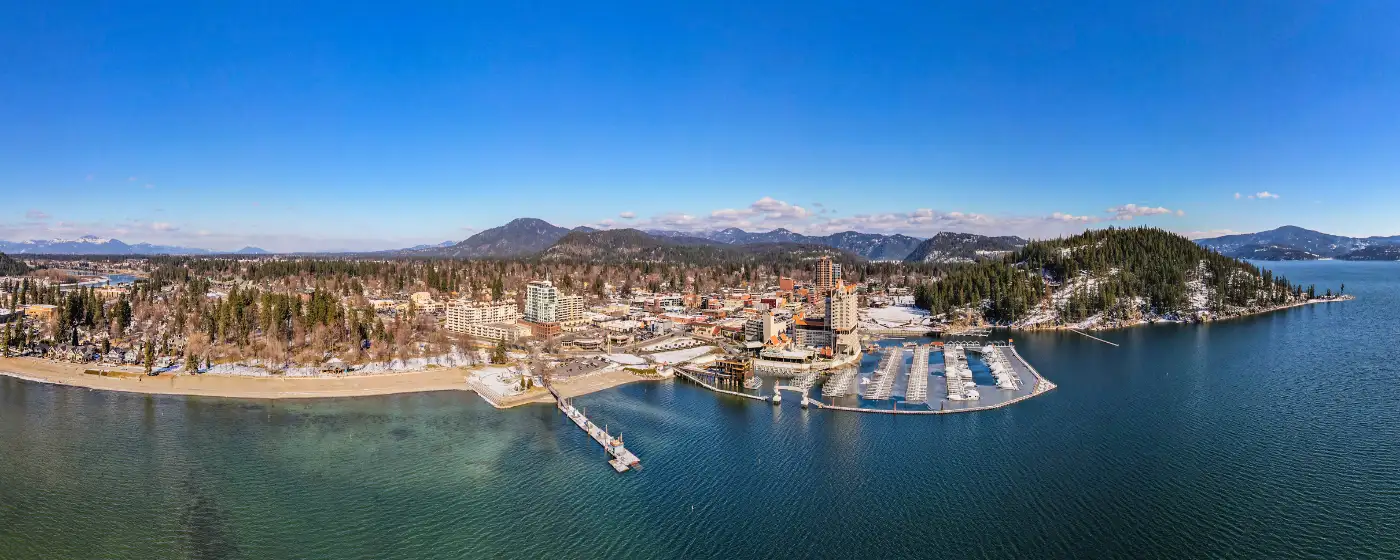
Maybe someone told you Coeur d'Alene is more affordable than the Pacific Northwest cities you've been watching. That's true — but only relative to Seattle or Portland. Compared to the national median, this is a premium market, and first-time buyers who arrive expecting starter-home prices in the low $300s leave disappointed. The Zillow Home Value Index for Coeur d'Alene sat at $545,000 as of May 2026, up 3.1% year-over-year, and the three-month median sale price tracked by Redfin through June 2026 ran even higher at $590,000. The lake, the resort-town draw, and a steady wave of in-migration from California, Washington, and Oregon have collectively pushed prices well past what a typical North Idaho income alone can carry — and that gap is the first reality every first-timer needs to sit with.
Coeur d'Alene draws buyers from across the inland West for a mix of reasons — outdoor access, relative affordability compared to coastal markets, and a lifestyle that's hard to replicate in a bigger city. But the median household income here is $72,338, which means most first-time buyers are stretching, counting on dual incomes, or bringing equity from a previous market. Spokane, Washington — roughly 30 minutes west on I-90 — offers meaningfully lower price points, and some buyers use that comparison as leverage to negotiate or as a genuine alternative. Understanding which city actually fits your budget before you fall in love with a specific address matters more here than in most markets.
On the positive side, inventory is improving. Kootenai County active listings climbed from 580 in February 2026 to 917 by June 2026, giving buyers more comparison power than the region has seen in recent years. Homes are still moving — averaging 22 days on market through June 2026 — but the frantic multiple-offer environment of 2021–2022 has eased. That means a prepared, pre-approved first-timer has a realistic shot at winning a home without waiving every protection. The North Idaho Centennial Trail, McEuen Park, City Park and Beach, and Tubbs Hill aren't just weekend amenities; they're part of why people keep choosing this city over cheaper alternatives nearby, and why prices here hold their ground. For more on what daily life and overall costs look like, see the cost of living in Coeur d'Alene page.
Whether you're a Spokane renter looking to plant roots on the Idaho side, a remote worker whose budget finally cleared $500K, or someone who grew up here and is buying for the first time, this guide walks through what your budget realistically buys, how the purchase process works locally, what cash you need at the table, and the specific mistakes that cost first-timers the most in this market.
The Coeur d'Alene First-Time Buyer Reality
The Zillow Home Value Index puts the city median at $545,000 as of May 2026 — and that number is doing a lot of work. It blends older ranch homes with lakefront properties and resort-adjacent condos near Downtown. For a first-time buyer, the honest framing is that true entry-level inventory is scarce and moves quickly; anything priced well below the median tends to attract immediate competition or requires significant work.
Below $400,000, the options thin dramatically. You're looking at condos with HOA fees, homes that need significant renovation, or properties on the edges of the city's boundaries. Above $550,000, the inventory broadens, but so does the down-payment math. That spread — between what entry-level looks like and what the median reflects — is wider in Coeur d'Alene than in nearby Post Falls or Rathdrum, both of which offer more inventory at lower price points for buyers willing to commute.
The market is competitive but not impossible. Homes averaged 22 days on market through June 2026, which gives a prepared buyer enough time to schedule showings, do basic due diligence, and write a reasoned offer — provided the pre-approval letter is already in hand. Well-priced listings in desirable pockets still draw multiple offers on weekends. The buyers who lose those homes are almost always the ones who called a lender on Saturday morning after seeing the listing Friday night.
The Homebuying Process in Coeur d'Alene, Step by Step
Step 1: Get Pre-Approved — Before You Tour Anything
This is not a formality in Coeur d'Alene. The full purchase process in Idaho typically runs 30 to 60 days from pre-approval to closing, and well-priced listings here can go under contract in under three weeks. Touring homes without a pre-approval letter means you're building emotional investment in properties you can't actually move on. Get the letter first — then schedule showings.
Shop at least two or three lenders. Idaho mortgage rates vary meaningfully by lender; the 30-year fixed was approximately 6.75% through Zillow Home Loans as of early August 2026, while other sources cited closer to 6.92% for the same period. That spread affects your monthly payment more than most buyers realize, and first-timers often accept the first offer they receive out of anxiety about the process.
Step 2: Define Your Search Area Honestly
Coeur d'Alene's neighborhoods each carry different practical realities — proximity to Highway 95, distance from the lake, and access to daily conveniences. Before you start touring, know which part of the city fits your commute, your priorities, and your price ceiling. Buyers who skip this step end up making offers on homes they'll regret or passing on good values because they've mentally fixated on an area they can't afford.
Step 3: Make Offers With Eyes Open
Idaho uses a standard real estate purchase agreement, and most offers in this market are negotiated — not surrendered. Sellers in Coeur d'Alene have benefited from years of appreciation and are often expecting full-price or near-full-price offers, but they're not immune to market reality. In the current environment, with inventory up significantly from early 2026, buyers have more standing to negotiate on price, closing costs, or possession date than they did two years ago.
Step 4: Inspection and Appraisal
Never waive the inspection contingency on a Coeur d'Alene home without understanding exactly what you're giving up. North Idaho homes deal with hard winters, and deferred maintenance on roofing, HVAC, and foundation waterproofing is common — particularly in older parts of the city. A $500 inspection can surface $15,000 in issues.
The appraisal is ordered by your lender and evaluated against recent comparable sales. If the home appraises below your offer price, you'll need to negotiate with the seller, cover the gap in cash, or walk away. In a rising market, appraisal gaps were a routine headache; with the market more balanced now, they're less frequent but still possible on aggressively priced listings.
Step 5: Closing
Idaho is an escrow state, meaning a title company or escrow officer manages the closing — not an attorney. Expect closing to take 30 to 45 days from mutual acceptance of the offer, assuming no appraisal issues or lender delays. Closing costs typically run 2%–3% of the purchase price and are due at the table, on top of your down payment. Budget for both together — they are not the same line item.
How Much Home Can You Afford in Coeur d'Alene
The table below shows approximate cash requirements at the table for several realistic entry-point scenarios. These are estimates using illustrative rate assumptions — your lender will give you exact figures based on your credit profile, loan terms, and the specific property. The interactive calculator below the table lets you adjust for your own down payment and rate.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–3%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — Entry-Level | $420,000 | $14,700 (3.5%) | $8,400–$12,600 | ~$23,000–$27,000 |
| Conventional (3%) — Entry-Level | $420,000 | $12,600 (3%) | $8,400–$12,600 | ~$21,000–$25,000 |
| FHA (3.5%) — City Median | $545,000 | $19,075 (3.5%) | $10,900–$16,350 | ~$30,000–$35,000 |
| Conventional (3%) — City Median | $545,000 | $16,350 (3%) | $10,900–$16,350 | ~$27,000–$33,000 |
| Conventional (10%) — Mid-Range | $545,000 | $54,500 (10%) | $10,900–$16,350 | ~$65,000–$71,000 |
| Conventional (20%) — City Median, No PMI | $545,000 | $109,000 (20%) | $10,900–$16,350 | ~$120,000–$125,000 |
FHA financing is available in Kootenai County at loan limits above the national floor — confirm the current county limit with your lender before shopping, since it affects how high an FHA offer can go here. Private mortgage insurance applies to conventional loans with less than 20% down and adds to your monthly obligation; your lender can quote the specific PMI rate for your scenario.
Closing costs on the buyer's side typically include lender origination fees, title insurance, escrow fees, prepaid homeowners insurance, and prepaid interest. Sellers in Coeur d'Alene sometimes agree to contribute toward buyer closing costs, especially on homes that have sat longer — worth asking for in your offer rather than assuming.
Looking to buy in Coeur d'Alene? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Coeur d'Alene quote.
Common First-Time Buyer Mistakes in Coeur d'Alene
Touring Before You Have a Pre-Approval Letter
This one costs first-timers more heartbreak than any other. A Saturday open house near McEuen Park can generate real emotional attachment — and if a competing buyer with a pre-approval letter makes an offer Monday morning, you're watching from the sideline. Get the letter before you tour. It takes a few days, not a few hours, if you're doing it properly.
Underestimating Total Cash Required
Most first-timers calculate their down payment and stop there. Closing costs run an additional 2%–3% of the purchase price in Idaho, and on a $545,000 home, that's another $10,900 to $16,350 due at the table — separate from your down payment. Add moving costs, a reasonable repair reserve for a home that's been through North Idaho winters, and the first-year costs of establishing a household, and the gap between "I have the down payment" and "I'm ready to close" is larger than it looks on a spreadsheet.
Waiving the Inspection Contingency Without Real Justification
During peak competition in 2021 and 2022, waiving inspections became almost routine in Coeur d'Alene. The market has since moderated. Waiving inspection on an older home where deferred maintenance is genuinely common — to win a bidding war that may not even materialize — is a risk that rarely pays off. If a seller requires inspection waiver as a non-negotiable, factor that unknown liability into your offer price, not your emotional attachment to the property.
Ignoring the Post Falls and Hayden Alternatives
First-time buyers locked onto Coeur d'Alene's zip code sometimes pass over meaningfully lower prices in Post Falls or Hayden without seriously running the numbers. Both cities are within easy commuting distance along the US-95 corridor, and inventory at sub-$450,000 is more plentiful there. If your budget is stretched thin, touring those markets before committing to a Coeur d'Alene search isn't settling — it's smart math. Buyers who skip this comparison sometimes realize six months after closing that they bought more house stress than they needed to.
Accepting the First Mortgage Rate You're Quoted
Idaho lenders are not a monolith. The spread between the best and worst rate quote a first-time buyer might receive on the same loan product in the same week can be meaningful — enough to matter across a 30-year term. Rate shopping feels uncomfortable for first-timers who worry it will affect their credit, but multiple mortgage inquiries within a short window (typically 14–45 days, depending on the scoring model) are treated as a single inquiry. Call three lenders. Compare the loan estimate forms side by side. The few hours spent doing this is among the highest-return activity in the entire process.
Local Expert Takeaway: In Coeur d'Alene, the buyers who close on their first home aren't necessarily the ones with the most money — they're the ones who showed up pre-approved, understood their true cash needs before touring, and didn't wait for a perfect market. With Kootenai County inventory at its highest point in years and homes averaging 22 days on market as of mid-2026, a prepared first-timer has a genuine window right now. The catch: at a $545,000 city median, you need to be honest about whether Coeur d'Alene proper, or a nearby Post Falls or Hayden address, actually fits what you've saved and what you earn. That conversation — budget before wishlist — is the one that separates buyers who close from buyers who keep looking.
Quick Takeaways & FAQs
✅ Kootenai County active listings hit 917 in June 2026 — the highest inventory first-time buyers have had to work with in years, giving you real comparison power.
⚠️ The city median sits at $545,000 (Zillow Home Value Index, May 2026), and true entry-level inventory is limited — budget honestly for Post Falls or Hayden if Coeur d'Alene's price points are a stretch.
📍 Homes here averaged 22 days on market through June 2026, which means a pre-approval letter isn't a nice-to-have — a well-priced listing can go under contract before your weekend showing.
What credit score do I need to buy a home in Coeur d'Alene as a first-time buyer?
How long does it take to buy a home in Coeur d'Alene from start to finish?
Is it better to buy in Coeur d'Alene or in Post Falls for a first-time buyer?
What are typical closing costs for a home purchase in Coeur d'Alene?
Can I use an FHA loan to buy a home in Coeur d'Alene at the current median price?
Moving to Idaho?
Tell us what you need help with and we'll connect you with local resources.
