Maybe your spreadsheet pointed you here because Boise and Meridian stopped making sense on your income. Maybe a coworker mentioned Caldwell had prices that hadn't yet caught up to the rest of the Treasure Valley. Either way, you've landed in one of the few places in southwestern Idaho where a first-time buyer can still connect a realistic income to a real purchase — without stretching into loan territory that keeps you up at night. The Zillow Home Value Index puts Caldwell's typical home price at $405,784 (2026), the lowest among the major Treasure Valley cities, and that gap is the single biggest reason buyers keep moving westward from Boise along I-84.
That affordability is real, but it comes with competition you should understand before you start touring. Out-of-state buyers from Seattle, Los Angeles, and the San Francisco metro ranked as the top external searchers targeting Caldwell in late 2025 — many arriving pre-approved or carrying cash. On the motivated end of the local market, Redfin describes conditions as 'somewhat competitive,' with desirable homes going pending in roughly 19 days. The median household income in Caldwell is $73,058, yet estimates suggest you typically need income in the low-to-mid $80,000s to qualify comfortably at the current median price with a standard down payment. That gap is real, and it means loan program selection and credit preparation matter more here than the headline price suggests.
The good news for first-timers is structural: Caldwell's median price sits well below the 2026 FHA loan limit of $586,500 for Canyon County, meaning virtually every home in the city is accessible through FHA financing. New construction has added genuine supply to a market that historically ran thin on inventory, and as of August 2026, MLS inventory had climbed to 342 active listings, up sharply from 257 in late winter, giving buyers more options and slightly more negotiating room than the prior two years allowed. For a full picture of what that price means against day-to-day costs, see the cost of living in Caldwell page.
Whether you're six months away from being ready or actively comparing lenders, the sections below walk through what your budget actually buys in Caldwell, the step-by-step purchase process, a concrete affordability snapshot by scenario, and the specific mistakes that tend to cost first-timers the most in this particular market.
The Caldwell First-Time Buyer Reality
At a Zillow Home Value Index of $405,784 (2026), Caldwell is the Treasure Valley's clearest entry point — and that matters more than it sounds. In practical terms, it means a first-time buyer using an FHA loan with 3.5% down is financing a purchase that still clears the Canyon County FHA limit by a significant margin, without the financial gymnastics that the same scenario requires in Nampa or Meridian.
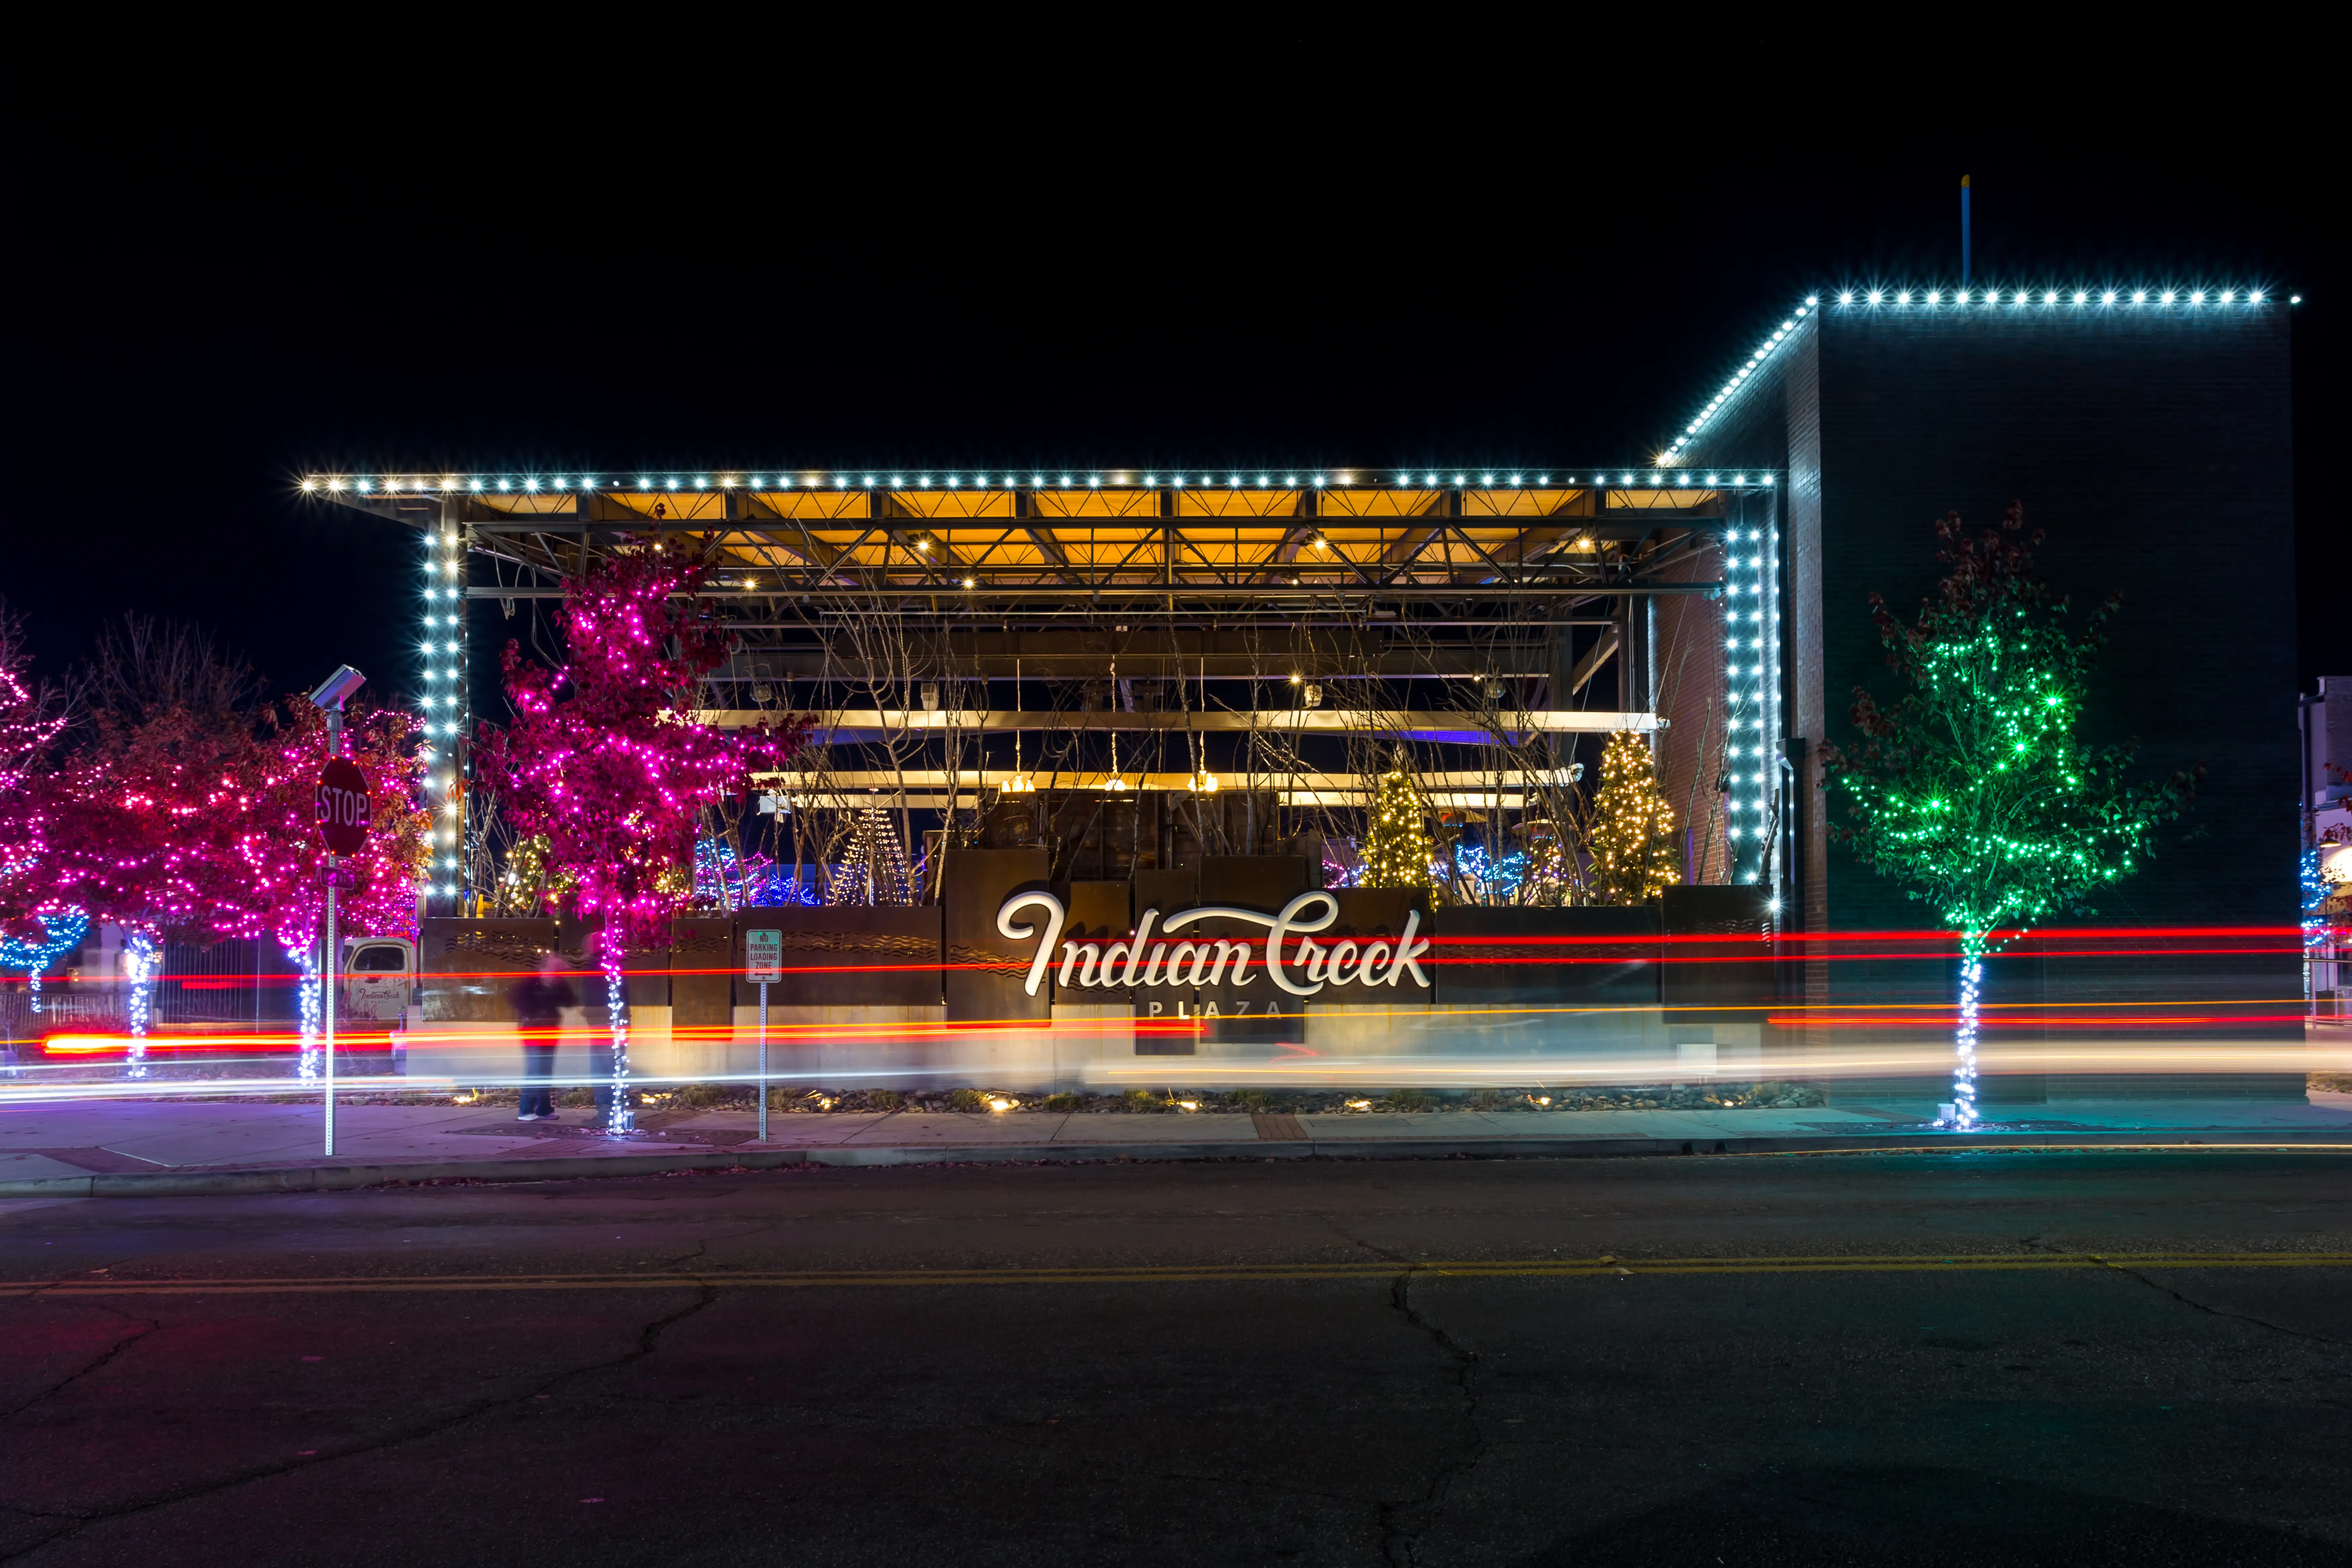
What that price actually buys varies across the city. Downtown Caldwell and the area near Indian Creek Plaza carry older homes — some with real character, others with deferred maintenance that an inspection will surface quickly. The city's newer construction corridors offer turnkey options for buyers who'd rather not inherit someone else's renovation list; those areas have seen the strongest inventory growth in the current cycle.
The income-to-price tension is the honest part of this picture. Caldwell's median household income of $73,058 is genuinely below the threshold most lenders want to see for comfortable qualification at the city's median price. That doesn't mean it's impossible — it means the difference between a smooth approval and a stressful one often comes down to credit score, debt load, and how aggressively you've saved. Buyers who spend six months paying down revolving balances and building reserves before they apply consistently report a better experience than those who walk into a lender's office cold.
The Homebuying Process in Caldwell, Step by Step
Step 1: Get Pre-Approved Before You Look at a Single House
This is not a formality in Caldwell — it's the price of entry. When a desirable home goes pending in 19 days, a seller has no reason to consider an offer without documented financing. Pre-approval (not pre-qualification) means a lender has pulled your credit, verified income and assets, and issued a conditional commitment. That document is what gets your offer read seriously.
Step 2: Define Your Search Parameters Honestly
Before you tour anything, settle your geographic priorities: how far from downtown you're comfortable going, whether new construction or resale fits your timeline, and which parts of the city align with your daily routine. Those filters will narrow your search more usefully than price alone.
Step 3: Work With a Local Agent and Make Offers Decisively
An agent who knows Caldwell specifically — not just the broader Treasure Valley — will flag the due-diligence items that trip up first-timers here: irrigation shares attached to a property, canal easements that limit what you can build, and taxing district overlays that affect your actual property tax bill independently of city boundaries. These are not theoretical concerns; they show up regularly in Canyon County transactions.
Step 4: Inspection and Appraisal — Do Not Skip Either
The inspection contingency is the one first-timers in competitive markets are most often pressured to waive or shorten. In Caldwell's older housing stock — particularly anything near Downtown — this is a mistake. Older plumbing, original electrical panels, and aging HVAC systems are common findings. A five-day inspection window is already tight; waiving it entirely is a financial risk that outweighs the competitive edge it provides.
The appraisal follows the inspection and is ordered by your lender. If the appraised value comes in below purchase price — which happens, especially on renovated homes priced optimistically — you'll need to negotiate with the seller, cover the gap in cash, or walk away. Know in advance which of those you're willing to do.
Step 5: Closing in Canyon County
Idaho is a title-company state, not an attorney-state, so your closing will typically happen at a title company office. Plan for roughly 3% to 4% of the purchase price in closing costs, covering lender fees, title insurance, prepaid taxes, and homeowners insurance escrow setup. You'll receive a closing disclosure at least three business days before your signing date — read it against your loan estimate line by line, not just the bottom number.
How Much Home Can You Afford in Caldwell
The table below shows estimated cash requirements at closing under several common scenarios at Caldwell price points. Down payment percentages and closing cost estimates are approximations for planning — your lender will issue exact figures on your loan estimate. All figures assume the buyer is financing; the engine's mortgage calculator below will run payment estimates against current rates.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (3–4%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — entry-level resale | $320,000 | $11,200 (3.5%) | $9,600–$12,800 | ~$21,000–$24,000 |
| FHA (3.5%) — city median | $405,784 | $14,202 (3.5%) | $12,173–$16,231 | ~$26,000–$31,000 |
| Conventional (3%) — city median | $405,784 | $12,173 (3%) | $12,173–$16,231 | ~$24,000–$29,000 |
| Conventional (5%) — city median | $405,784 | $20,289 (5%) | $12,173–$16,231 | ~$32,000–$37,000 |
| FHA (3.5%) — upper end of market | $450,000 | $15,750 (3.5%) | $13,500–$18,000 | ~$29,000–$34,000 |
| Conventional (10%) — strong credit buyer | $450,000 | $45,000 (10%) | $13,500–$18,000 | ~$58,500–$63,000 |
FHA loans carry mortgage insurance premiums — an upfront premium typically rolled into the loan balance, plus a monthly premium — which affect your long-run cost relative to conventional financing. If your credit score is above 700 and you can reach 5% down, run both scenarios with your lender before committing to a loan type.
One number worth internalizing: the effective property tax rate in Caldwell is approximately 0.57%, one of the lower rates in the region — though your actual bill will depend on which taxing districts overlay your specific parcel, not just the city rate. Full cost-of-living context lives at cost of living in Caldwell.
Looking to buy in Caldwell? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Caldwell quote.
Common First-Time Buyer Mistakes in Caldwell
Shopping Before You Have Pre-Approval in Hand
In a market where motivated sellers can accept an offer within days, touring homes without pre-approval is not just inefficient — it's a setup for heartbreak. The buyer who falls in love with a house on Thursday and then spends two weeks getting a lender to pull their credit is not the buyer who gets that house. Get the letter first, then set the alerts.
Waiving the Inspection Contingency on Older Housing Stock
The pressure to be 'competitive' pushes some first-timers to shorten or drop the inspection period. Downtown Caldwell and areas with older housing stock can have findings — aging electrical panels, older plumbing, original HVAC — that are not cosmetic. Waiving inspection to win a $330,000 house and then discovering a $25,000 electrical upgrade is required is a painful and avoidable outcome.
Underestimating the Cash Needed at Closing
The down payment is only part of the equation. Closing costs in Canyon County typically run 3% to 4% of the purchase price, and first-timers frequently budget only for the down payment. At the city's current price levels, that oversight can mean arriving at the closing table $12,000 to $16,000 short of what's actually needed. Build the full closing cost estimate into your savings target from day one.
Missing Caldwell-Specific Due Diligence Items
Canyon County has a set of property characteristics that rarely appear in buyer guides written for other markets. Irrigation water shares — which may or may not transfer with a sale — can have real value and real cost. Canal easements running through a lot affect what you can build or plant near them. Taxing district overlays determine your actual property tax bill, and they vary parcel by parcel in ways the county's base rate won't predict. Ask your agent to walk through every one of these on any property you're seriously considering — and if your agent looks puzzled when you raise them, that tells you something useful about their local experience.
Skipping the Loan Comparison Step
Many first-timers go with the first lender who says yes. In Caldwell, where FHA and conventional programs are both broadly available and the price point keeps most purchases within accessible financing ranges, the difference between two lenders' rates and fee structures on a $405,000 loan can add up to thousands of dollars over the life of the loan. Get at least two loan estimates before you lock anything.
Local Expert Takeaway: Caldwell is the Treasure Valley's most accessible first-time buyer market on price, but the path here rewards preparation over speed. Get fully pre-approved before you walk through a single door, and budget the full 3–4% closing cost estimate alongside your down payment — not as an afterthought. New construction builders in Caldwell are often more open to negotiations on rate buy-downs and closing cost contributions than resale sellers tend to be, so if your timeline is flexible, that's worth exploring. And if you're shopping near Indian Creek Plaza or older parts of the city, treat the inspection as non-negotiable — the character of those neighborhoods comes with mechanical systems that need a professional set of eyes before you commit.
Quick Takeaways & FAQs
✅ At a Zillow Home Value Index of $405,784 (2026), Caldwell carries the lowest entry price among major Treasure Valley cities — and virtually every home in the city qualifies for FHA financing under Canyon County's $586,500 limit.
⚠️ The income-to-price gap is real: Caldwell's median household income of $73,058 falls below the low-to-mid $80,000s typically needed to qualify comfortably at the current median price, making credit prep and loan program selection critical steps before you apply.
📍 Canyon County has property-specific quirks — irrigation shares, canal easements, and taxing district overlays — that rarely appear in generic buyer checklists but show up regularly in local transactions; ask about all three before you make an offer.
What credit score do I need to buy a home in Caldwell, Idaho?
How long does it take to buy a home in Caldwell from offer to close?
Is the Caldwell housing market good for first-time buyers right now?
What are closing costs on a home purchase in Caldwell?
Are there irrigation rights or other Canyon County quirks I should know before buying in Caldwell?
Moving to Idaho?
Tell us what you need help with and we'll connect you with local resources.
