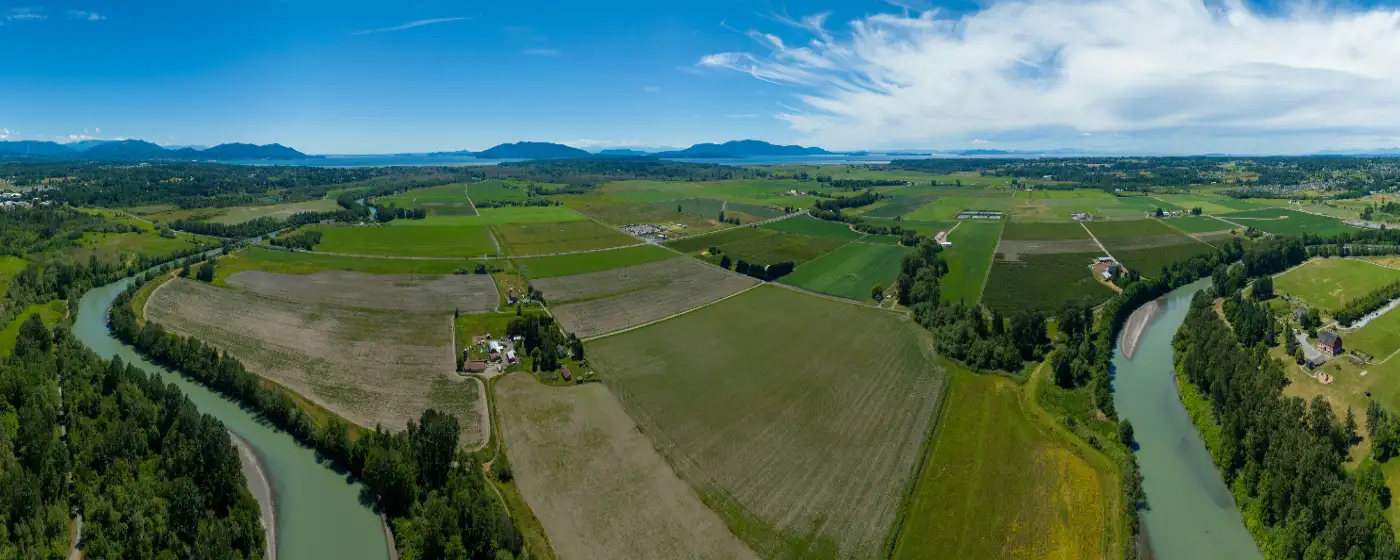
Maybe you've been renting in Bellingham and someone mentioned Ferndale as the place where your dollar still buys a real house. Maybe you've been watching Whatcom County listings for six months and you're starting to understand the geography. Either way, here's the thing first-timers don't expect: Ferndale is not a fallback option. It's a city of roughly 16,700 people with its own downtown on Main Street, two refinery-anchored employers that create genuine household income in the area, and a market that has quietly appreciated to a Zillow Home Value Index of $600,714 as of June 2026 — a figure that surprises people who assumed they'd find bargain pricing north of Bellingham.
The median household income in Ferndale sits at $87,579, which reflects the presence of industrial and public-sector wages from Phillips 66 and BP Cherry Point, along with Whatcom County government. That income base keeps the market competitive. Families with school-age children move here specifically for the local schools, and the city's relative affordability compared to Bellingham draws buyers who want more square footage without crossing into rural Lynden or Blaine. The buyer pool is real, and sellers know it. For a full breakdown of what life here costs day to day, see the cost of living in Ferndale page.
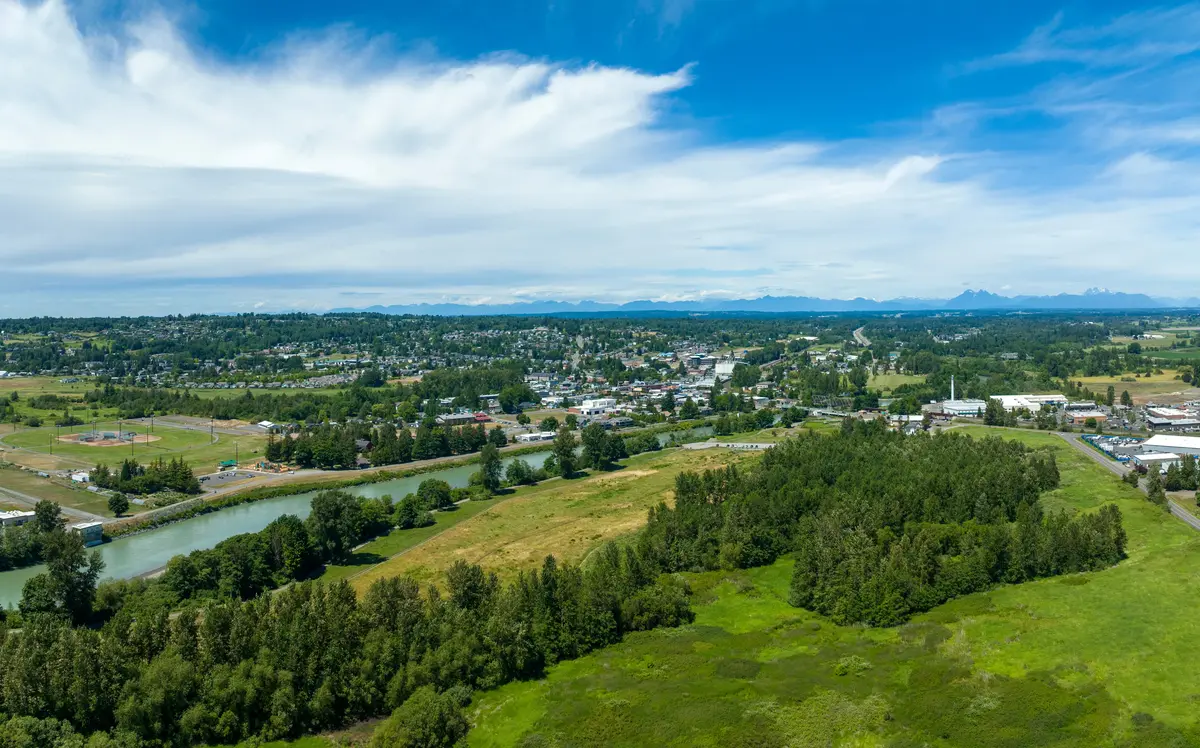
On the lifestyle side, Ferndale offers proximity to Pioneer Park and Hovander Homestead Park for weekend routines, a historic downtown along Main Street, and a self-contained small-city feel that Bellingham — with its university traffic and tighter inventory — simply can't replicate. Car ownership is non-negotiable here; there's no meaningful transit link to Bellingham, and most households run two vehicles. The Bellingham commute runs about 20 minutes on I-5 under normal conditions, which shapes where buyers focus their search.
Whether you're making your first offer or still figuring out what you can actually afford, the sections below walk through the Ferndale first-time buyer reality, the step-by-step purchase process, a concrete budget table, and the specific mistakes that cost first-timers deals in this market.
The Ferndale First-Time Buyer Reality
The Zillow Home Value Index for Ferndale is $600,714 as of June 2026 — up a modest 0.1% year-over-year, which signals stability rather than a runaway market. That figure is the floor, not a bargain bin. Entry-level resale homes in older construction tend to cluster in the low-to-mid $500s when they appear, but they move quickly and in decent condition.
New construction is a different calculation entirely. The median closed price for new single-family homes in Ferndale over the past six months is $727,488, and active floor plans across Ferndale's 11 new-home communities from five builders are priced from approximately $649,990 to $879,450. If you're a first-timer drawn to the idea of buying new — no deferred maintenance, builder warranties — budget accordingly. The premium over resale is real.
The market pace sits at roughly 41 days to pending, which is brisk but not chaotic. You have time to think, but not time to drag your feet. The average sale-to-list price ratio is 99.9%, meaning sellers are getting almost exactly what they ask. Lowball offers are a waste of everyone's time here. With approximately 3.87 months of housing supply as of early June 2026, this is a fairly balanced market — not the frenzied bidding-war environment of 2021, but not a place where sellers are desperate either. First-timers who come in expecting to negotiate 5% below asking will be disappointed.
The Homebuying Process in Ferndale, Step by Step
Step 1: Get Pre-Approved — Before You Tour Anything
Washington lenders typically require a minimum credit score of 620 (some programs push that to 640) and a debt-to-income ratio of 45–50% for conventional approval. Pull your credit report and fix errors before you apply — not after you fall in love with a house in Cascadia or Malloy Village. A pre-approval letter from a local or regional lender carries more weight with Ferndale sellers than a letter from an online-only lender they've never heard of.
One thing most first-timers don't know: Washington State defines a first-time homebuyer as anyone who hasn't owned a home in the past three years. If you owned a home years ago and sold it, you may still qualify for first-time buyer loan products. It's worth asking your lender directly.
Step 2: Shop Within Your Pre-Approved Range
Use your pre-approval ceiling as a hard cap, not a target. In Ferndale's $600,000+ market, the difference between your ceiling and what you're comfortable paying monthly matters more than it sounds. Focus your search on specific areas — the Vista Drive corridor, Ferndale Heights, or The Meadows — based on what your commute and household priorities require, not just what looks good online.
Step 3: Write a Clean Offer on NWMLS Form 21
All Washington residential offers use NWMLS Form 21, the Residential Purchase & Sale Agreement. It covers purchase price, earnest money, contingencies, included items, and closing date. Earnest money is typically due within two business days of acceptance — have those funds liquid and ready before you write anything. In Ferndale's near-list-price environment, a well-structured offer with a reasonable closing timeline often matters as much as the number at the top.
The step first-timers most often get wrong: waiving contingencies to compete when they don't need to. With 3.87 months of supply, most Ferndale sellers are not receiving five competing offers. An inspection contingency and a financing contingency are reasonable to keep. Save the contingency-waiving for a true multiple-offer situation your agent confirms in real time.
Step 4: Inspection, Appraisal, and the Gap
Schedule your inspection within the contingency window — typically 10 days in Washington. Western Washington's wet winters mean older Ferndale homes can surface deferred maintenance issues that a thorough inspection catches before they become expensive surprises after closing. Budget mentally for a negotiation after the inspection report, not panic.
The appraisal follows lender ordering, usually after mutual acceptance. If the appraised value comes in below purchase price, you'll need to cover the gap in cash, renegotiate with the seller, or walk away. This happens rarely in a balanced market, but first-timers are sometimes blindsided by it — know your plan before it happens.
Step 5: Closing
Washington closings are handled by escrow companies, not attorneys. You'll sign a substantial stack of documents — expect two to three hours — and your down payment plus closing costs must be wired before closing day. Final walkthrough of the property happens within the 24–48 hours before closing. Once the deed records with Whatcom County, the home is yours.
How Much Home Can You Afford in Ferndale
The table below shows what different entry points look like at closing — the cash you need to actually sit down and sign. These are estimates based on purchase price and loan type; the interactive calculator below will generate payment estimates based on your specific rate and terms.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — entry resale | $520,000 | ~$18,200 (3.5%) | ~$10,400–$15,600 (2–3%) | ~$28,600–$33,800 |
| Conventional (3%) — entry resale | $520,000 | ~$15,600 (3%) | ~$10,400–$15,600 (2–3%) | ~$26,000–$31,200 |
| FHA (3.5%) — near city median | $600,000 | ~$21,000 (3.5%) | ~$12,000–$18,000 (2–3%) | ~$33,000–$39,000 |
| Conventional (3%) — near city median | $600,000 | ~$18,000 (3%) | ~$12,000–$18,000 (2–3%) | ~$30,000–$36,000 |
| Conventional (5%) — above median | $650,000 | ~$32,500 (5%) | ~$13,000–$19,500 (2–3%) | ~$45,500–$52,000 |
| Conventional (10%) — new construction entry | $727,000 | ~$72,700 (10%) | ~$14,500–$21,800 (2–3%) | ~$87,200–$94,500 |
Closing costs in Washington typically run 2–3% of the purchase price and include lender fees, title insurance, escrow fees, prepaid interest, and homeowners insurance at funding. The effective property tax rate in Ferndale is approximately 0.71%, which your lender will factor into your escrow impound account.
Down payments below 20% trigger private mortgage insurance (PMI) on conventional loans until you reach 20% equity. FHA loans carry a mortgage insurance premium (MIP) for the life of the loan in most cases — ask your lender whether refinancing to conventional later makes sense for your situation. VA and USDA loans offer 0% down for eligible borrowers and carry no PMI, making them worth exploring if you have qualifying military service or are purchasing in a USDA-eligible area.
The Washington State Housing Finance Commission offers 30-year fixed-rate loan products — FHA, VA, USDA, or conventional — available through approved lenders statewide. Ask any Whatcom County lender whether you qualify; eligibility is broader than most first-timers assume, since Washington counts anyone who hasn't owned in the past three years as a first-time buyer.
Looking to buy in Ferndale? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Ferndale quote.
Common First-Time Buyer Mistakes in Ferndale
Shopping Before You Have a Pre-Approval Letter
Touring homes in Malloy Village or Ferndale Heights before you have a pre-approval letter is the single fastest way to waste everyone's time — including yours. In a market where homes go pending in around 41 days, the gap between "we should probably talk to a lender" and "we found the one" can cost you the house. Sellers here will not hold a property while you get your financing sorted out after the fact.
Underestimating the Cash You Need at Closing
First-timers routinely budget for the down payment and forget that closing costs in Washington add another 2–3% on top. On a $600,000 purchase, that's $12,000–$18,000 in additional cash due at the wire, on top of your down payment. If your savings account barely covers the down payment, you are not ready to make an offer. Earnest money — typically 1% or more of the purchase price, due within two business days of acceptance — comes out of that same pool.
Waiving the Inspection Contingency When You Don't Have To
With roughly 3.87 months of supply, Ferndale is not a market that routinely demands you waive your inspection to win. First-timers who hear "waive contingencies" as blanket advice and apply it to every offer are taking on risk that the current supply level doesn't require. Western Washington's wet winters create real inspection concerns in older homes that a few hundred dollars up front can surface before closing. Keep the inspection contingency unless your agent has specific, current evidence that a particular seller is fielding multiple offers.
Skipping Boundary Verification for Address-Specific Details
If assigned district boundaries matter to your household, verify them for any specific address before you write an offer — not during the inspection period. A two-minute lookup can prevent an expensive surprise. Confirm the details directly with the relevant authority; this guide covers the buying process, and the Ferndale schools page has the full breakdown.
Treating the Bellingham Commute as an Afterthought
The Bellingham commute averages about 20 minutes under normal conditions — but I-5 between Ferndale and Bellingham has predictable congestion windows, particularly southbound in the morning. If you're commuting daily, that 20-minute figure can stretch, and there is no meaningful transit alternative. Two cars per household is the practical baseline here. If you're planning to live car-light or commute by bus, Ferndale will frustrate you in ways that don't show up in a listing description.
Local Expert Takeaway: Ferndale's market in mid-2026 is balanced enough that first-timers don't need to panic-buy — but it's priced seriously enough that you need your financial house in order before you tour your first home. Get pre-approved, understand that $600,714 is the midpoint (not the ceiling), and keep your inspection contingency unless your agent tells you otherwise on a specific offer. After closing, you'll find yourself with a genuine small city: a walkable Main Street with independent dining spots, Hovander Homestead Park for weekend mornings, and a 20-minute drive to Bellingham when you need the city. The lifestyle is real. So is the price tag.
Quick Takeaways & FAQs
✅ Ferndale's balanced supply of roughly 3.87 months means first-timers can buy thoughtfully without the frenzied bidding-war pressure that defined the 2021–2022 market.
⚠️ The city median of $600,714 leaves little room for entry-level bargain hunting — older resale stock in the low-to-mid $500s exists but competes quickly, and new construction starts near $650,000.
📍 All Washington offers are written on NWMLS Form 21, and earnest money is due within two business days of acceptance — have that cash liquid before you tour, not after you win.
What credit score do I need to buy a home in Ferndale, WA?
How much do I need saved to buy my first home in Ferndale?
How long does it take to buy a home in Ferndale?
Is it a buyer's or seller's market in Ferndale right now?
Can I qualify as a first-time homebuyer in Washington if I owned a home before?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
