Maybe you've been watching Meridian from a distance — comparing it to Boise on a spreadsheet, noticing the prices are somewhat lower, and wondering if you can actually pull off a first purchase here. The honest answer: it's doable, but it demands more preparation than most first-time buyers expect. Meridian sits at the heart of the Treasure Valley in Ada County, straddling Interstate 84 and State Highway 55, with the kind of suburban infrastructure — new construction, strong community amenities, established neighborhoods — that draws tens of thousands of relocating families every year. That demand is exactly what makes the market unforgiving for buyers who show up underprepared.
The city's growth has produced a median household income of $100,795, which matters when lenders calculate how much house you can realistically carry. New mixed-use development like Heritage Square — announced downtown in July 2026 — and The Village at Meridian's ongoing expansion signal that Meridian isn't slowing down. For a first-timer, that's both a reason to buy and a reason to move quickly once you're ready.
Entry-level inventory is tight across the entire Treasure Valley, and Meridian's supply sat at roughly 0.97 months as of February 2026 — a deeply seller-favored market. Nearby Nampa and Kuna carry lower price points if budget is your primary constraint, but Meridian tends to hold value strongly over time. The lifestyle upside is real: Julius M. Kleiner Memorial Park is a genuine community anchor, Roaring Springs and Wahooz give families something to do within five minutes of most subdivisions, and the commute to downtown Boise runs about 20 minutes on a normal morning.
Whether you're comparing neighborhoods or deciding between loan types, the sections below walk through Meridian's first-time buyer reality, the step-by-step process, an honest budget snapshot, and the mistakes that most often derail buyers in this specific market.
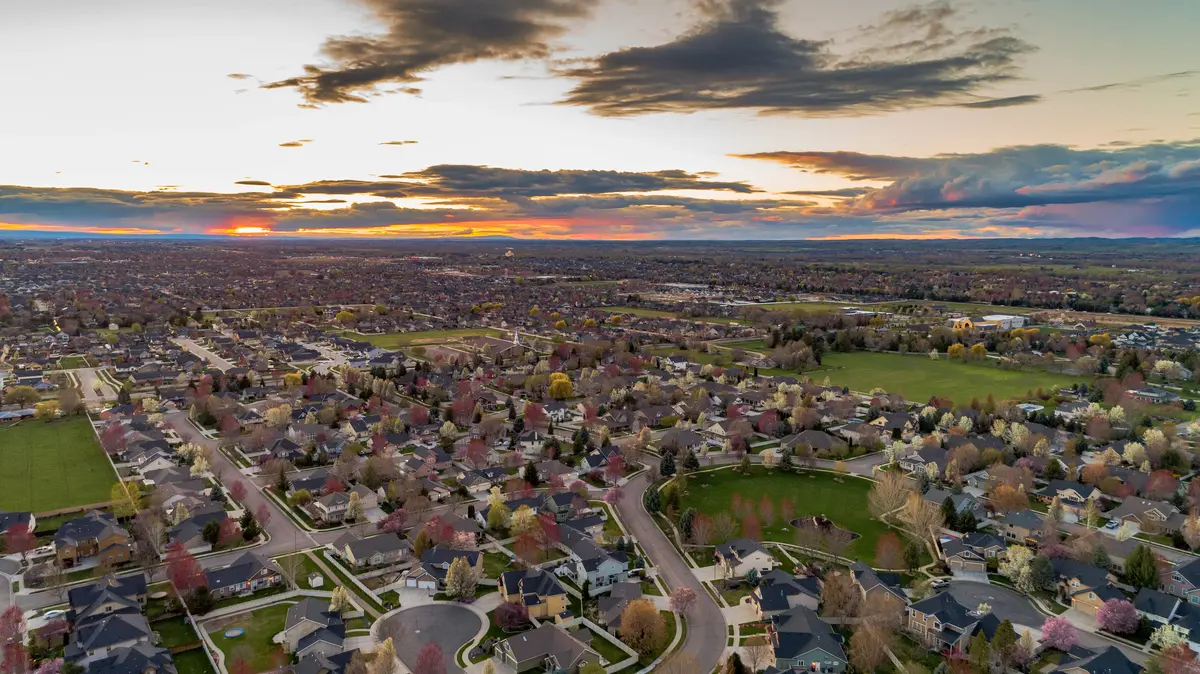
The Meridian First-Time Buyer Reality
The Zillow Home Value Index for Meridian hit $535,149 in May 2026 — a figure that puts the city squarely out of reach for buyers relying on a minimal down payment without a solid income to support it. That number reflects the full market, not just new construction. Entry-level options do exist, but they tend to be older 3-bedroom homes on smaller lots in established neighborhoods like Cedar Creek or Sonna, and they move fast.
Inventory is the defining reality here. With roughly 0.97 months of supply recorded as of early 2026, Meridian is nowhere close to the 5–6 months that signals a balanced market. When a well-priced home in Paramount or Sienna Creek hits the MLS on a Thursday, it often has multiple offers by Sunday. First-time buyers who haven't locked in pre-approval before they start browsing repeatedly find themselves a step behind.
The seasonal window matters. Historically, August through December sees higher supply and lower buyer competition in Meridian — making fall a strategically better time to make your move than spring, when out-of-state relocators flood the market. If your timeline is flexible, that shift alone can meaningfully reduce the pressure you'll face at the negotiating table.
The Homebuying Process in Meridian, Step by Step
Step 1: Get Pre-Approved — Before You Tour a Single Home
Pre-approval is not a formality in Meridian — it's the price of admission. A pre-approval is a lender's conditional commitment based on verified income, credit history, employment, and assets. It is categorically different from a pre-qualification, which relies on self-reported estimates and carries almost no weight with sellers here. In a market this competitive, sellers have been documented accepting lower offers from pre-approved buyers over higher offers from buyers who are only pre-qualified.
The Idaho 30-year fixed mortgage rate was running at 6.75% as of August 5, 2026 (per Zillow Home Loans), with a 15-year fixed option at 6.00%. Run those numbers with a lender before you fall in love with a floor plan. Know your ceiling before you set foot in a model home.
Step 2: Shop With a Clear Price Band and Neighborhood Shortlist
Meridian's neighborhoods each have a distinct character and a different commute reality. BridgeTower and Spurwing Greens sit on the northwest side near Ten Mile Road; Paisley Meadows and Saguaro Canyon offer newer construction farther south. Define which quadrant of the city aligns with your daily routine, then narrow your search before your agent starts scheduling tours.
Step 3: Write a Competitive Offer
In a seller's market, your first offer is usually your best chance. Lean on your agent for recent comparable sales — not just list prices, but actual closed figures. Escalation clauses can be effective on properties priced near the city median; your agent will know which sellers and listing agents are likely to respond to them.
Step 4: Inspection and Appraisal — Don't Skip Either
The inspection contingency is the one first-timers in Meridian most often waive under pressure — and most often regret. New construction in subdivisions like Paramount isn't immune to issues; HVAC sizing, grading, and framing details are all worth a professional eye. Waiving the inspection to compete is a real risk, not just a paperwork formality.
The appraisal is ordered by your lender and is separate from the inspection. If the home appraises below your offer price, you'll need to either renegotiate, cover the gap in cash, or walk. In a rising market, appraisal gaps are genuinely common — budget for that possibility before you're in the middle of it.
Step 5: Closing
Idaho is an escrow state, meaning a title company manages the closing process. Expect roughly 30–45 days from accepted offer to keys in hand on a financed purchase. You'll sign a significant stack of documents — review the closing disclosure carefully three business days before closing, when it's legally required to arrive. That's your last clear look at every cost before you wire funds.
How Much Home Can You Afford in Meridian
The table below uses approximate, illustrative figures to show how cash requirements shift across realistic Meridian entry points. Closing costs are estimated at 2–3% of the purchase price, consistent with the $2,000–$10,000 range typical for loan origination, appraisal, and title services in this market. These are estimates — your lender will provide an official Loan Estimate tied to your specific situation.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — lower entry | $400,000 | $14,000 (3.5%) | $8,000–$10,000 | ~$22,000–$24,000 |
| Conventional (3%) — lower entry | $400,000 | $12,000 (3%) | $8,000–$10,000 | ~$20,000–$22,000 |
| FHA (3.5%) — near city median | $535,000 | $18,725 (3.5%) | $10,000–$12,000 | ~$28,725–$30,725 |
| Conventional (3%) — near city median | $535,000 | $16,050 (3%) | $10,000–$12,000 | ~$26,050–$28,050 |
| Conventional (5%) — near city median | $535,000 | $26,750 (5%) | $10,000–$12,000 | ~$36,750–$38,750 |
| Conventional (10%) — above median | $620,000 | $62,000 (10%) | $12,000–$14,000 | ~$74,000–$76,000 |
All figures are estimates for planning purposes only; actual costs depend on lender, loan program, property taxes, and prepaid items. A licensed mortgage advisor will provide exact figures for your purchase.
Private mortgage insurance (PMI) applies to conventional loans with less than 20% down, and FHA loans carry mortgage insurance premiums regardless of down payment size — both add to your monthly carry cost. Down payments below 20% are common in Meridian among first-time buyers, but going in clear-eyed about the insurance cost is part of budgeting honestly. The interactive calculator below can help you model monthly payment scenarios once you've settled on a target price range.
Looking to buy in Meridian? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Meridian quote.
Common First-Time Buyer Mistakes in Meridian
Touring Before You Have Pre-Approval in Hand
This is the most common and most costly mistake in Meridian's market. Buyers who tour first and get pre-approved second routinely watch homes they want go under contract while they're still gathering W-2s. The pre-approval process takes one to three business days with a responsive lender — do it before you open Zillow.
Waiving the Inspection to Win a Bidding War
When inventory is tight, some buyers waive the inspection contingency thinking it gives them an edge. In established neighborhoods like Cedar Creek or Sonna, where homes were built 15–20 years ago, skipping the inspection can mean inheriting aging HVAC systems, settling foundations, or roof issues you'll pay to fix alone. The better move is an escalation clause or a faster close — not eliminating your only protection against a major defect.
Underestimating How Much Cash You'll Need at the Table
First-time buyers often budget for the down payment and forget that closing costs — loan origination, appraisal, title insurance, prepaid interest, and homeowners insurance escrow — can add $8,000 to $14,000 on a median-priced Meridian purchase. Arriving at the closing table short on funds is a real scenario that delays or kills transactions. Build a cash buffer of at least 4–5% of the purchase price into your savings target before you start making offers.
Buying Without Verifying Address-Specific Details
Meridian's neighborhoods can differ meaningfully by address — HOA rules, lot sizes, proximity to arterial roads, and community amenities all vary within what looks like the same zip code on a map. Buyers who fall in love with a subdivision's entrance and model home sometimes discover their specific lot backs a commercial corridor or carries a higher HOA fee than the model unit. Pull the full HOA disclosure and verify the specific lot's details before you write an offer, not after.
Treating the Rate Environment as Fixed
With Idaho 30-year fixed rates at 6.75% as of early August 2026, the monthly carry on a median Meridian purchase is meaningfully higher than it was three years ago. Some first-time buyers stretch to the top of their pre-approval ceiling at today's rates, betting on refinancing later. That's a reasonable strategy if your budget has room to absorb the current payment comfortably — but buying at the absolute edge of your approval leaves no margin if rates stay elevated longer than expected.
Local Expert Takeaway: Meridian rewards buyers who treat pre-approval as step one, not step three. The fall window — August through December — is historically the least competitive time to buy here, and that seasonal advantage is real. Budget for $25,000–$40,000 in total cash depending on your price point, don't waive your inspection on a home near Sonna or Cedar Creek, and verify every address-specific detail before you fall in love with a floor plan. The market is competitive, but buyers who show up prepared with verified financing and a realistic cash cushion close — the ones who don't are usually the ones still renting a year later.
Quick Takeaways & FAQs
✅ Meridian's Zillow Home Value Index hit $535,149 in May 2026 — a real market, with real entry-level options for prepared buyers who budget for total cash needs, not just the down payment.
⚠️ With only about 0.97 months of housing supply as of early 2026, Meridian is a deeply seller-favored market — first-time buyers without a pre-approval letter in hand routinely lose homes to buyers who have one.
📍 The fall buying window (August–December) historically brings more inventory and less competition in Meridian — a meaningful timing edge if your move date is flexible.
What credit score do I need to buy a home in Meridian, Idaho?
How long does it take to buy a home in Meridian from start to finish?
Is fall really the best time to buy in Meridian?
Can I buy in Meridian with a 3% down payment?
What are closing costs in Meridian, and who pays them?
Moving to Idaho?
Tell us what you need help with and we'll connect you with local resources.
